
Tonight’s RBA meeting is more interesting than usual. Yields might be set to break to the upside and encourage USD seasonality.
No beating around the bush in the 70’s!
Tonight’s RBA meeting is more interesting than usual. Yields might be set to break to the upside and encourage USD seasonality.
No beating around the bush in the 70’s!
08AUG EURUSD
1.0970 put for ~32 pips
Target 1.0830 (spot ref 1.1045)
Short GBPUSD at 1.3080
Stop loss 1.3026 (was 1.3226)
Take profit 1.2757
July 31, 2023
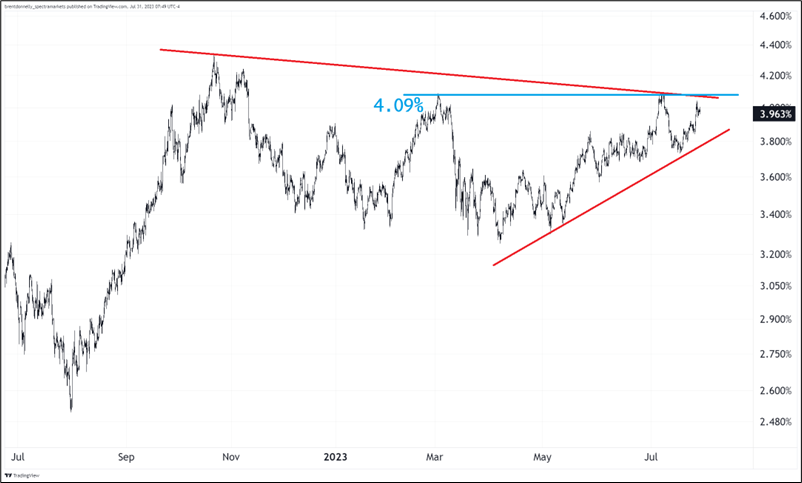
The BOJ is trolling the market in recent days, as they leaked their policy decision 12 hours before the meeting and then conducted a Rinban last night to keep JGB traders on their toes. I suppose if the BOJ is trying to avoid a VAR shock in JGBs, they may succeed, but there needs to be a release valve somewhere, in this case a weaker JPY. It looks like it’s off to the races again for USDJPY. The pair should once again recouple with US yields and so the ultimate path of USDJPY from here will be determined by whether or not that epic 4.09% double top in the US 10-year yield holds or cracks.
With oil rallying, the Atlanta Fed GDPNow at 3.5%, housing markets fine, jobs market tight, services solid, and manufacturing set to rebound… I would bet that red triangle in this chart is most likely to resolve up and through 4.09% in the coming days.
Today is the last day of the month and while I have written extensively about how month-end has not been predictable post-COVID and month-end models have been highly unprofitable, it’s still always worth staying on high alert for real money hedging. Last month, for example, month-end activity followed the standard playbook, but on balance there has been no edge in following the month-end models in recent years.
Once month-end is out of the way, we enter a seasonal period where the USD tends to do well, and we will get a flurry of data that could fire up that seasonality right away. Tomorrow’s ISM Manufacturing is of particular interest and my lean is that the release will be strong. I’ll write out my logic in more detail in tomorrow’s am/FX. Have to run a few spreadsheets first to confirm or deny my suspicions.
Tonight’s RBA meeting is another interesting one as economists are close to split (18 calling for a hike, 12 calling no change) while the market has priced in only a 13.4% chance of a hike. That is a huge dispersion and it’s rare to see such a wide gulf between market pricing and economists’ expectations.
The policy tension is similar to what we see with other central banks.
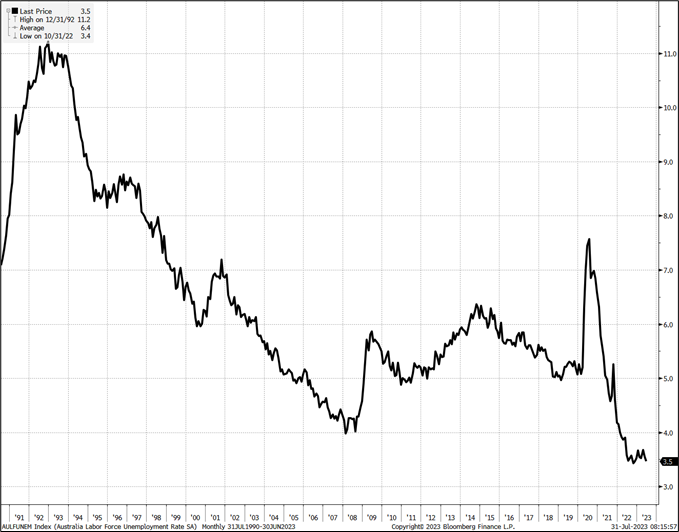
Levels of inflation are high and above target, but momentum and change are highly favorable. With the RBA still suffering from a credibility problem, inflation still way above target, and the Unemployment Rate less than a tick from the all-time low, there is a solid argument for a hike.
It’s tempting to go long AUDUSD or AUDJPY for a hawkish meeting, especially with commodities looking firm. As I have been discussing for a while, this oil rally feels much more organic and less speculative than other CL moves in 2022 and 2023, and copper is finding its footing too. Long AUDJPY probably makes sense, but the entry point is gross as we went all the way to 91.90 on the BOJ madness and we now trade above 95.50. I can’t bring myself to lift an offer up here, but it’s probably a reasonable thing to do!
Another reason I can’t pull the trigger on long AUDJPY is that there is a wildcard here around the fact that Philip Lowe is on the way out soon—this is his second last meeting. He will preside over the September 5th meeting, then Michele Bullock will take his seat on September 17th. Also, the seasonality of AUD in August is sketchy. Here are the seasonals for four major pairs with August circled.
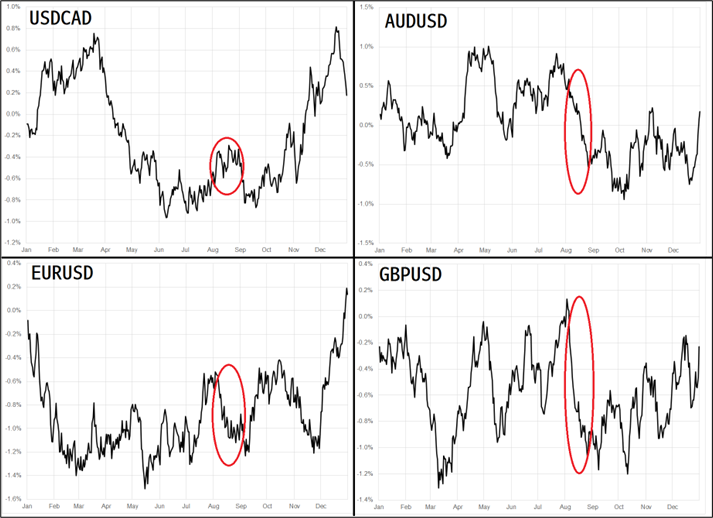
Given my views that commodities are going higher, and manufacturing looks like it’s bottoming, long USDCAD doesn’t make any sense anymore so I will square that one up for a small loss. Based on seasonals, beta to manufacturing, and correlation to commodities, it’s far less attractive than EURUSD or GBPUSD and really makes no sense at this point.
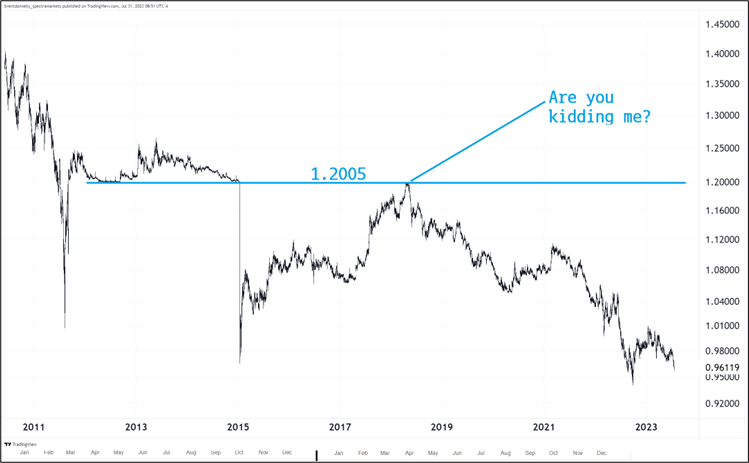
I have been thinking a lot about CHF lately because I think it’s in overshoot territory and the SNB will pivot soon to a policy of no CHF-buying intervention and a much more dovish policy message. I haven’t done anything about it because the SNB meeting is so far off and these raging CHF-positive trends can persist for ages. Anyway, I was looking at the daily chart and was reminded of the insanely perfect retest of 1.2000 in 2018. The most incredible example of all time of how old support becomes resistance. This chart deserves a spot in a technical analysis textbook! Note the SNB floor breaks, we go to 0.85 (lows not properly captured by this chart) and then we retest 1.2000 perfectly before crumbling all the way back down to new lows. Incroyable.
If you have a 6- or 12-month carry trade view, I think using CHF as a funder is absolutely awesome right now.
New Zealand and US jobs reports this week are going to be exciting.
Have an electric week.
Loud and clear, sir!


This piece is mostly for people who are interested in backtesting
This could be a consolidation week as crosswinds now blow in FX and equities
