• USD higher is no longer a one-way bet.
• Rates higher is no longer a one-way bet.
• Risk parity could do OK from here.
• I am bullish GBPUSD, and bullish AUDUSD.
A meme that explains why markets
are not always efficient

• USD higher is no longer a one-way bet.
• Rates higher is no longer a one-way bet.
• Risk parity could do OK from here.
• I am bullish GBPUSD, and bullish AUDUSD.
A meme that explains why markets
are not always efficient
Stop loss 0.6684
Take profit 0.6994
Stop loss 1.1374
Take profit 1.1839
Stop loss 1.4884
Take profit 1.5684
September 8, 2022
I have been talking about GBPUSD and USDCNH and specific trade ideas a fair bit of late but today I want to zoom out and look at how much things have changed in recent weeks. The global macro story today and the current regime are quite different from the one that has dominated for most of 2022.
Fixed income no longer looks like a one-way bet. The speech by Lowe last night is another example of the somewhat obvious yet still relevant idea that central banks hike much faster when moving from extreme accommodation to neutral than they do once they near neutral or mildly restrictive territory. Lowe’s speech is worth a read (link here). The key line is:
We are conscious that there are lags in the operation of monetary policy and that interest rates have increased very quickly. And we recognise that, all else equal, the case for a slower pace of increase in interest rates becomes stronger as the level of the cash rate rises.
This is consistent with Brainard yesterday who spoke of overtightening risks. The Fed is going to a slightly more two-way framework as they approach neutral.
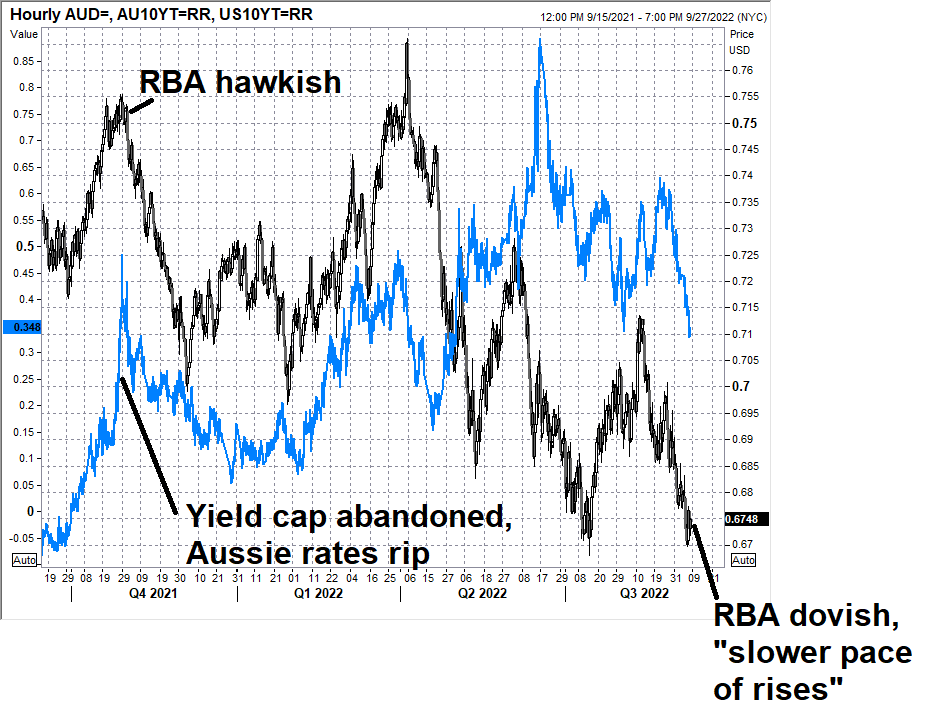
A point to keep in mind on AUD. The drop in AUDUSD is probably unwarranted because Australian rates and the currency have not been especially correlated and if the RBA commentary is a sign of slower rate hikes globally, that could be good news, not bad. Recall that AUD peaked pretty much the same day the RBA went super hawkish and abandoned yield curve control.
This does not mean that a dovish RBA is automatically bullish AUD. But the overall direction of global rates (and specifically US rates as the high beta) is what matters. Along with commodities of course. Here’s AUDUSD vs. copper:
When the central banks start pushing back against USD strength, it does not always mean you just go short USD and get rich. But it does mean that the long USD trade becomes choppier and more difficult. Long USDJPY or long USDCNH right now and you are fighting a massive battle with government authorities. The thing is, these authorities don’t always win. For the JPY pushback to be credible, the BOJ will need to hint at a removal of yield curve control as a remedy for JPY weakness. So far, it’s been the MOF leading the charge on commentary and without the BOJ on board, the commentary is not credible. Currency policy and monetary policy need to be pushing in the same direction or the currency policy is destined to fail.
Also this headline yesterday is relevant, even if it’s an obvious point.
*BRAINARD NOTES POTENTIAL FOR STRONGER USD TO COOL INFLATION
I am bullish GBPUSD though I acknowledge there is a huge battle for the soul of the pound right now as the debate rages over whether fiscal is good or bad for the currency. My belief is the USD has shown us that loose fiscal / tight monetary is good for the currency despite initial worries about sovereign credit. Are we really worried about UK credit? Seems far-fetched to me.
In other USD pairs, I think it’s time to sell USD calls, take profit on USD longs and look for spots to get short dollars. The risk, though, is that we chop around for a while. Central bank pushback on USD strength does not mean the dollar just does an instant 180. They often get tested before eventually winning.
The excessive bullish tone in July that manifested through yet another meme stock mini bubble is gone. It’s getting a bit less clear to me that stocks need to go down from here. The Fed is committed to tightening financial conditions one day and the next day you get Brainard sounding dovish. Maybe the soft landing narrative is going to come back for a while. This is a bad seasonal period for equities, generally, but seasonals don’t work 100% of the time.
Central banks are slowing down a bit as they approach restrictive territory. Central banks are pushing back against USD strength. There are two-way risks again for bonds, the USD, and stocks as the great risk parity collapse of 2022 looks to have run its course for now. Bullish. I’m adding long AUDUSD with a stop at 0.6684 to my trades as I think we are entering a new regime where the USD struggles and risk parity does OK. Have a simian day.
https://twitter.com/buyerofblood/status/1545213572720250882?s=12&t=ZxPVJoMws6HZxozImqmuYQ
Meme explains why EMH is not always useful

This piece is mostly for people who are interested in backtesting