Yesterday’s FOMC was not the quiet nothingburger I had expected. Tail risk is back in bond volatility and RHS USD moves.
Does not bode well for my BRL view but the data will ultimately decide what’s what, not Jerome Powell.

Yesterday’s FOMC was not the quiet nothingburger I had expected. Tail risk is back in bond volatility and RHS USD moves.
Does not bode well for my BRL view but the data will ultimately decide what’s what, not Jerome Powell.
There is an incomprehensible
number of possible QR
codes. We will never run out.
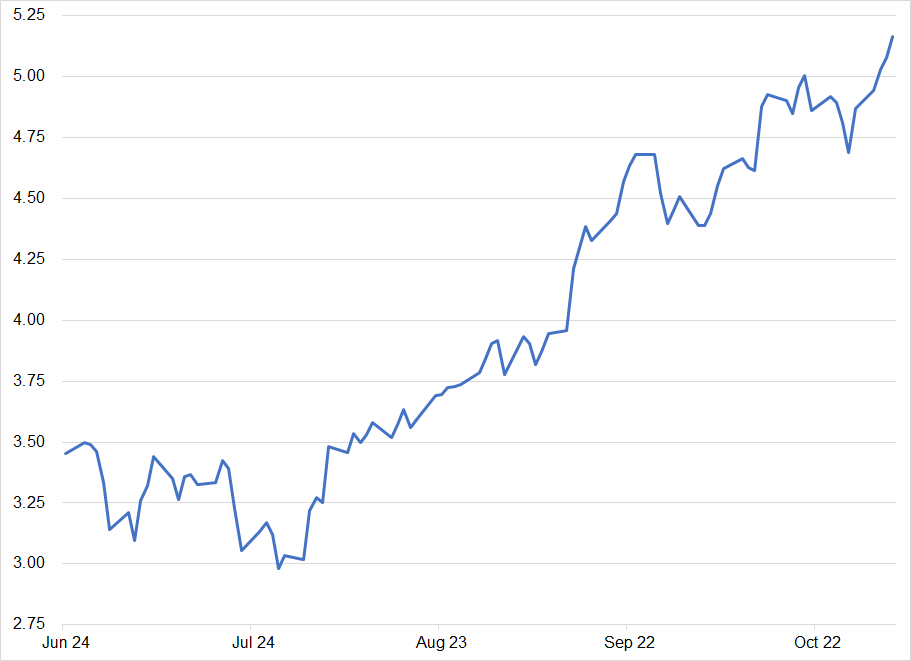
Spot ref. 5.1850 on 10OCT22
Expires 11JAN23
November 3, 2022
I am surprised that Powell referred directly to a higher terminal rate yesterday. My view going in was wrong. I expected a noise meeting where the Fed elects to keep quiet and wait for the deluge of data between now and the December 14 FOMC. At that meeting, they will have so much new information and a new set forecasts. Instead, Powell directly mentioned a higher terminal rate and the market did this:
This implies Powell and Company have high confidence in the level of neutral, the impact of >5% Fed Funds compared to that neutral rate, the lagged impact of past hikes, and the forward path of the economy. I don’t know why they would have that much confidence. I still believe the data is in control and while this move higher in yields makes sense given Powell has explicitly endorsed it, it’s worth keeping in mind that he might just end up being wrong again.
They were wrong on transitory, they were wrong about not needing to hike 75bps (as I outlined yesterday) and they were also wrong in October 2018 with the epic unforced error when Powell said the Fed was a long way from neutral. Here’s what actually happened:
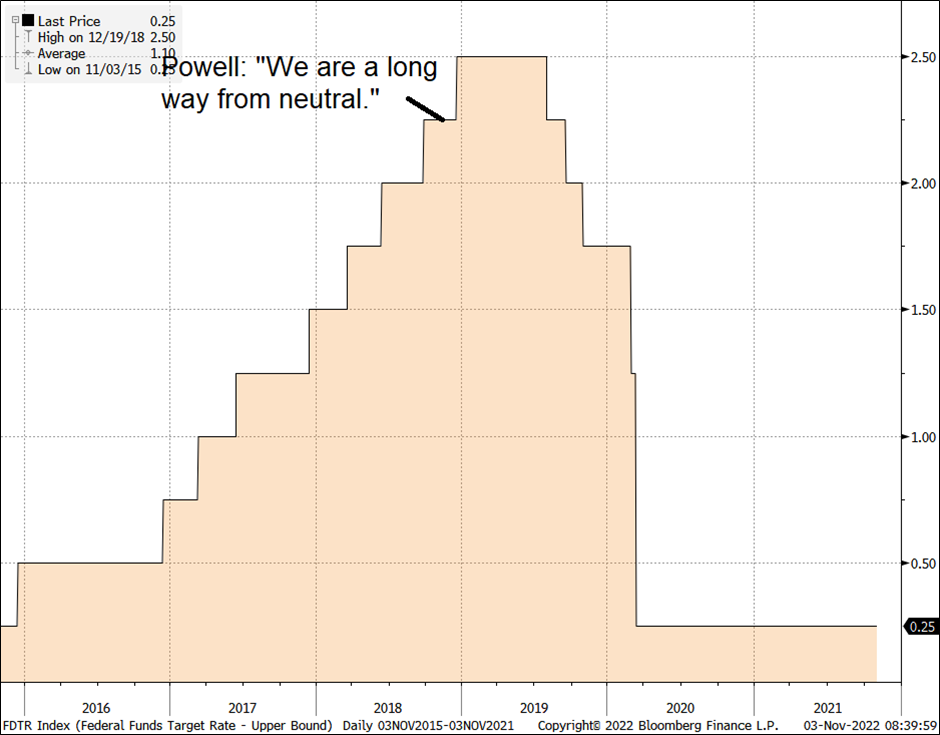
They hiked once. One. More. Time. And this is what 2-year yields did:
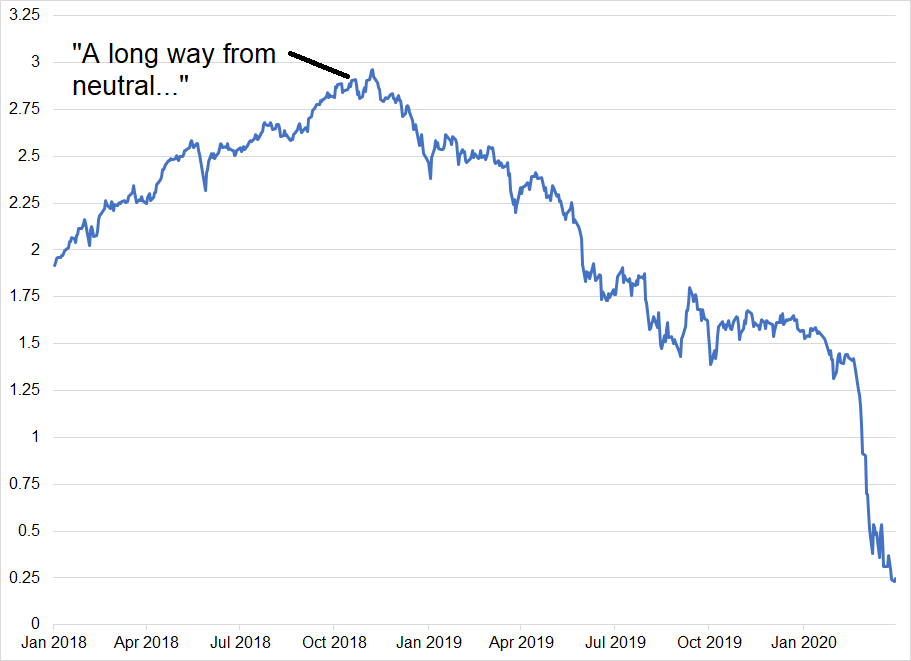
I am not saying Powell is wrong about the terminal rate. I am saying he doesn’t know. Neither do we. Two soft NFPs and two lowball CPIs and Powell will be adding this line to his growing list of erroneous pledges:
“We still have some ways to go, and incoming data since our last meeting suggests that the ultimate level of interest rates will be higher than previously expected.”
It sure rhymes with his “long way from neutral” comment in 2018 and he has had uncanny bad timing before. Couldn’t he have just shown some humility and said: “the ultimate level of rates may be higher” instead of “will be higher.”?
To new readers: I am not a Fed hater in my bones. I was a Fed apologist for most of my career because their job is wildly difficult, private sector forecasts whiff just as frequently as Fed forecasts, and policymakers are often in no-win situations. But to me, this Fed is different. It’s political (waited for renomination before hiking, even though they knew it was time to hike), it’s illogical (buying MBS in 2022 in the middle of a housing bubble), and it’s unethical (trading ahead of announcements, resigning, and moving to cushy private sector jobs while still going after and banning bank traders who committed far less egregious (or not even unethical) actions).
Surveys are usually boring. I have been told this one is mildly interesting. If you have not yet completed it, please take the five minutes if you can! It’s some trader research I’m dong as a follow up to Alpha Trader. Thanks!
I hope your P&L is $2^23624.
A 76X76 QR Code can hold up to 2,953 bytes or 23,624 bits. Since each bit has two states, the number of possible permutations for a QR Code is 2^23624.
Think about every particle in the observable universe. Inside each of those particles, you put every single particle in the observable universe. And then you repeat that hierarchical structure 21 times, and you still don’t have enough particles to match a 76×76 QR array’s possible combinations.
HT JR