
There is so much data between now and the December 14 FOMC meeting. That data is more likely to move terminal Fed Funds than this week’s November FOMC meeting.
Guess which one
was born in 1946

There is so much data between now and the December 14 FOMC meeting. That data is more likely to move terminal Fed Funds than this week’s November FOMC meeting.
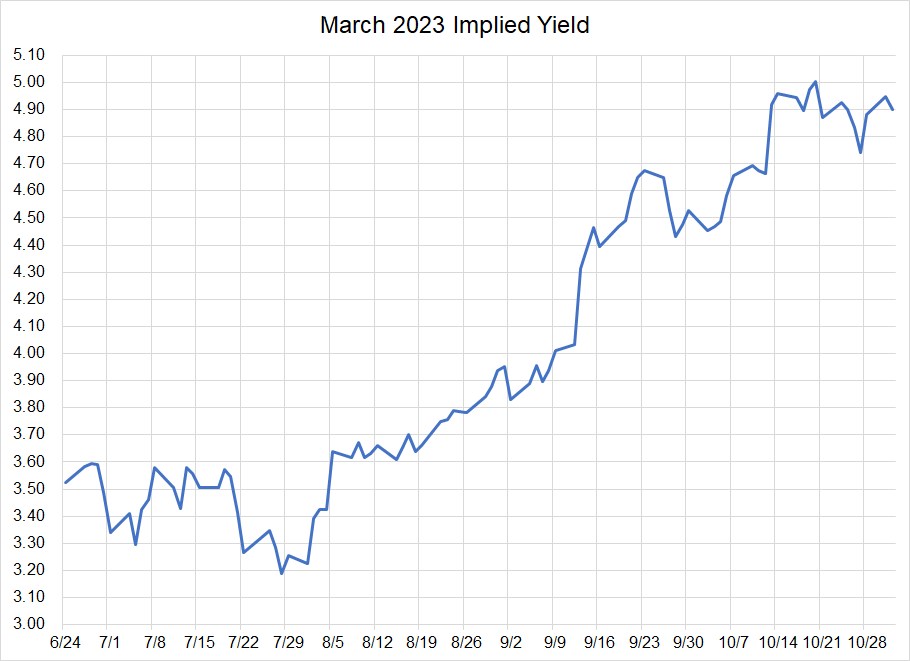
Guess which one
was born in 1946
Spot ref. 5.1850 on 10OCT22
Expires 11JAN23
November 1, 2022
This could be one of the least important Fed meetings in a year full of crucially important Fed meetings. With two CPIs and two NFPs between now and December 14 FOMC, the Fed can lay out any plan they want. The market has made its decision that terminal Fed Funds is ~5%. It will take data, not fed commentary at a non-SEP meeting, to move the Terminal Fed Funds needle off 5.
This year has been a story of rising terminal rates leading to economic downturns and various tail risks. These rising pressures have created the big blue X on the next chart, where higher terminal rate = lower stocks.
Now, the two tail risks, the “EU is going to shut down because there is no energy” tail, and the “bond vigilantes are going to blow up the UK, and probably trigger a sovereign debt crisis in the United States, too” tail have dropped from DEFCON 1 to DEFCON 4 in four short weeks. This has allowed the terminal rate to edge higher and stabilize around 5% with stocks higher (green lines on the chart).
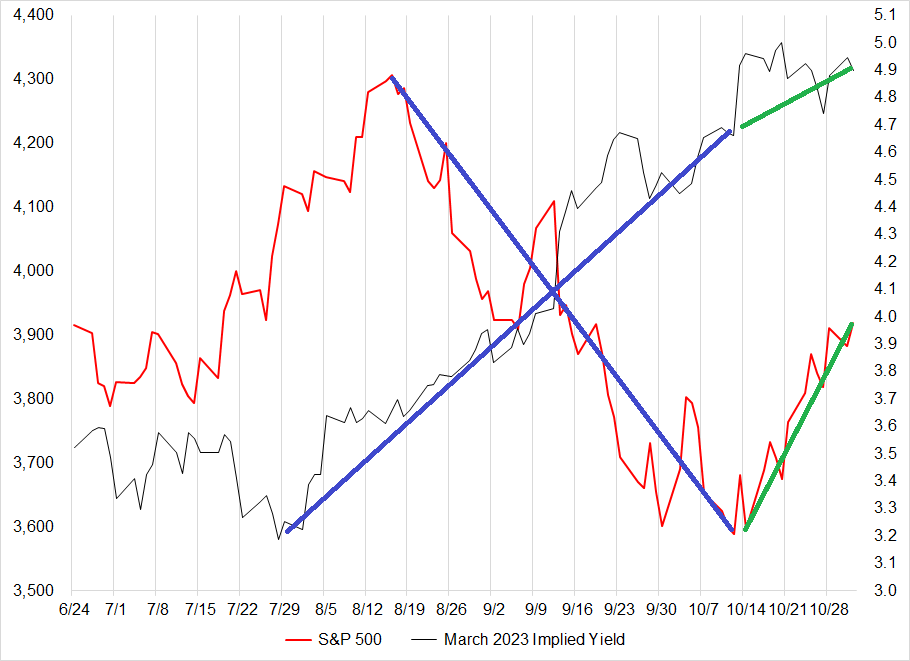
Now, we get some kind of random unsourced news about China reopening less than two weeks after epic China malaise triggered by headlines suggesting Xi is out for world domination by 2049. It is worth noting that was the takeaway from the 2017 Party Congress, too. To me, the what (booming market reaction to weak news) is more important than the why (are rumors of a “reopening committee” true?).
China growth and China equities are a classic bombed out sentiment story and I would not be surprised if an improving China credit impulse and eventual reopening leads to a much more positive story for China in 2022. If that’s right, it’s probably bullish NZD, THB, and oil as it will be a consumption story, not a capex story.
Everything that is happening right now is a transition from apocalyptic to rather bad. Particularly outside the USA, mortgage resets, corporate debt rollovers, weak PMIs, and all that don’t suggest we are going back to the days of Roaring 20s magazine covers any time soon. But for now, the market is focused on Fed terminal rate, China reopening, and unwinding tail risks… The jury is still out on the 2023 economic outlook as the 3m/10y inversion signals a recession at some point out there, but who knows when.
Here is SPX (log) vs. prior 3m/10y inversions:
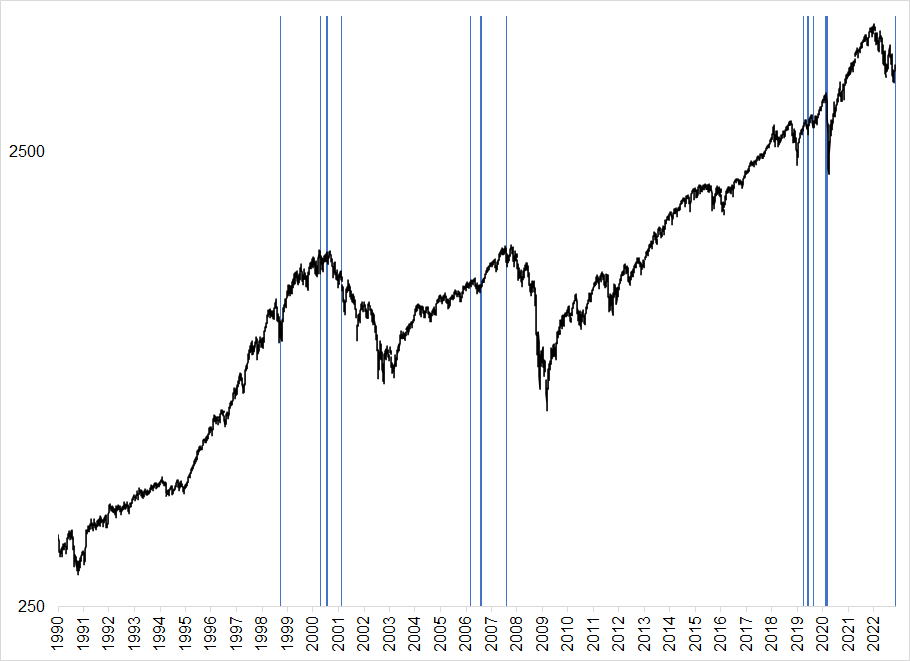
Rule is: If curve was not inverted 10 days ago, and it is inverted today, insert blue line
It’s an early warning system, but not tradable. One thing worth noting is that this cycle is nothing like prior cycles and so the usefulness of this indicator for trading is probably even lower than usual. The first inversions in 1998 and 2006 both preceded multi-year continuations higher in stocks, but this one comes after a huge drop in stocks. Those cycles featured very little inflation, and rapid Fed pivots. This cycle features high, sticky inflation, and a Fed pause. I would say that even though the 3m/10y is a good predictor of eventual recession, it’s basically useless for traders and investors. Initial Claims are a better real-time indicator of the US economy. And the recession could come slower this time as the labor shortage keeps people in jobs longer than in past cycles.
My Brazil view has been mildly disappointing but not disastrous so far. The first promising turn of events took place yesterday as Lula won and Brazil rallied. This is consistent with the main part of my thesis on the trade which was that the resolution of uncertainty would be more important than the actual result of the election. While uncertainty has not been completely resolved, this price action in EWZ yesterday is encouraging:
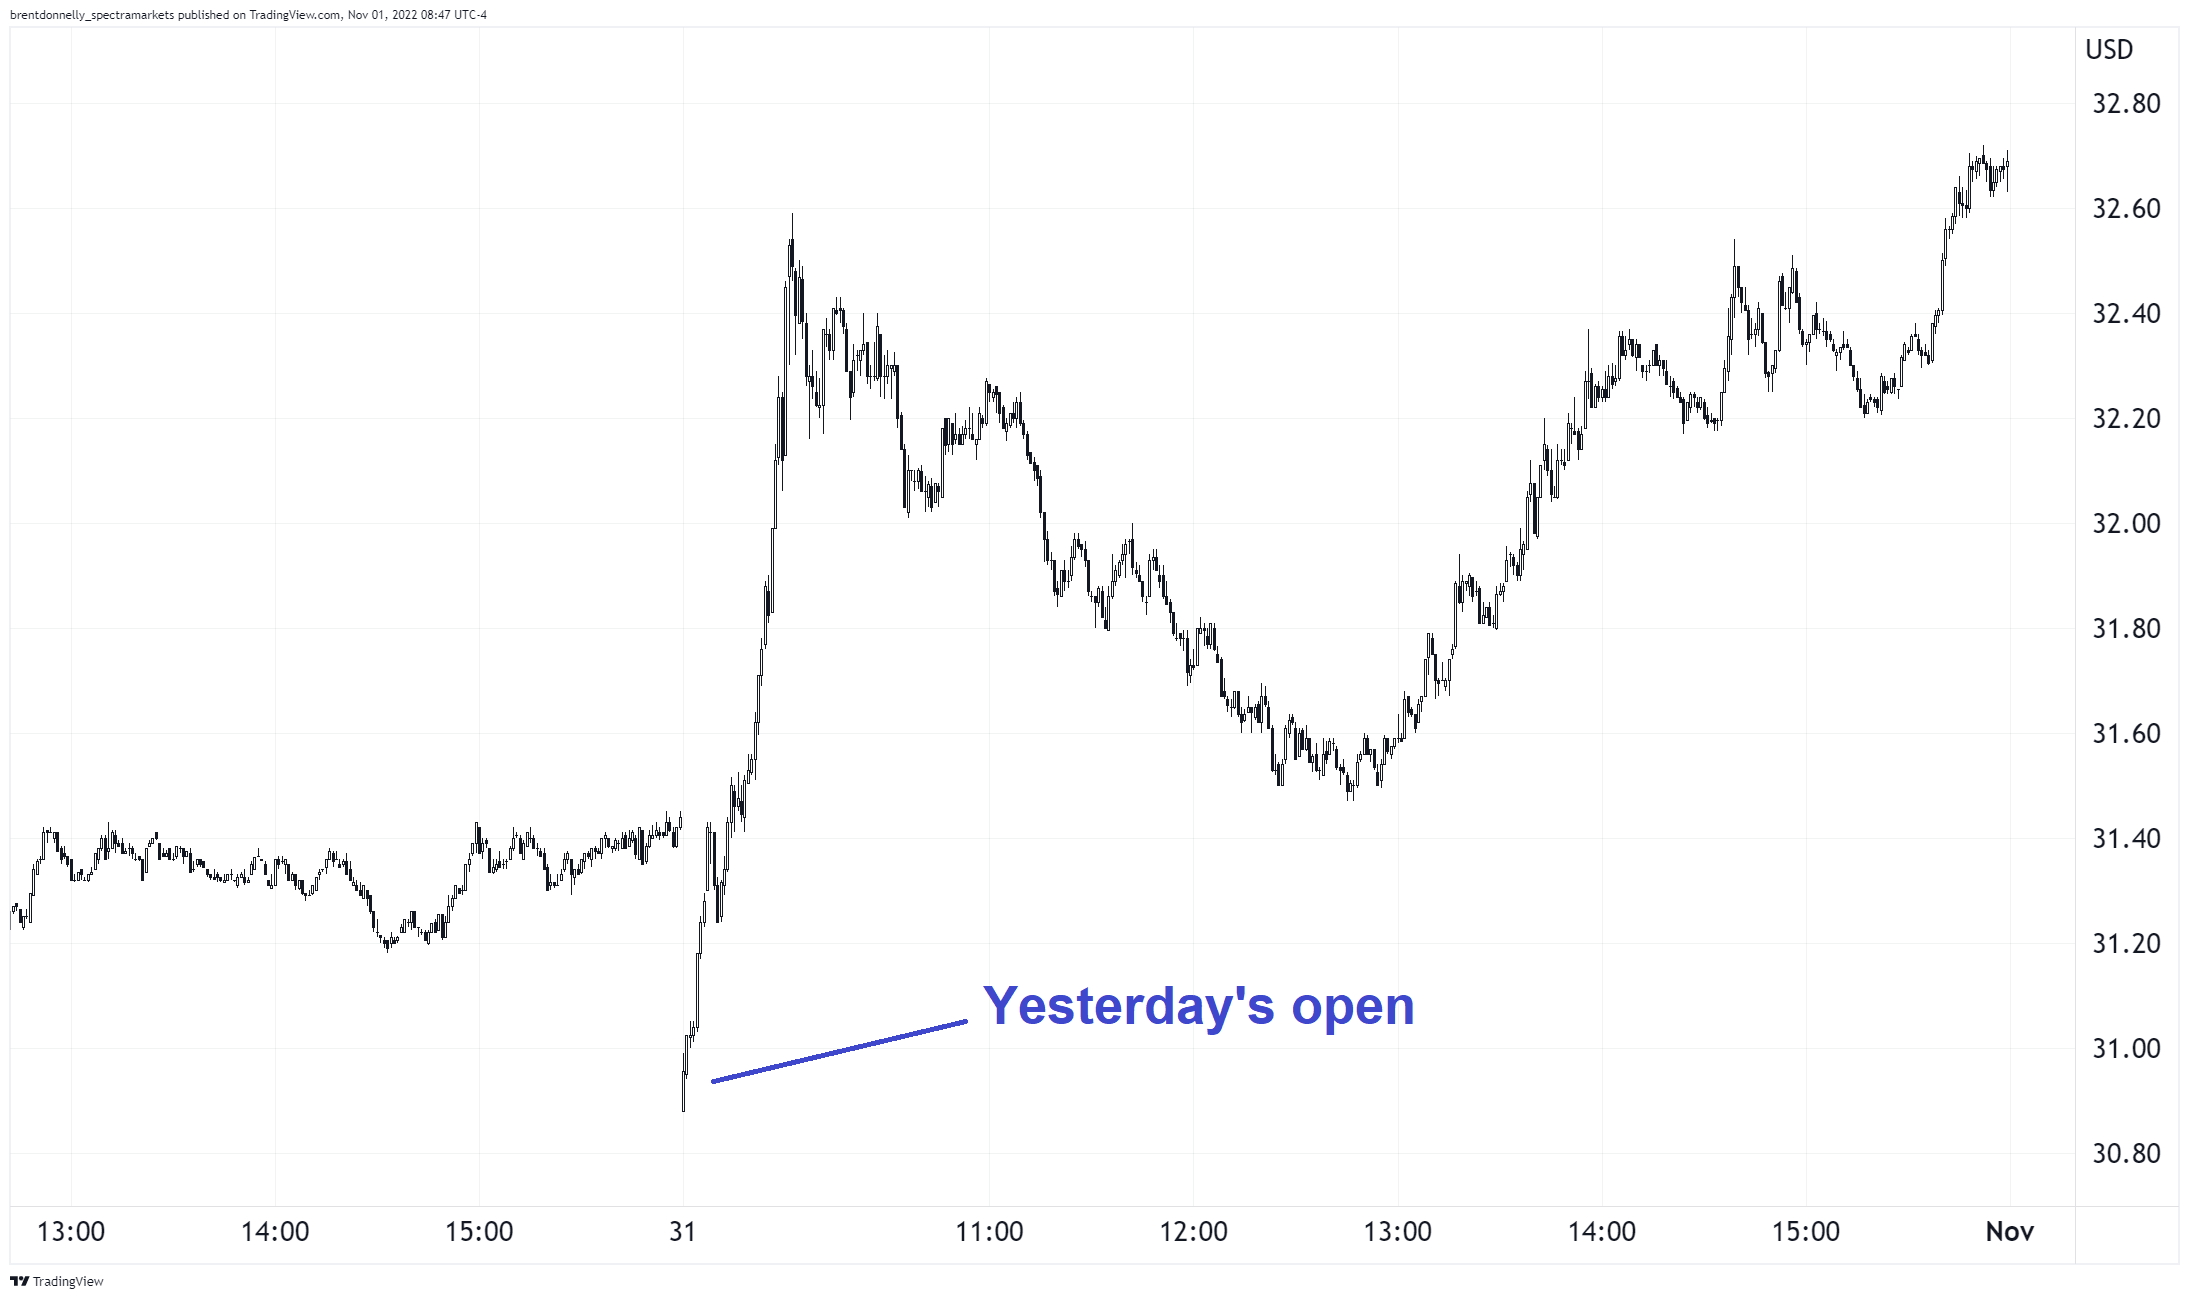
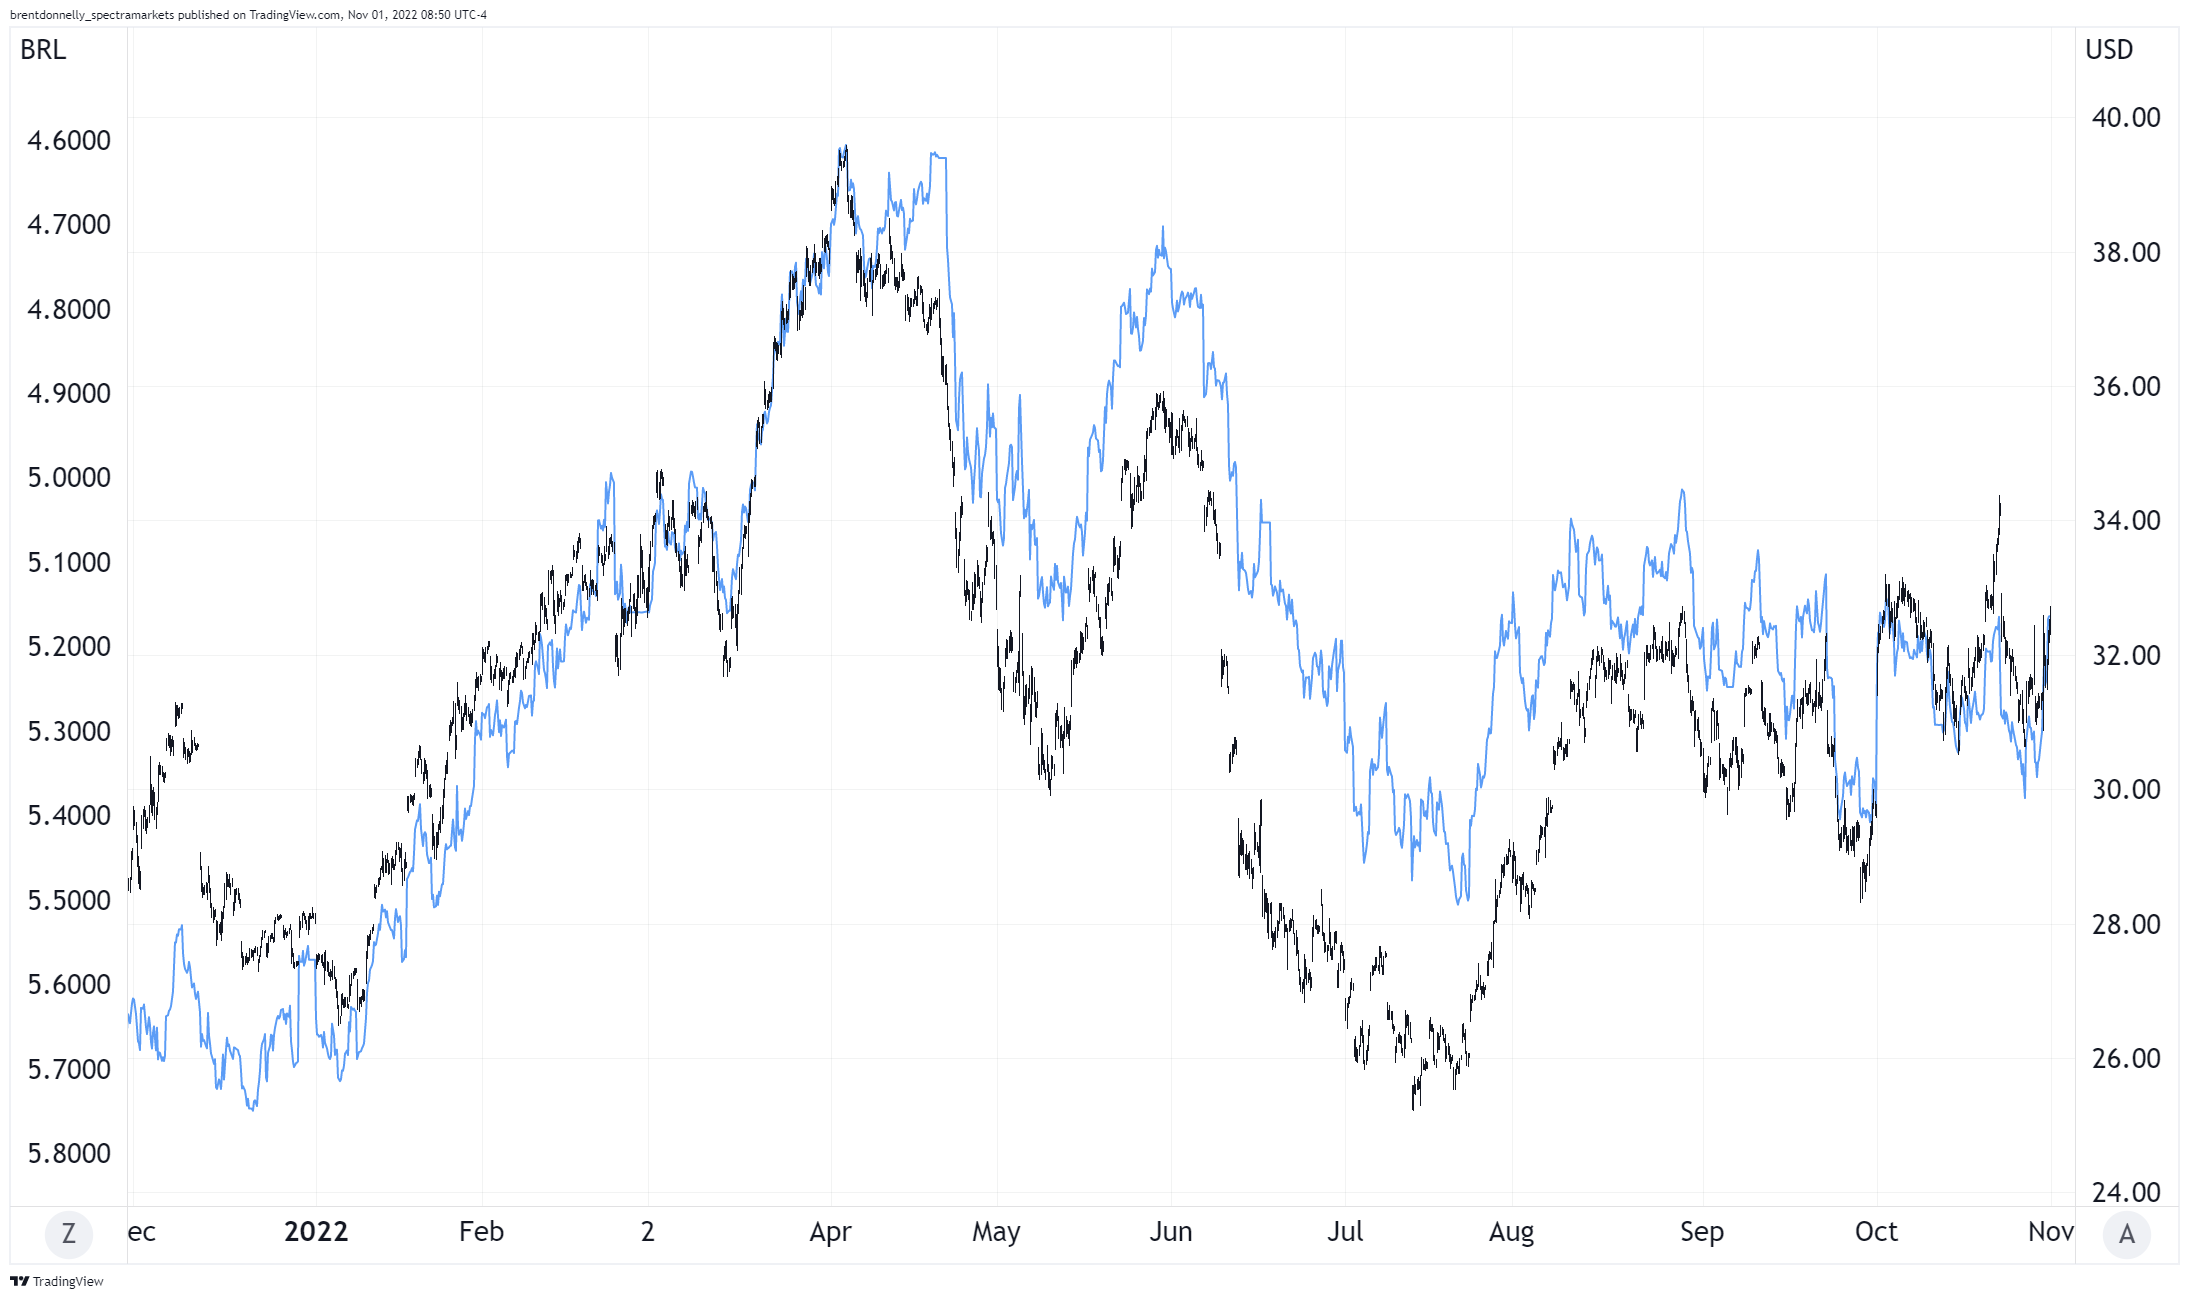
I am a tourist in Brazil and thus I think of EWZ and USDBRL as the same thing. They are not quite the same thing, of course, but it’s a reasonable heuristic. Here’s USDBRL and EWZ, compared.
There are so many good finance websites and Substacks, etc. that it can be hard to keep track. I find this site useful (app.harkster.com) as a curator of finance content, especially for global macro. Curation is such an important function in today’s internet. Full disclosure: I have no financial relationship here, but I am friends with one of the guys running it. I’m linking to it because I think it’s good, not because we’re friends. They are also linking to me. A part of my business model here that I have stumbled into is that I amplify good finance content for free, when I believe in it, and I get reciprocal amplification if that promoted person so chooses. No quid pro quo though, yo.
Have a boomer of a day.
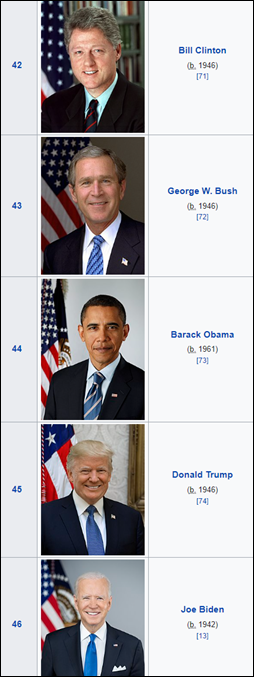
Birth year of winning candidate of the last eight US presidential elections:
1946
1946
1946
1946
1961
1961
1946
1942
Oh… And Lula was born in 1945.
My dad was born in 1944. I hope I am not leading a large nation at age 80; I would hope to be chilling by that point.
https://twitter.com/derektmuller/status/1586081695849418753?s=20&t=ULZHuH256_Bz9a_pv1uPVA
via DG


This piece is mostly for people who are interested in backtesting

