
The USD is underreacting to the move in yields, so far.
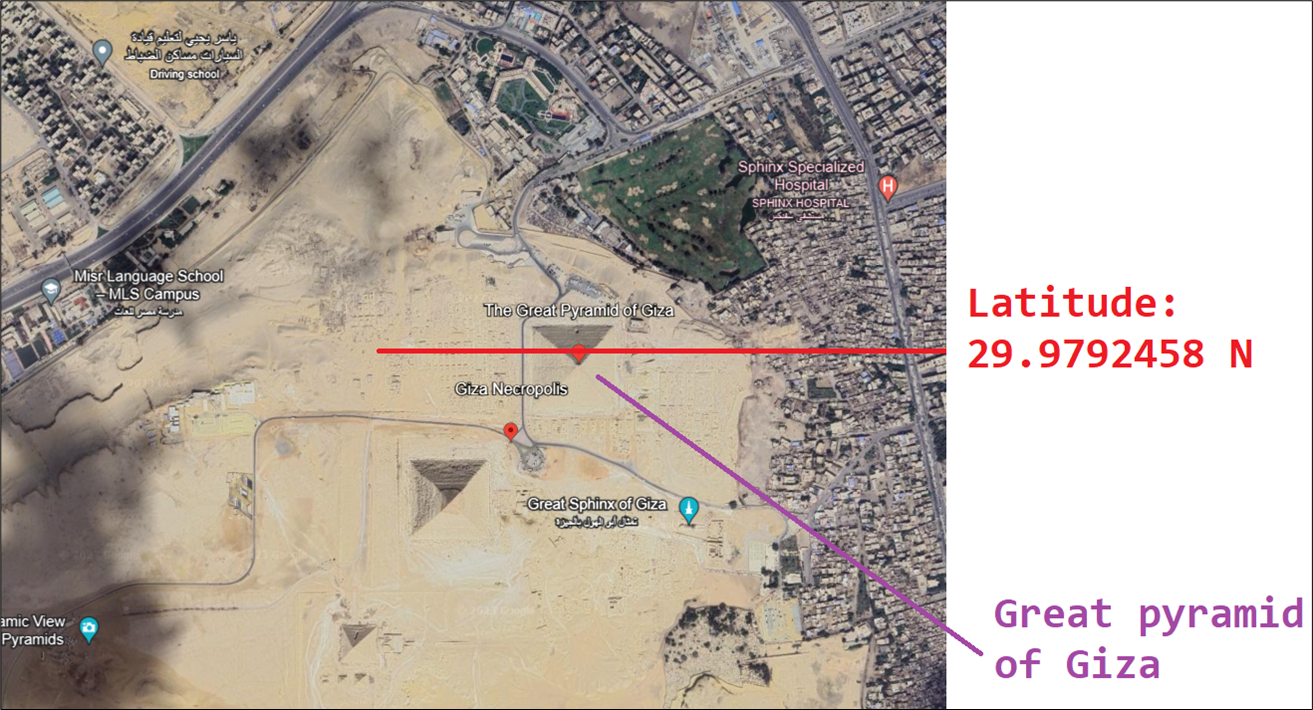
The line of latitude 29.9792458 N passes through the Great Pyramid of Giza.
The speed of light is 299,792,458 meters per second.
Probably nothing.

The USD is underreacting to the move in yields, so far.
The line of latitude 29.9792458 N passes through the Great Pyramid of Giza.
The speed of light is 299,792,458 meters per second.
Probably nothing.
Short CADJPY at 108.90
Stop loss 110.26
Long 10DEC EURMXN
18.70/18.20 put spread
~50bps EUR
off 19.16 spot
November 2, 2023
One of the most glaring features of the current FX market is the divergence between some rate differentials and the associated currency pairs. For example, AUDUSD, despite a 2% rally off the lows, is still way undershooting rate differentials.
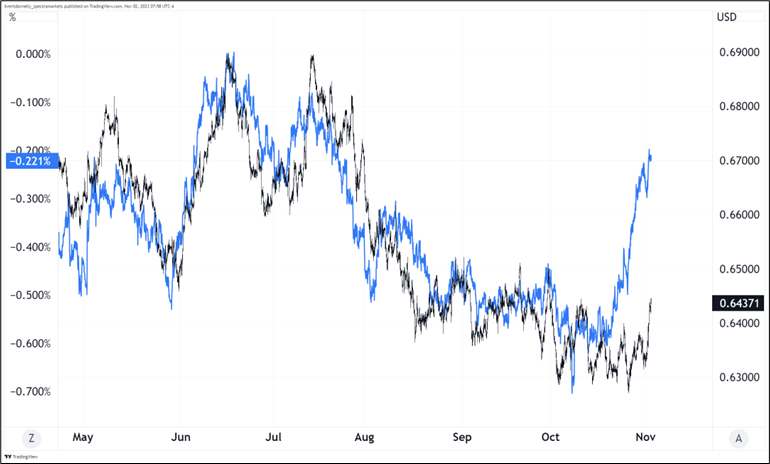
AUD has been where P&L goes to die this year, but it’s worth noting that the yield differential move in June showed the way higher for AUDUSD while the same thing happened in early July (UP) and late July (DOWN). Look how the blue line was ahead of the game on those moves.
The beef with Oz is the structural balance sheet recession problem in China, but using China and Aussie terms of trade as a framework for trading AUD has not worked for years because there is so little transmission from commodities to RBA policy. Now, regardless of what’s going on in China, Aussie rates are making a late cycle catchup move after lagging for ages. Negative real rates in Australia have been the bane of the currency and now the RBA is kind of sort of normalizing.
The main point here is that the framework for trading AUD should be that yields are more important than the outlook for China growth or commodity prices, though obviously if you’re long AUD you’re cheering for higher copper prices.
This AUD yield move has been a thing for a while, so this is not a breaking news update. People have already bought AUDCAD calls and taken profit on them over the past week or so. And NFP is tomorrow. But AUD should remain firmly a buy dips currency as long as there isn’t a massive reversal in the rate differential.
JPY looks similar. The US vs. Japan differential is driven more by the US but Japanese yields have had a part to play, too. The market is long a lot of USDJPY cash and topside, and the whole narrative has changed. What was a panic over UST supply a week ago is now falling yields and instant calm as the US Treasury and Fed are not blind to the implications of higher yields and they have responded calmly and appropriately to the runup. Here’s the USDJPY overlay:
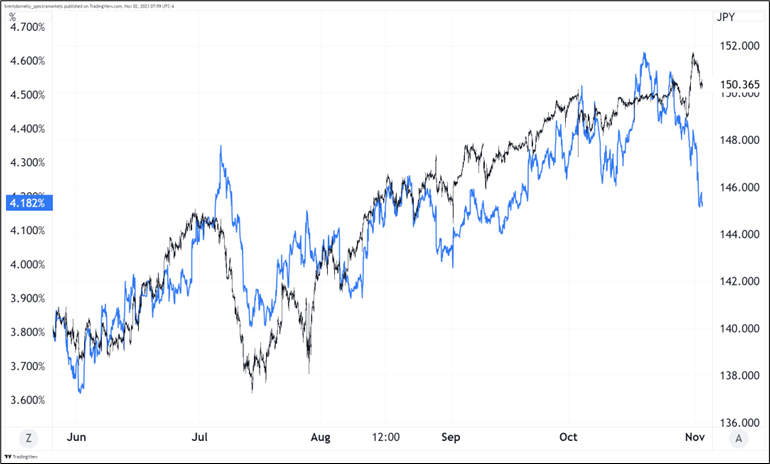
This would be an absolute genius moment for the MOF to intervene, though central banks generally prefer to keep intervention as a last resort. They are less opportunistic and tend to just wait until they are backed into a corner.
To me, it looks like USDJPY is going to 148 on its own anyway.
The EURMXN put spread is alive after a near death experience.
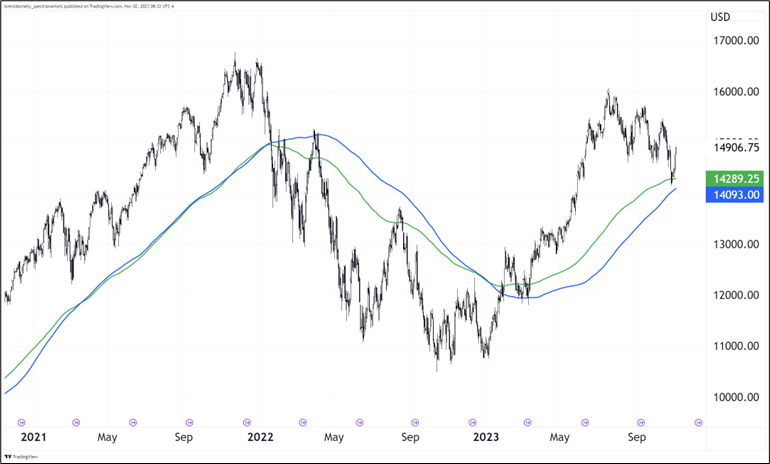
The NASDAQ holds the MAs after an eye-watering selloff. Bullish.
Have a serendipitous day.
The line of latitude 29.9792458 N passes through the Great Pyramid of Giza.
The speed of light is 299,792,458 meters per second.
Probably nothing.
Here is an excellent discussion of pseudoscience and why this coincidence is still pretty coincidental even when analyzed by a statistician who understands degrees of freedom.
https://slatestarcodex.com/2016/11/05/the-pyramid-and-the-garden/
And here’s a totally unhinged “academic” paper


This piece is mostly for people who are interested in backtesting

