The EURJPY short call through ECB was good, but the tactics left much to be desired.

Raspberries make excellent Lego wigs

The EURJPY short call through ECB was good, but the tactics left much to be desired.
Raspberries make excellent Lego wigs
Cover EURJPY before 10 a.m.
and get flat into next week
September 15, 2023
EURJPY was on its way to new lows when there was a double shot of policy pushback in the media. First, ECB hawks called their friends at the FT to say the ECB is not definitely done.
“I don’t agree that we are definitely done,” said one of the policymakers. “We would need a very negative surprise [on inflation] to hike again in October, but we might in December.” Another one said a quarter-point rise in December was “still possible — I’m not ruling it out”.
Then, Bloomberg reported that last Friday’s Ueda’s remarks were overinterpreted.
Bank of Japan officials see a discrepancy between what Governor Kazuo Ueda said in a recent interview and how traders interpreted the remarks, according to people familiar with the matter. Most of what Ueda said in the Yomiuri newspaper interview published was consistent with his routine remarks of late. Taken in total, his comments indicate little change in the view among officials that they’ll need to weigh both upside and downside risks in deciding whether to adjust policies.
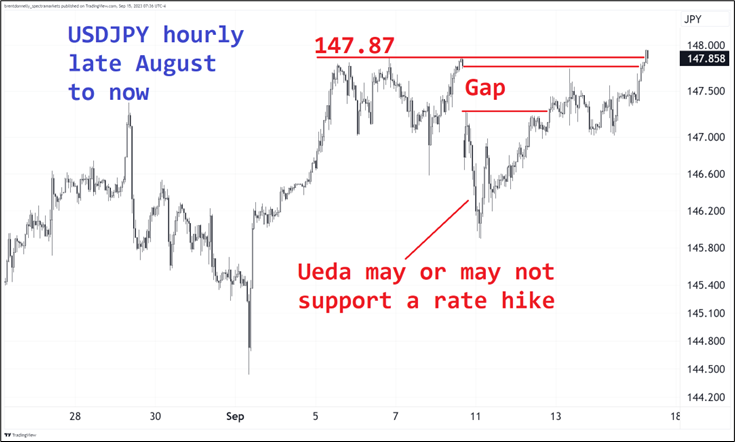
USDJPY has now filled the weekend gap and managed to push 10 pips through the former triple top at 147.87.
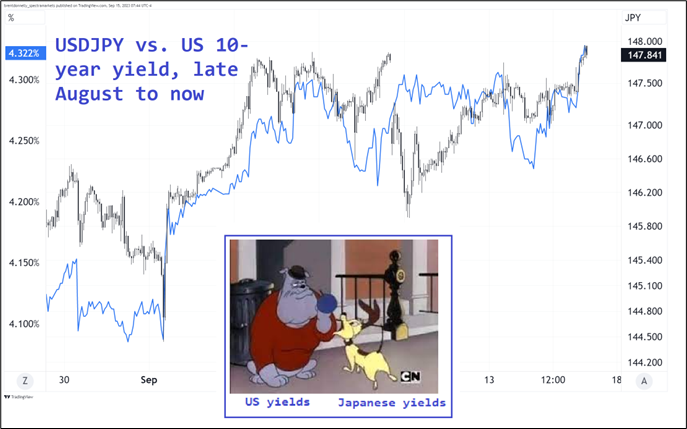
All the noise this week further supports the notion that USDJPY is driven by US 10-year yields. US bonds are the big dog, and Japan yields are a noisy, yappy dog.
I’m hugely disappointed with the rebound in EURJPY, and I will look to square up by 10 a.m today and move on. The FT article has a ton of ifs, ands, and buts… But still. With FOMC, Norges, BoE, SNB, and BOJ next week I would rather take profit here and move on to new ideas.
US 10-year yields are looking feisty up at the top of the range. While we are now entering a bearish seasonal period for US stocks, and EURJPY has a positive correlation to equities, the most likely reason stocks would get hit over the next few weeks would be a clean breakout in yields on a bunch of hawkish or H4L central bank outcomes.
By the way, I am ashamed to admit that there was an epic cheer hedge on this EURJPY trade. If you are not familiar with the Cheer Hedge, read this first.
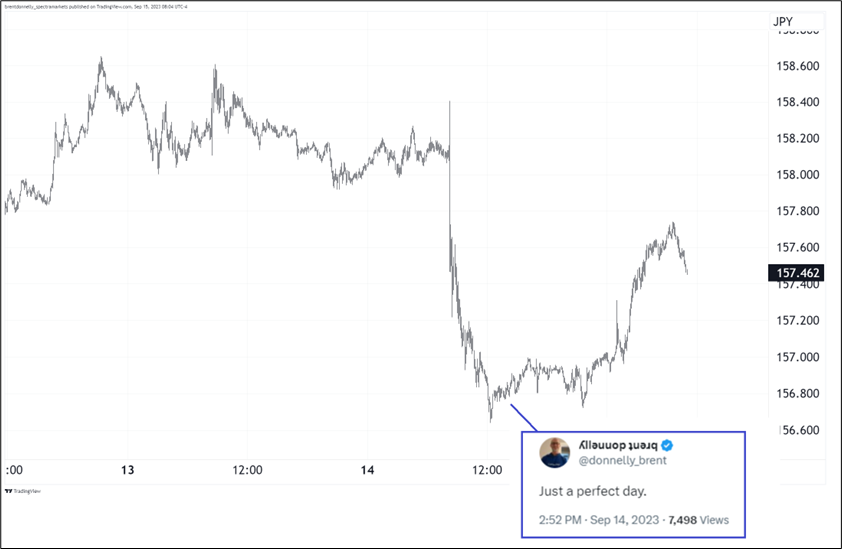
I mean… I was tweeting about the weather, really, but when you have Lou Reed’s Perfect Day in your head after what looks like a really solid market call. Achtung.
Yesterday’s ECB meeting saw a rare reaction where the second Euribor contracts sold off 3 ticks while the sixth contract rallied 9. Euribor contracts tend to move together, up and down, but when there is a specific change of view around the curve, things can get zippy.
ER2 (the second contract) is ERZ3, which is December 2023. ER6 (the sixth contract) is ERZ4, which is December 2024. The fall in ER2 and the rally in ER6 tells you that the market wasn’t sure about a hike this year, and got one… But the hike itself triggered a rising probability of cuts by the end of 2024. This is price action associated with a policy error. The market thinks the ECB has gone too far with hikes and will therefore now need to cut more in 2024.
The market is not always right. It was correct when it took a similar view after ECB hikes in 2008 and 2011 but it was wrong when it tried to call BS on the ECB in 2022.
This chart shows all the times ER2 sold off 3 or more ticks on the same day as ER6 rallied more than 8 ticks.
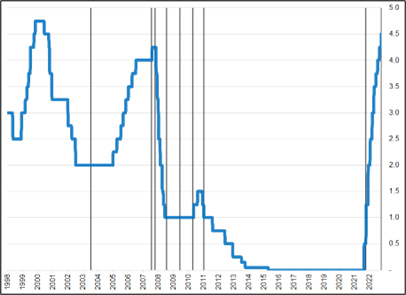
I don’t know what that one episode was in 2003, but you can see that starting in July 2008, when the ECB was hiking due to all-time highs in oil, the hike was ill-advised. It was one of the great policy errors in the modern era of central banking. The market called bologna in the mini hiking cycle during the Eurozone crisis in 2010-2011, too. The market was right, and the ECB was wrong again.
In September 2022, with the energy crisis about to explode and Liz Truss saying “lettuce cut taxes and spend more,” the market called BS on the ECB but the ECB was right. The energy crisis was a red herring, European winter was warmer than a Cinnabon, and the ECB hiked a jillion more times. Here’s the same chart, but with ER6 instead of the ECB policy rate.
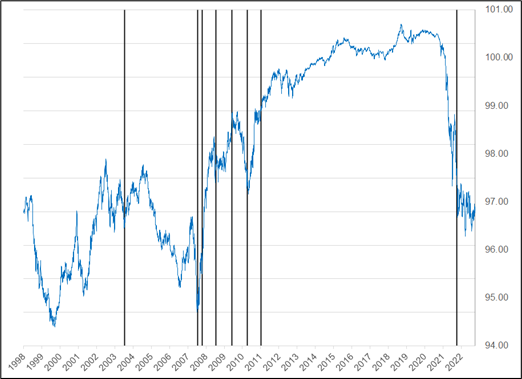
The ECB is hiking into a German recession, and this looks like a classic late-cycle insurance hike that is likely to be unwound pretty quick if EU economic momentum does not turn 180 degrees back upward in Q1. Then again, you could have said the same thing in September 2022.
Spectra Markets is now three! We have hired Mollie Martin to run marketing and take the brand to a higher level. Welcome, Mollie! She will spearhead a modernization of the brand and will help launch a new flagship educational product, Spectra School, in Q1 2024.
Let’s go! Spectra School is going to be the best thing we’ve done.
Finally, 15 years ago today, Lehman Brothers went under. RIP LEH.
“The tasteful thickness of it…”
It’s a huge week next week. Get some sleep!
Have a well put together day.

This piece is mostly for people who are interested in backtesting