A sort of almost unbelievably large move in Brazil. Plus: Short CADJPY.


Subscriber-only
Stocks and AUDNZD
NZD has a bunch of bullish kickers: Election, seasonality, and inflation

A sort of almost unbelievably large move in Brazil. Plus: Short CADJPY.
Short CADJPY @ 112.17
stop at 113.61. Target 110.41
18DEC 1.22 AUDNZD PUT
Cost ~0.56% AUD off 40 spot
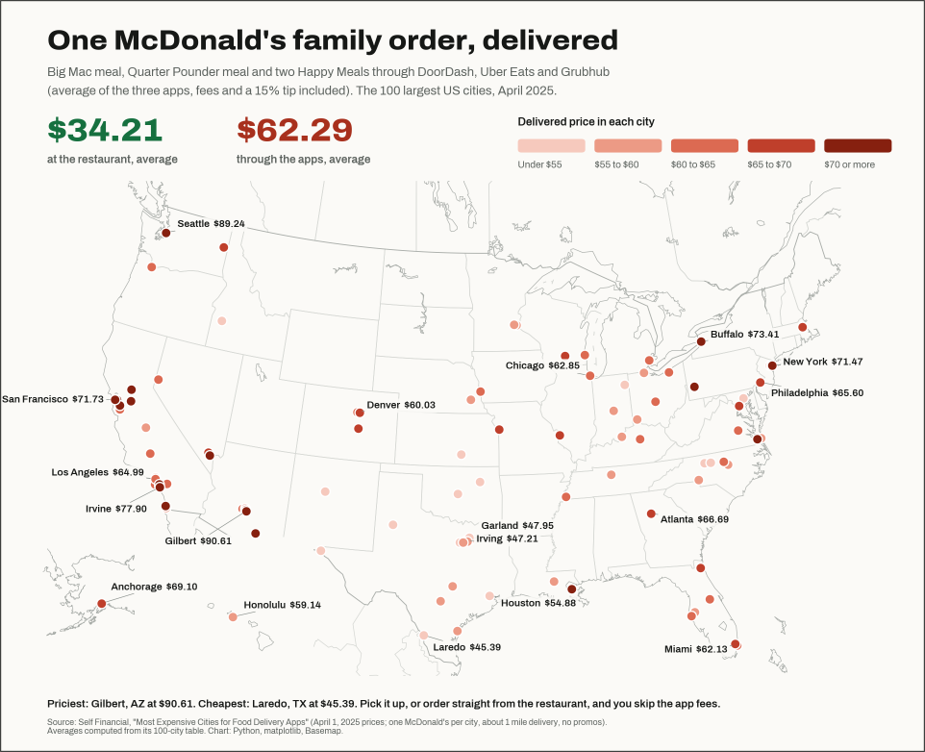
Ordering food on an app costs 60% to 90% more than it costs in the restaurant.
When you add up higher menu prices, service fees, delivery fees, other fees, and a 15% tip, it costs about 65% to 75% more to order McDonald’s on an app, for example.
See larger map at bottom of am/FX.
The result in Brazil was a shocker. While it’s easy for strategists to roll out the “buy the dip” messages, it’s hard for real humans to risk manage a situation like this because the FX options market is hit by a neutron bomb and some equity options presumably torched as well. In the long run, BRL has been fine under all types of government and has outperformed under Lula. This is not because he is an economic miracle worker, it’s because external factors like China’s accession to the WTO have dominated idiosyncratic policy and politics in Brazil. Here’s total return of BRL (spot + carry) under various regimes.
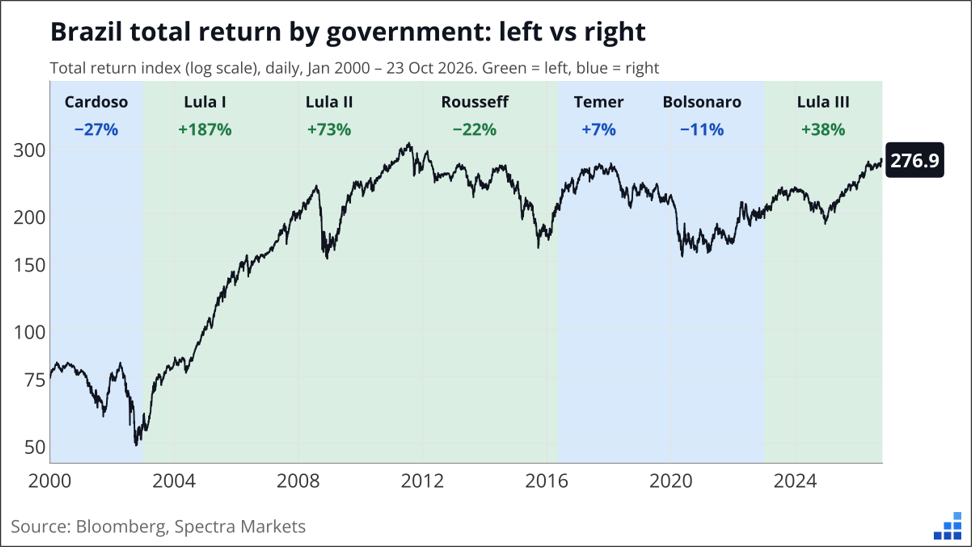
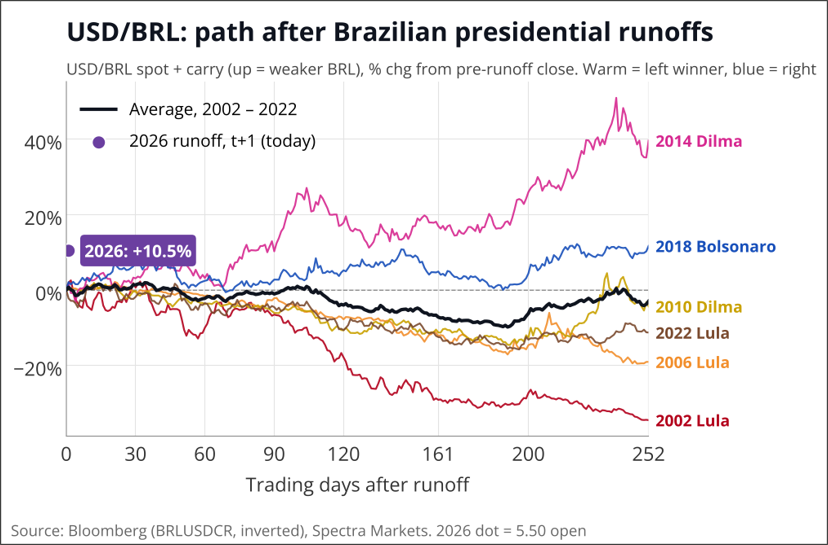
Saying Lula is bad for BRL is kind of like saying Republicans support smaller government. It sounds true but historically has not been true. Let’s see. For a bit more context, here is BRL including carry after the runoffs since Y2K.
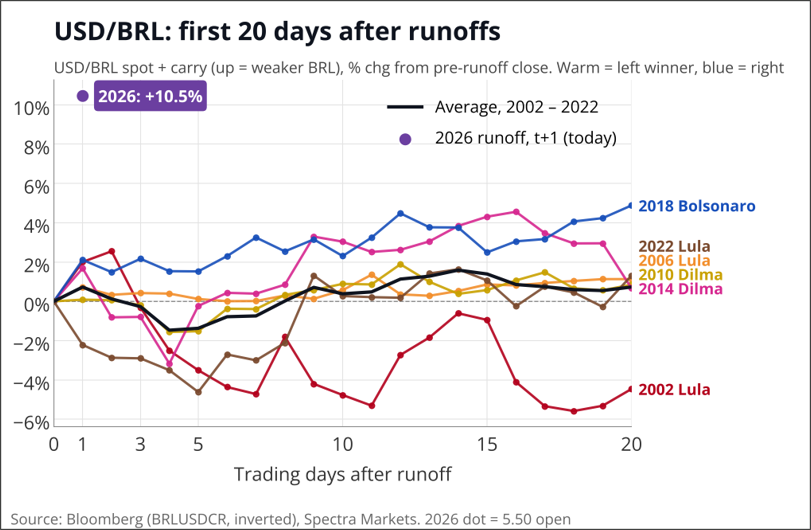
Zooming in, you can see the price action after the runoffs in prior years has been incredibly choppy.
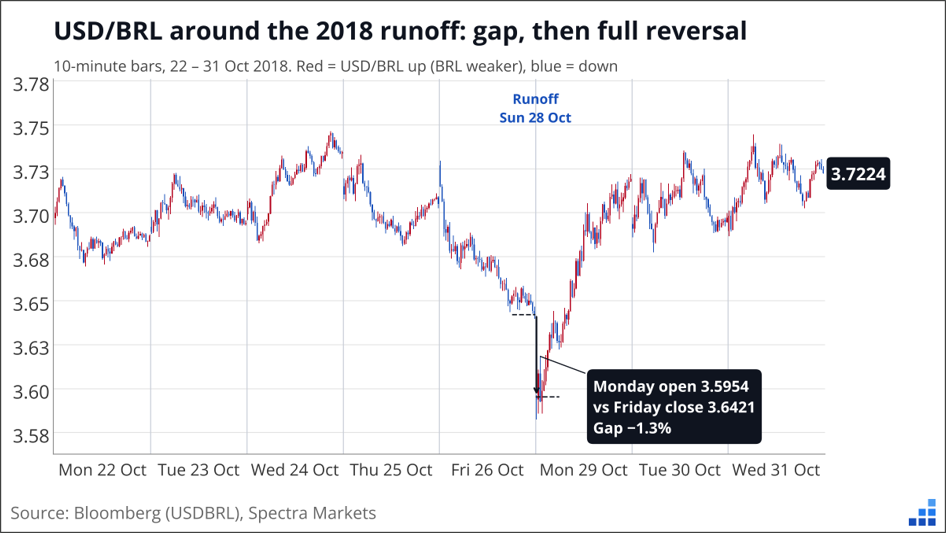
I double checked the data there on Bolsonaro because I didn’t remember—it is correct that USDBRL went up the Monday after he won.
No call to action here on Brazil. I suppose if you are a long-only investor who went in flat, there is a huge margin of safety here now to get long Brazilian assets on a one- or two-year time horizon. Short-term macro wise, I don’t see anything to do here.
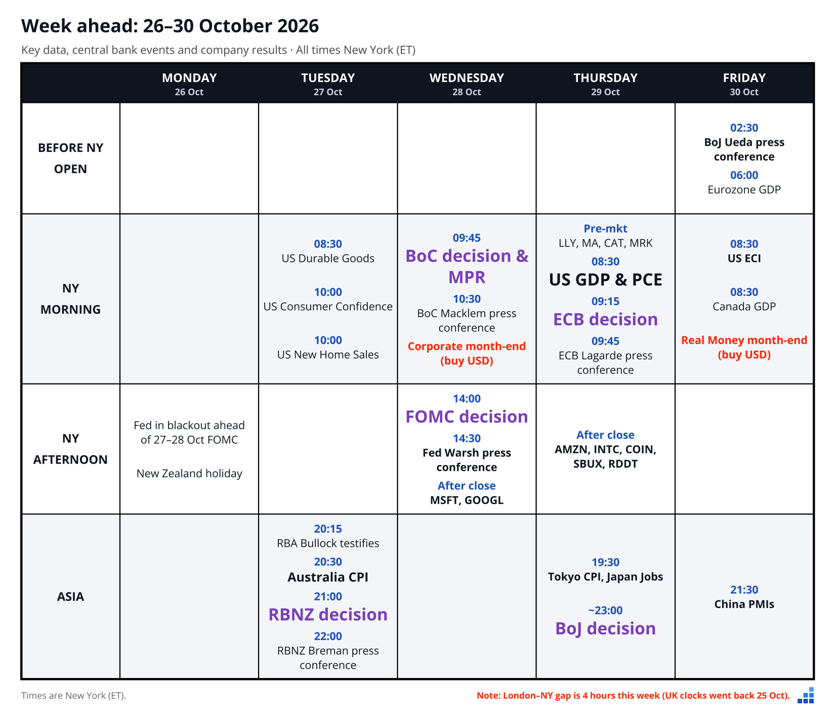
It’s a huge week for central banks and I feel like there is potential for a surprise from either the Bank of Canada (dovish), the Bank of Japan (hawkish) or both. While it would be mind-blowing if the BoJ hiked, I do think that the high inflation situation there could allow them to deliver a hawkish hold that takes December from 75% to 100%. The Bank of Canada is staring at below-target core and above target headline inflation, so they could easily signal a hike is coming, but not yet. That would be a bullish outcome for USDCAD.
The CADJPY chart offers a good entry point for shorts, and I am going to add short CADJPY here (112.17) with a stop at 113.61. It’s a simple trade with simple logic:
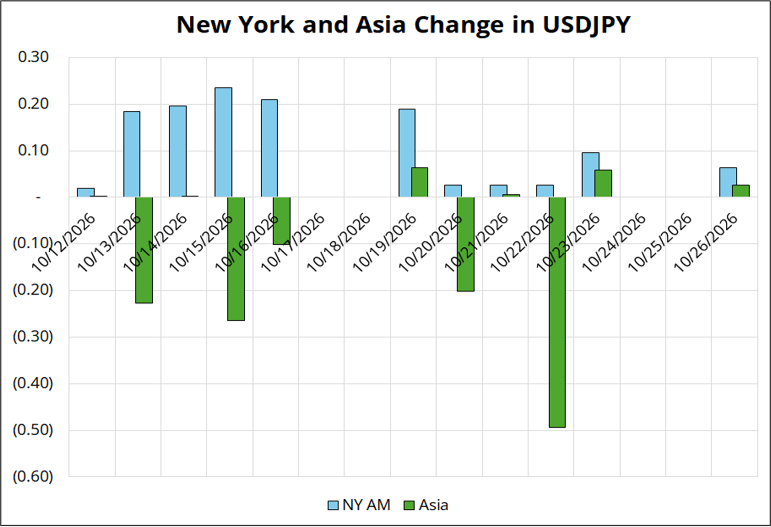
I prefer spot here but it is worth considering options because 06NOV26 we get the GPIF quarterly investment results. Therein, we will find out if they have been tweaking the domestic bond allocation within the existing limits. If they have, that will inflame anticipation over a possible rebalancing announcement in the future. If they have not, it will be yen-negative because it will show that the thesis around GPIF moving some money home is off the mark for now.
Here are the two ways to trade this. I like the spot idea best because there are many paths where both BoC and BoJ are boring nothingburgers. If you want more leverage on a large move, the options trade is better.
One heck of a calendar this week. Five central banks plus advance GDP, and month-end. I mistakenly said last week that there should be large USD buying by real money. I thought stocks were down a lot this month, because that’s what it feels like! But in reality, U.S. markets are close to unchanged in October. SPX flat, NASDAQ down 3%, overall market cap down less than 1%. So, Friday should be random month-end flows, not highly directional.
Have a superb week.
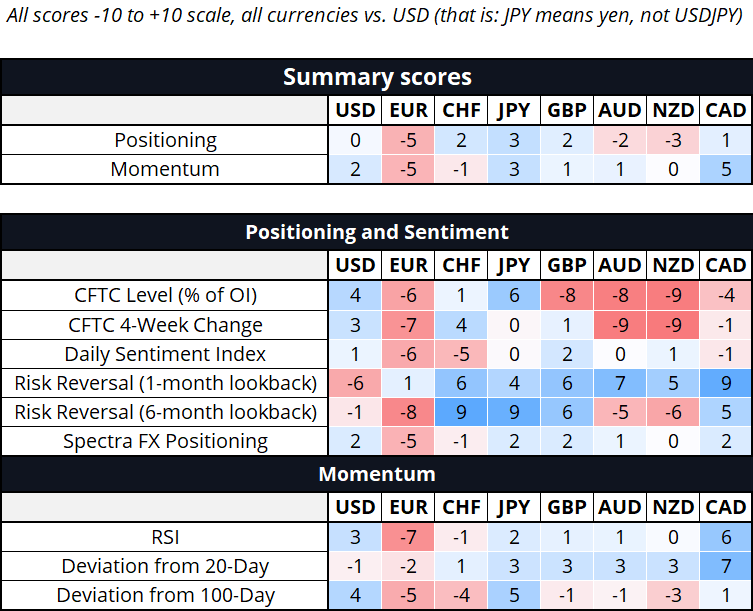
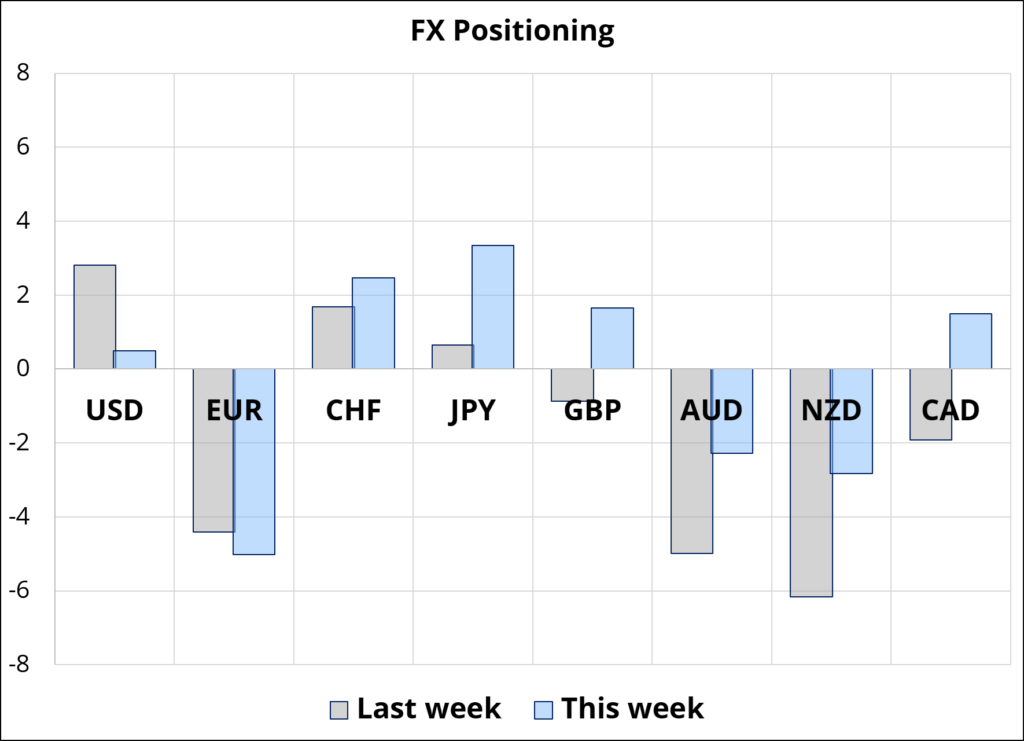
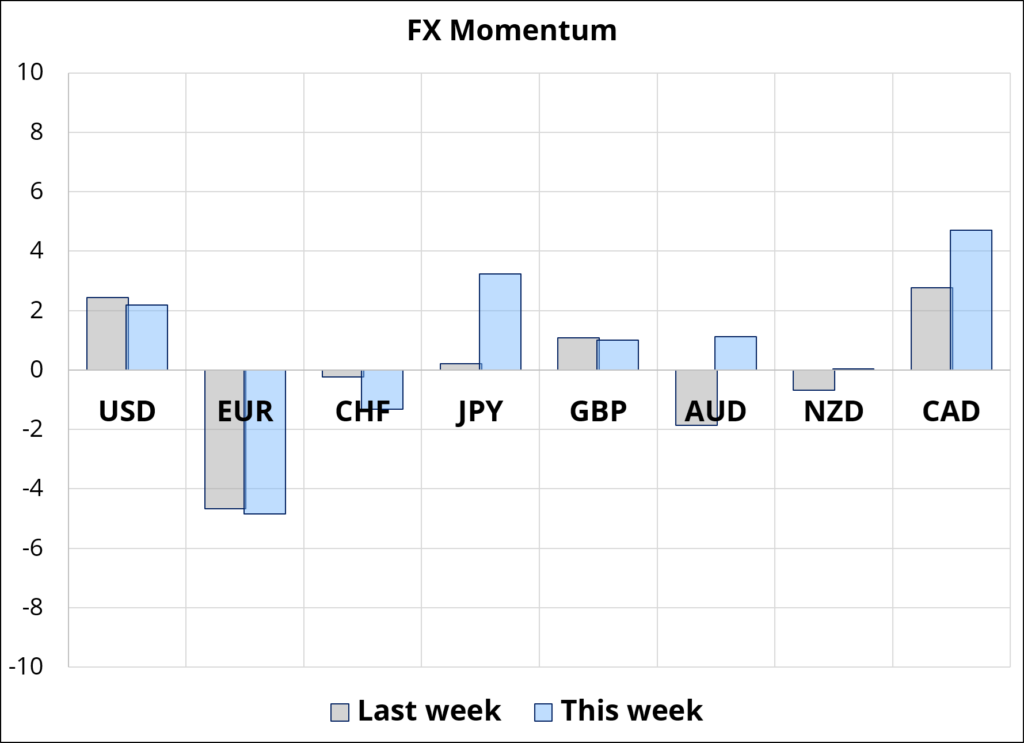
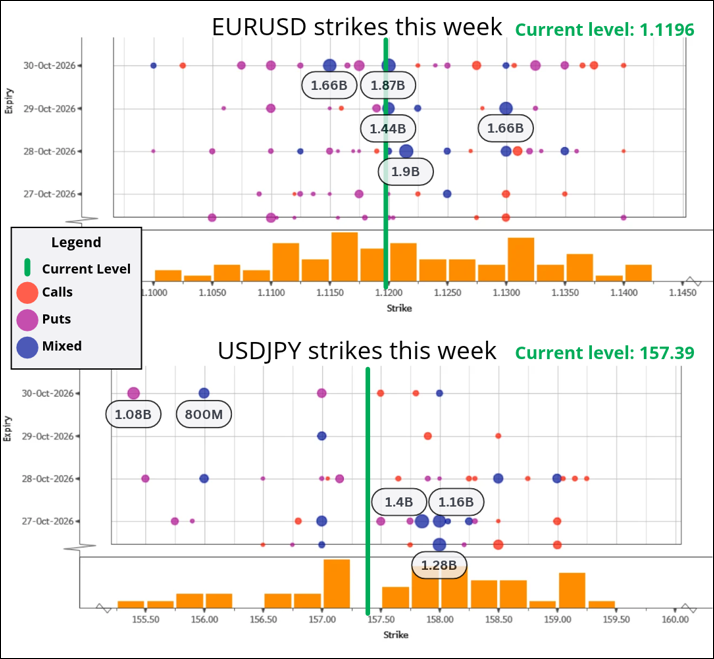
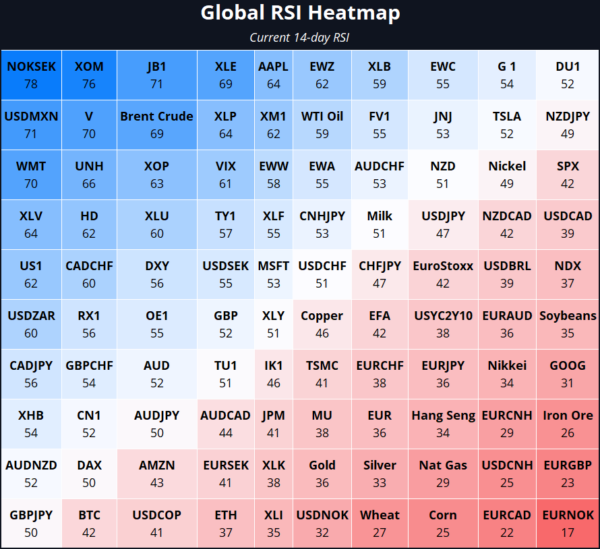
Hi. Welcome to this week’s report. (To read about how I use and trade this report, see here.) Positioning is getting pretty close to home, which is a win for USD bulls as we have gone from big long USD to not so much and yet EURUSD is still below 1.1200. That said, EUR shorts are extreme, and EURNOK’s RSI is 17, so there is still some reason to believe that euro shorts are at risk of the news flow changes. Moody’s nondecision didn’t help euro much, though. The real story in euro, perhaps, is the billions of gamma right around here. That was the story last week too, and EURUSD was trapped. Maybe another frustrating week for both bulls and bears as we need something big to get away from the 1.12 anchor.
When you add up higher menu prices, service fees, delivery fees, other fees, and a 15% tip, it costs about 65% to 75% more to order McDonald’s on an app vs. in person.
https://www.self.inc/info/most-expensive-cities-for-food-delivery-apps/
Another study shows that delivery apps cost 70% to 80% more than pickup.
NZD has a bunch of bullish kickers: Election, seasonality, and inflation