Diffs
Things are breaking a little tiny bit in FX with the USD surging despite lower US yields and higher gold as global yields are moving more than the US and cuts get priced for the ECB and BOC. Here is EURUSD vs. rate differentials:
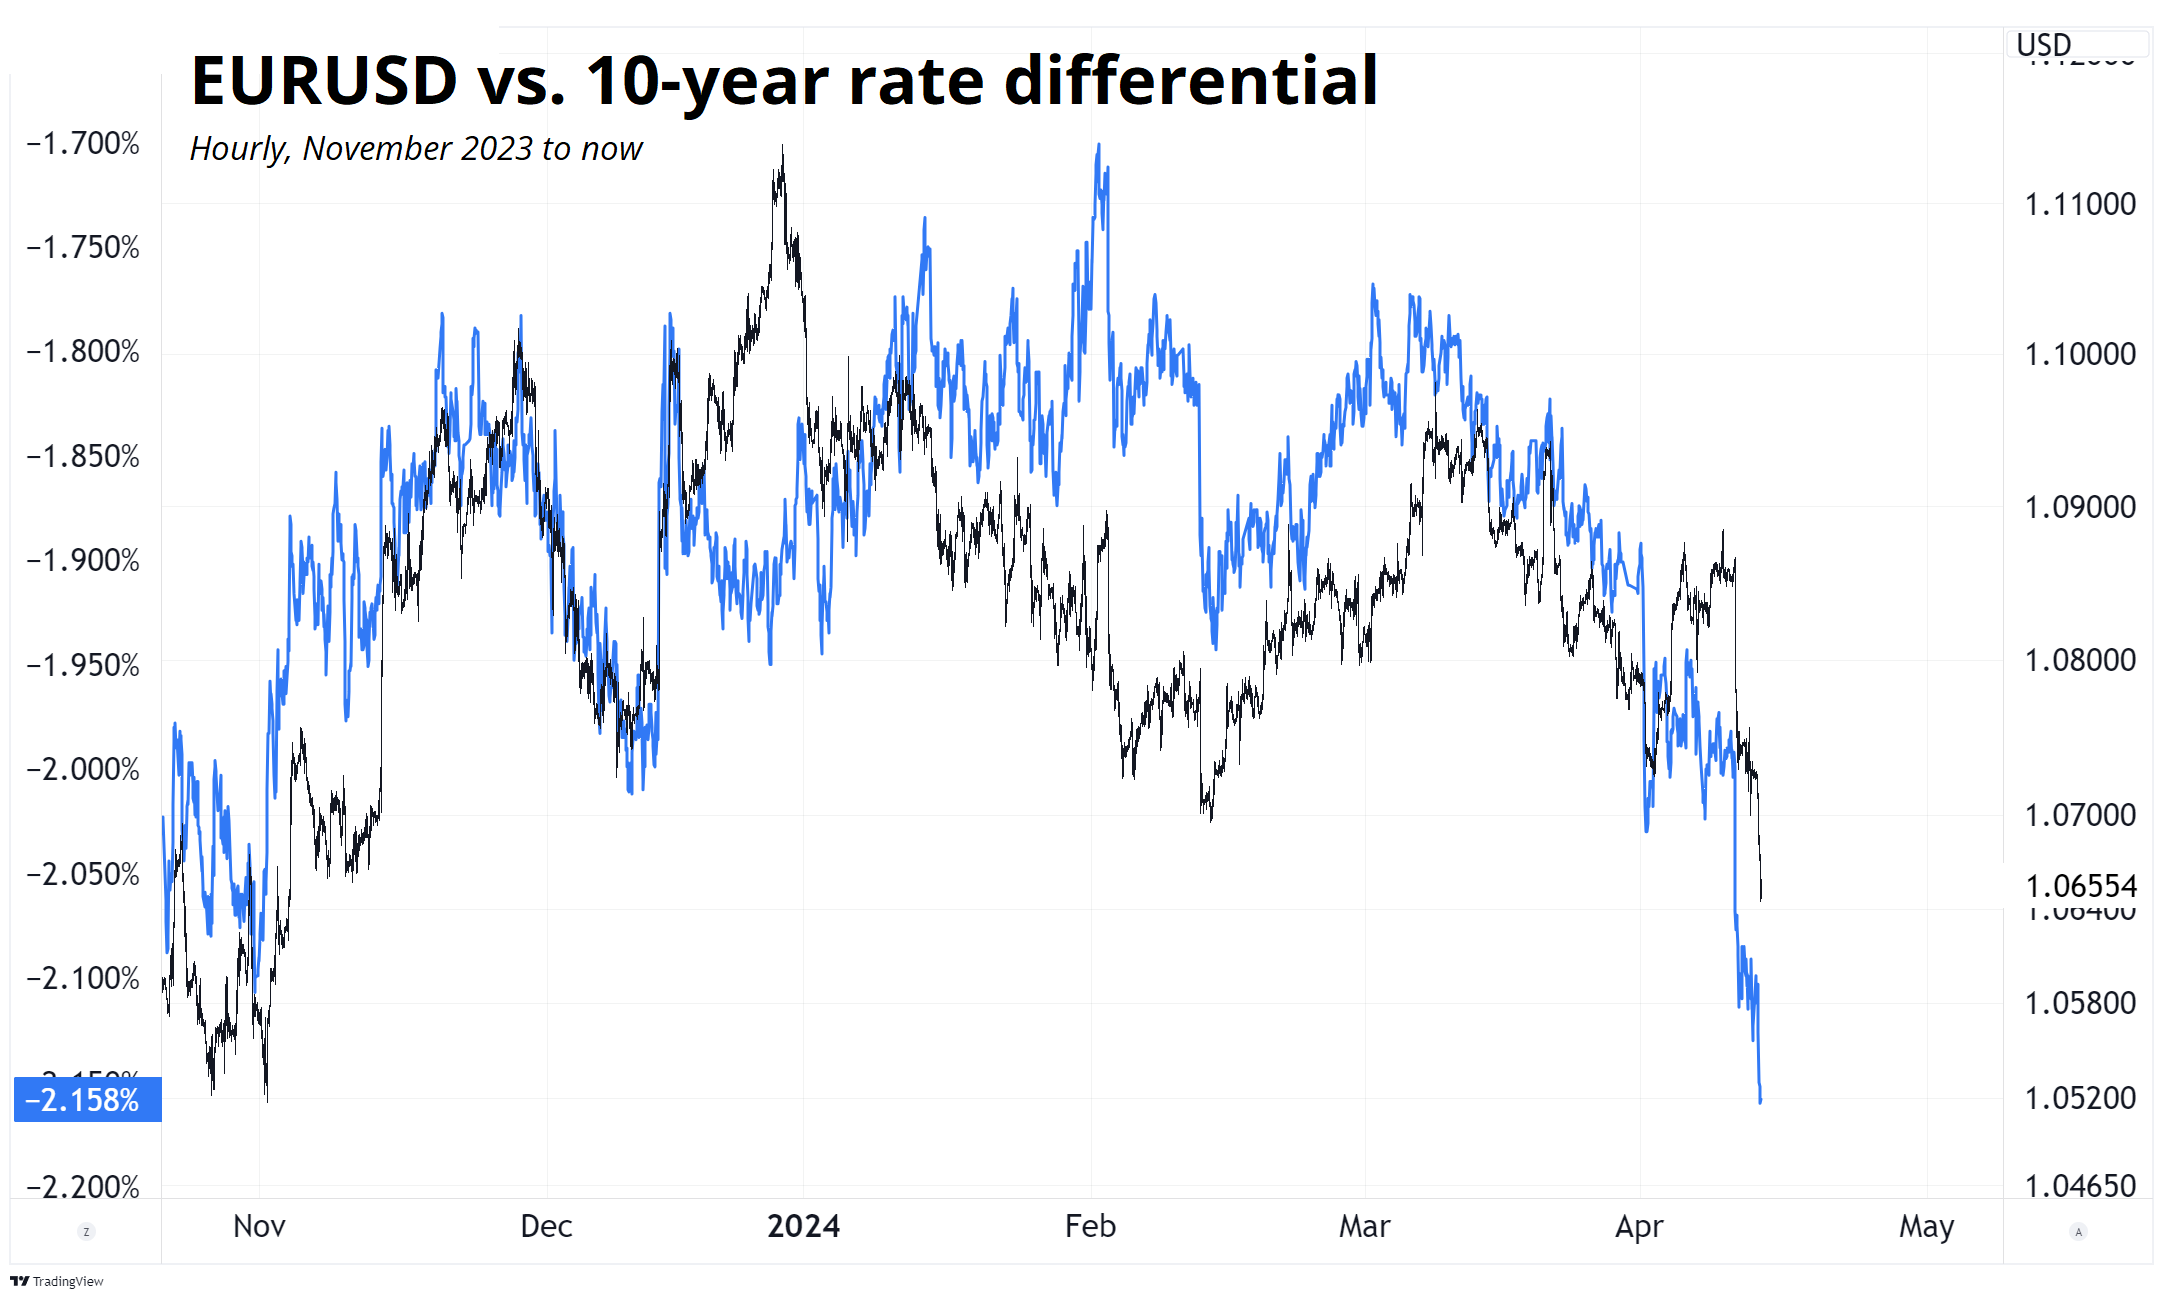
The differential is back down to levels last seen during the EU energy crisis when we were staring at TZT futures all day.
The strength in commodities really stands out in a risk averse and USD up environment, but perhaps this is consistent with a reflationary scare in a world where there is no tightening pushback possible from central banks. By telling the market they won’t hike, the Fed is igniting animal spirits and/or fear of inflation. In case you missed it, that was the topic of am/FX yesterday.
Alfonso Peccatiello and I discuss this setup in more depth in this week’s podcast and the conclusion is that until there is a legitimate possibility of a Fed rate hike, commodities will probably continue to act as a policy error release valve.
Meanwhile, in the crosses, lower global yields have slammed EURJPY and EURCHF and again, and this probably makes sense. The key level to watch in EURCHF is still 0.9685 as I have highlighted a bunch of times recently.
Speaking of key levels:
The 1.25 level in cable finally broke.
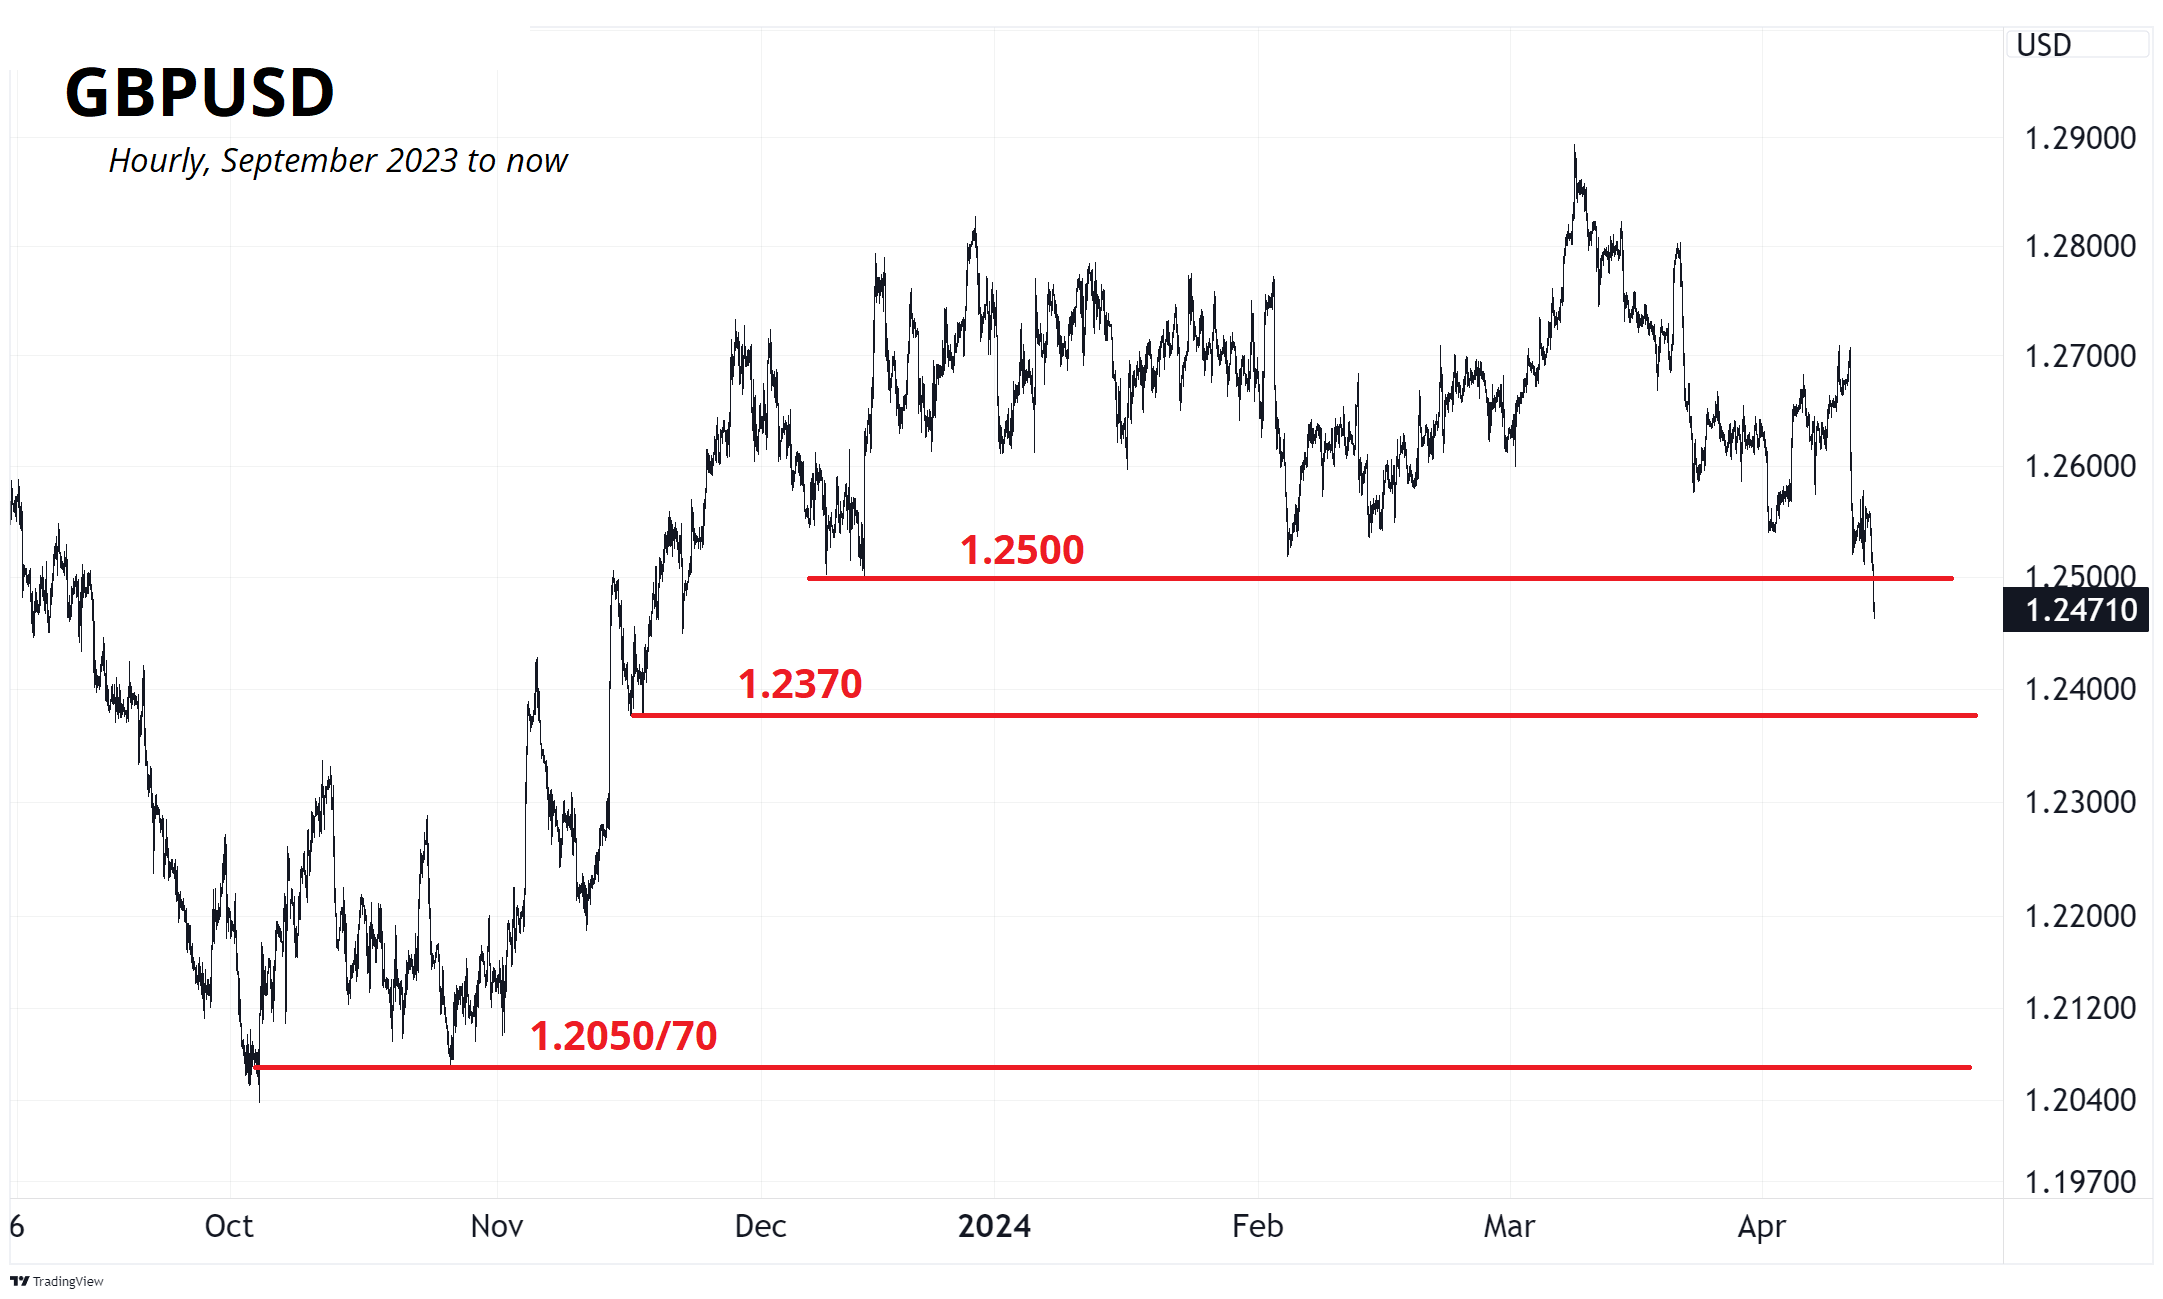
You can see the next major support is 1.2370 but with GBPUSD somewhat oversold on a micro basis, the first thing to watch is whether we can close below 1.2500. With CTAs inexplicably long (in size), there should be persistent selling from them today as we print a new multi-month low. So if we don’t close below 1.2500, it’s concerning for GBP bears. If we are tracing out a symmetrical move to the rally in November and December, that would target 1.2050/70 in the next month or so.
Cocoa!
Nick sent me a performance report from a hedge fund in Australia. They were up 14% last month, primarily on a long cocoa position, and I loved their commentary and how they think about risk and explain it to their investors.
The heightened volatility recorded in cocoa this month has increased the softs position in our sector allocation table, pushing softs to the top of our risk allocation. Even though the fund is now highly exposed to the cocoa price, this remains a core philosophy of our fund. To achieve our mandate, one of our goals is to hunt for outliers and once we identify them, initiate a systematic process to execute the trade and let the trend run for as long as possible. The obvious consequence of such a philosophy is a potential reversal of this trend exposing the fund to a drawdown from a high. As our investors know, we must embrace this volatility and trust the systematic process of the fund to unwind this position when appropriate. We are as excited as you are to see how this trade continues to develop.
In a nutshell: We caught a juicy move and we’re going to ride it. If it turns, it’s going to hurt, but that’s why it’s called “risk”. Love it.
Calendar
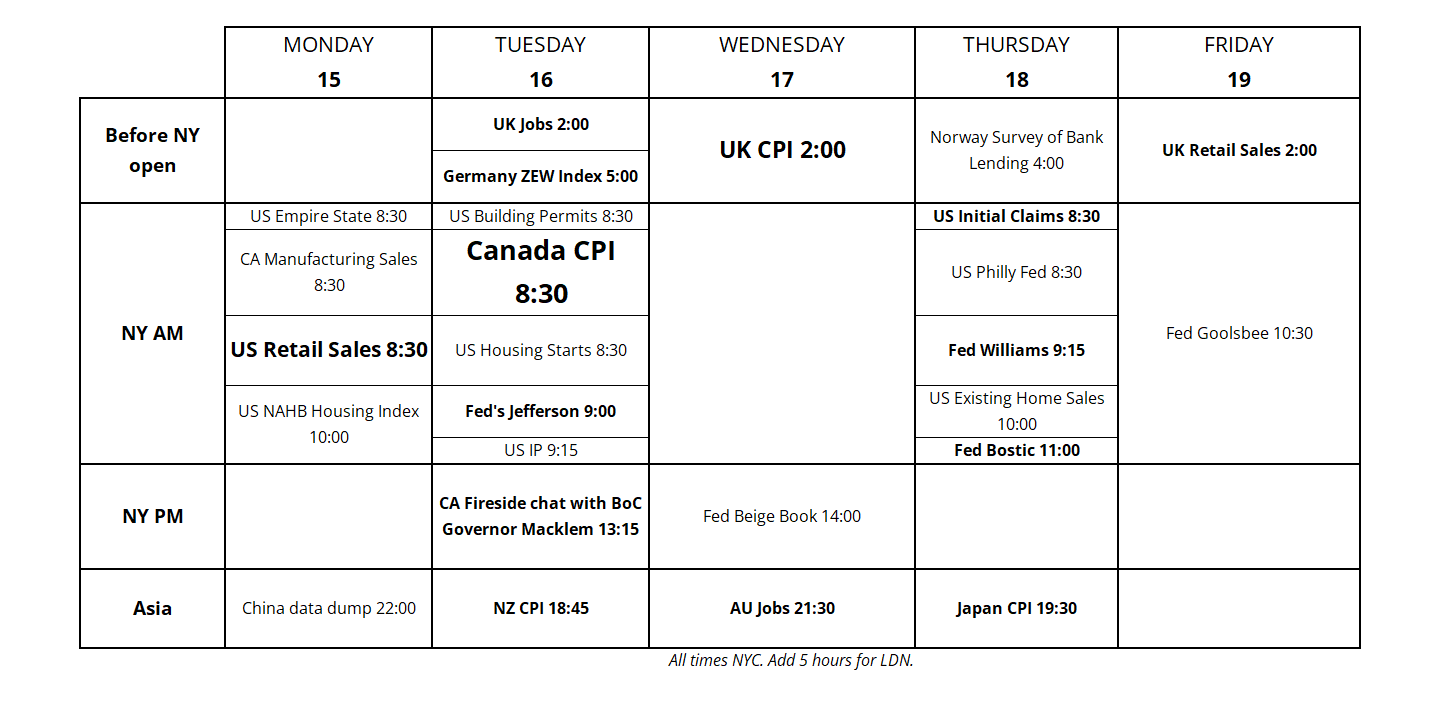
Here is next week’s calendar so you can prep. With the Bank of Canada priced at 50/50 for a cut in June, Tuesday’s CPI figure takes on much more importance than usual. Also note the flurry of UK data that could potentially set the cat amongst the pigeons post 1.25 break.
Final Thoughts
People are nervous about Iran headlines this weekend. That seems to be a weekly thing of late. This just came out:
*ISRAEL BRACING FOR POTENTIAL DIRECT ATTACK FROM IRAN IN DAYS
Hope your weekend is straight up fire.