
Talking about the USD and China and GBP and horsewomen.
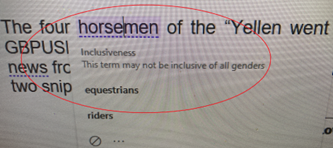
I had a little run-in with the Microsoft Word AI compliance department while writing am/FX yesterday

Talking about the USD and China and GBP and horsewomen.
I had a little run-in with the Microsoft Word AI compliance department while writing am/FX yesterday
Short GBPUSD at 1.3080
Stop loss 1.3026 (was 1.3226)
Take profit 1.2757
Long USDCAD @ 1.3230
Stop loss 1.3088
July 20, 2023
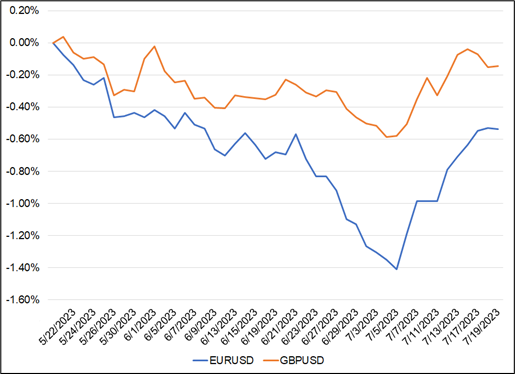
The China stimulus, China stabilization Groundhog Day movie continues as every day we walk in and they either did some random tweak to policy again or the market is getting geared up for the BIG ONE™. Much as was the case in mid-June, there is again excitement about the BIG ONE™ out of China as we near the Politburo meeting at the end of this month. Here’s how the June runup traded:
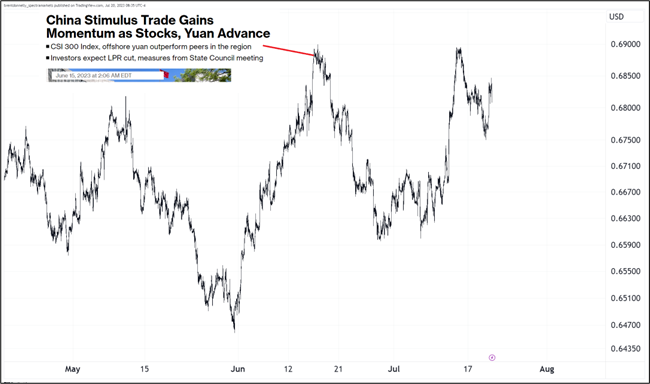
Now, China bulls are praying for stimulus at the ~July 28 Politburo meeting. I remain skeptical. Every week we come in and there is something. LPR cut, property measures, local loan measures, reversal of antagonistic policy towards big tech, currency market fiddling, and so on. Maybe they are just pushing on a string? That’s what it feels like to me, though obviously I’ll keep an open mind because in a command economy where outcomes are suboptimal, the game changing policy move is always one day away.
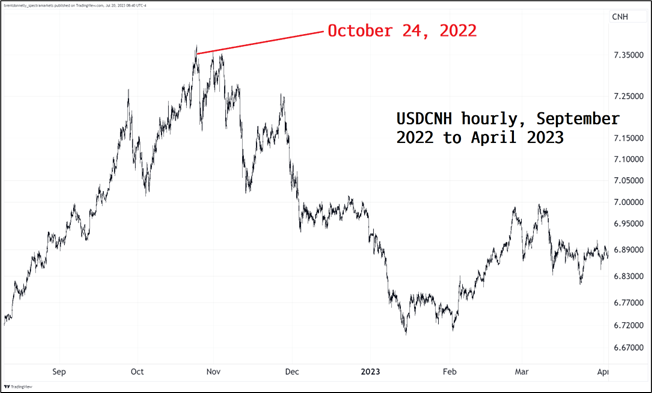
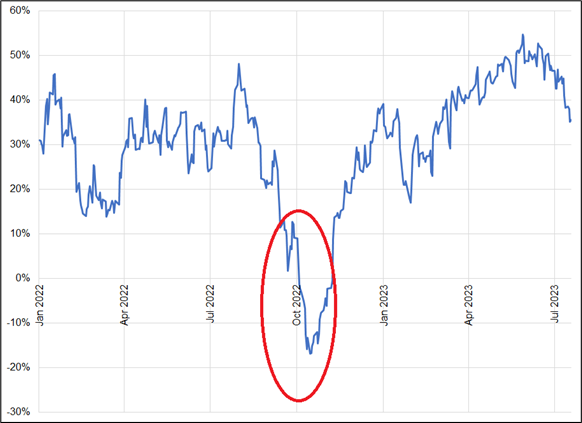
The last time the PBoC fixed low in USDCNH and tweaked the cross-border ratio rule was October 2022. They were effective in putting a top in USDCNH, but it wasn’t instant gratification. Here is the chart:
You know what else happened in October 2022? EURUSD massively decoupled from interest rate differentials. Here is the evidence:
That correlation is again rolling over fast and because of the mathematics of how 50-day rolling series work, it will keep going down fast if the current weirdness of FX vs. rates continues.
Here is my theory. Imagine the PBoC is concerned about USD strength, particularly vs. CNH. With the pair tightly tied to the direction of the broad USD, and large FX reserves sitting there locked and loaded… They switch from US Treasuries to bunds, buy EURUSD and… Repeat. That puts downward pressure on USDCNH over time and then when USDCNH starts blipping higher despite their efforts in G10 FX, they give it the smackdown. I believe this is what is happening, though my evidence is circumstantial. As you can see in the first chart on the prior page, the PBoC won, eventually, though there was a blistering retest of the highs in USDCNH and they had to bring out the big guns to win the war.
If the analog played out perfectly, it would be extremely bearish USD and that was my lizard brain, first derivative reaction. But, upon further thought, I don’t think this is the same setup.
When central banks intervene in currency markets, they are buying time, not ensuring a guaranteed reversal. They can hold the dam for a while, but eventually it will burst if the macroeconomic and flow factors don’t turn. The PBoC are huge, but they are not unstoppable. In 2022, they got tailwinds from year-end USD weakness, a recurring seasonal.
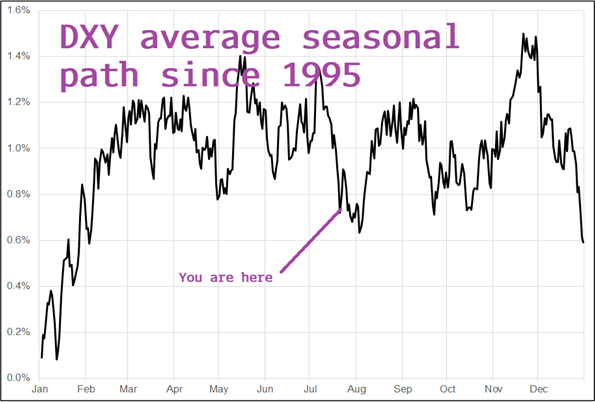
This time, they will fight seasonal USD strength that begins in a week. Most notably, August 3 to September 8 is the worst period of the year for GBPUSD and similar windows are super weak in other currencies, too. In contrast to late October 2022, this time the PBoC faces much stronger headwinds in their effort to manage the basket and USDCNH.
This is all encouraging for my GBPUSD short, as is the price action overnight after the PBoC made their move and GBP went up 60 then down 100. Also, GBP rallied right up to the single print zone that I identified yesterday and failed. The single prints are 1.2980/00 and the high was 1.2965. Bearish. Similarly, there was good news / bad price action in NZD, too. That makes two days in a row of good news / bad price for the bird. Yesterday it couldn’t rally on strong CPI and today it can’t rally on the nth string push announcement from China. Bearish.
Putting it all together, China has been aggressively switching out of USD and the rule change and super low CNY fix last night were another salvo in their effort to keep USDCNH from ripping back to 7.40. The game is in the early innings and this will be a months-long fight unless the US economic data rolls over. Today’s 228,000 Initial Claims release is not the kind of data point Team Xi is cheering for.
Finally, one last piece of evidence. When trying to assess what the central banks are doing in G10 FX, you can watch the 11 a.m. WMR fix because most large flows from central banks are either benchmarked to that, or peter out at that time as liquidity fizzles post-fix. Here is EURUSD from 10:30 a.m. to 11:00 a.m. each day (the 30 minute window into the fixing). You can see that EURUSD has been bought aggressively since July 6 and the last two days are not showing any evidence of aggressive USD selling.
CHF can trend for no reason for prolonged periods, so randomly fading moves that “make no sense” is usually a recipe for sadness. That said, short CHF is on my radar for a few reasons:
If you look at trades like 6-month CHFBRL or CHFMXN, the carry is bazonkers and you have a potential downside release valve for the CHF if the SNB starts making dovish noises either on the wires or at their next meeting in September. But like I said at the start of this section, I can’t find a good reason to just plug my nose and go short yet.
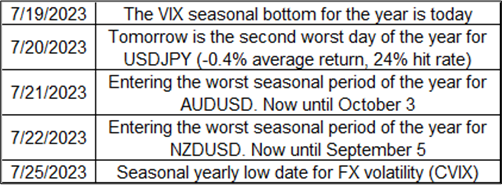
If you bought the Spectra Markets Trader Handbook and Almanac, I hope you have noticed that the seasonality signals have been absolutely excellent so far. 55 winners and 35 losers with a significant positive return. The next 5 signals are below.
Hope your day involves a bit of horsing around.
created in midjourney


This piece is mostly for people who are interested in backtesting

