I was extremely wrong on the BOJ but the question now is to figure out what’s next. It’s definitely not obvious.
Okra

I was extremely wrong on the BOJ but the question now is to figure out what’s next. It’s definitely not obvious.
Okra
Long 08MAR
132.50 USDJPY call
cost ~0.75% off 131.10
February 10, 2023
Quite a strange turn of events with Ueda looking set to take the helm at the BOJ, not Amamiya. Ueda’s name was not on many bingo cards! My BOJ call was totally wrong as I thought it would be safe to assume Amamiya would say “yes.” I am wrong and everyone is confused, chasing theories like cats chasing a laser.
Did Amamiya refuse the job because they wanted him to be hawkish and he said “no”? Or is it nothing to do with policy? But if the powers that be wanted rapid normalization, Amamiya would be the last person to approach. That would be like picking Yellen or Brainard to lead the inflation fight in the USA. None of it makes much sense to me.
Meanwhile, the possibly more important story is the continued rise in global yields and drop in stocks after last week’s ridiculous meme and retail-driven rally post-Powell. Chalk another win for the VIX UP, SPX UP >1% model as the 5-day change in stocks close-to-close from last Thursday is negative 3.2%. Stocks are in trouble still as CPI looms, yields are back on the move, and we are about to enter one of the three worst 2-week seasonal periods of the year.
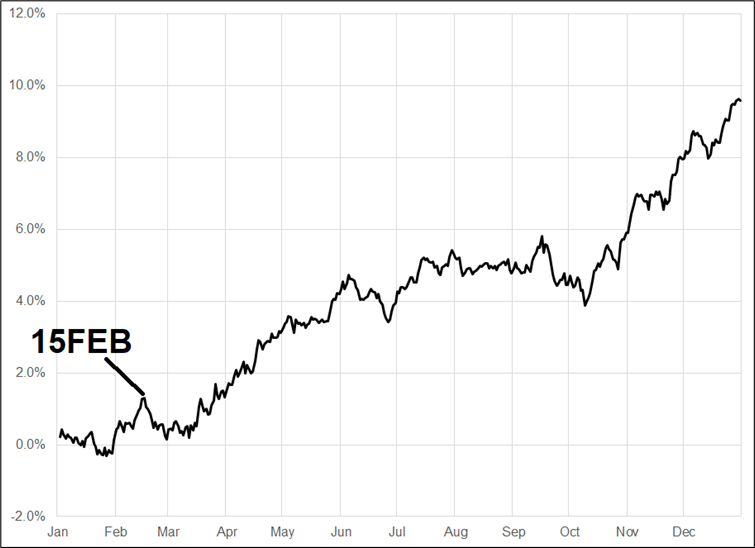
Caveat here is that stocks haven’t rallied into 15FEB this year, so the seasonality has not followed the standard pattern. Still, there is a reason stocks rally early in the year and sell off after. New allocations to 401k’s plus bonus money mean huge inflows in the first six weeks of the year. Those huge inflows are nearly done.
Circling back to the yen, there are crosswinds:
At the risk of suffering from confirmation bias or the endowment effect, I am sticking with the USDJPY topside call. It’s not an easy decision but I think the Japanese catalysts are out of the way for a long time and the real story for now is the rise in global yields. Policy will normalize in Japan at some point in Q3 of 2023, but there is enough uncertainty around the path while yields are unambiguously supportive for USDJPY. If you’re short USDJPY now, you have a long time to wait before your next Japanese catalyst.
One of the ever-present risks for US investors holding any cryptocurrency other than bitcoin is that they are probably invested in unregistered securities. If ETH is the new digital bond, it’s an unregistered bond that’s being advertised by many platforms as a sort of high-interest savings plan for crypto assets. This week’s SEC action against Kraken is another example of how the SEC has decided to use existing laws and rules to regulate crypto and those existing rules almost surely define most yieldy crypto and Web3 projects as securities.
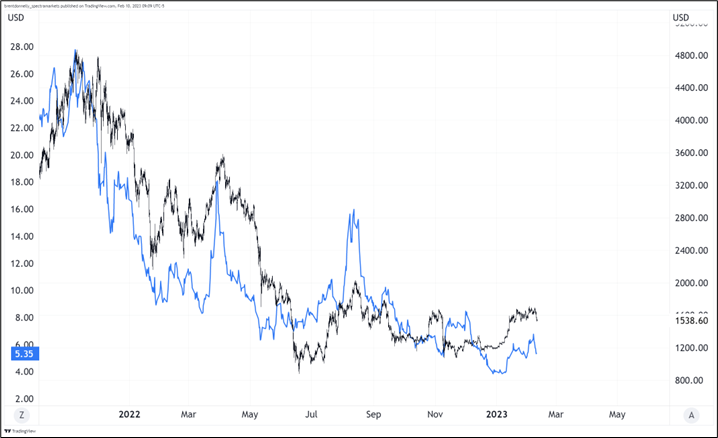
ETH dropped on the news, but it’s hard to separate idiosyncratic crypto news from the broad meme frenzy because crypto tends to move with TSLA, GME, and other meme / retail favorites. There is still a loose vs. tight financial conditions oscillation thing going on in the world. Whether you’re trading silver, palladium (down 5% today), AMC, GME, or ETH, it’s all very much the same trade many days. Same direction but different magnitudes. You can see in the chart below that the directional ebbs and flows of AMC stock and ETH have similar timing (though AMC is on the road to zero due to dilution, and ETH is not).
Canada jobs data today (raging strong) further delays the reckoning for Canadian consumer debt. As long as people have jobs, they will always be able to make the mortgage payment and the credit card minimums.
Have a warm weekend.