Today’s piece goes into why CPI is more important than AHE. Still, chalk up a point for the disinflationista Goldilocks camp after today’s data.
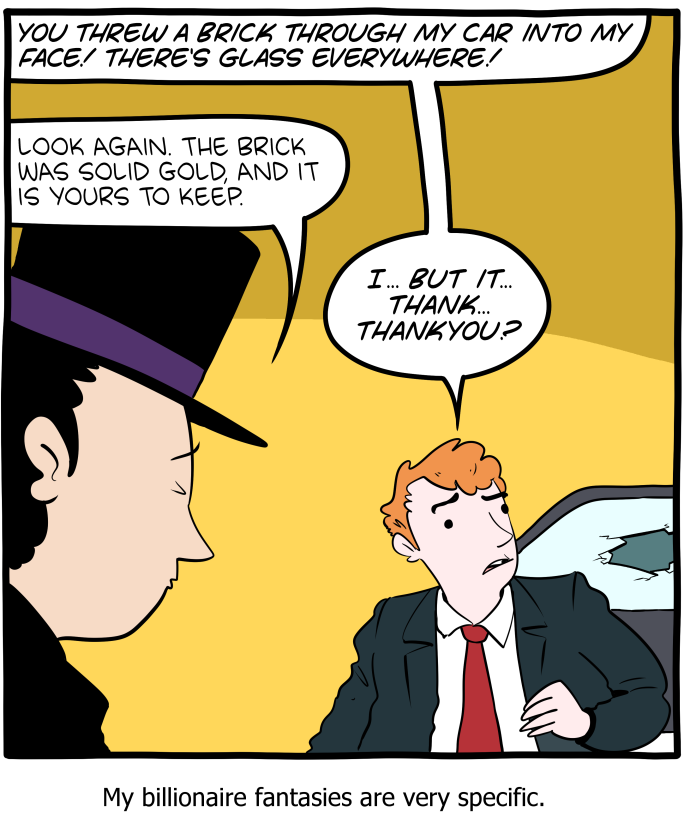
If you are looking for a silly, smart comic strip…
“Saturday Morning Breakfast Cereal” delivers

Today’s piece goes into why CPI is more important than AHE. Still, chalk up a point for the disinflationista Goldilocks camp after today’s data.
If you are looking for a silly, smart comic strip…
“Saturday Morning Breakfast Cereal” delivers
US month-over-month hourly earnings have dropped off a cliff, coming in lower than expected and last month was revised down. This is exactly what Waller and the Fed are hoping for and it runs in stark contrast to the ADP commentary on Wednesday. Look at the far right of the first chart and you can see the tiny print today (0.1% MoM). If you look at 3-month annualized, it has not yet made new cycle lows because the last two months were pretty hot, even after revisions.
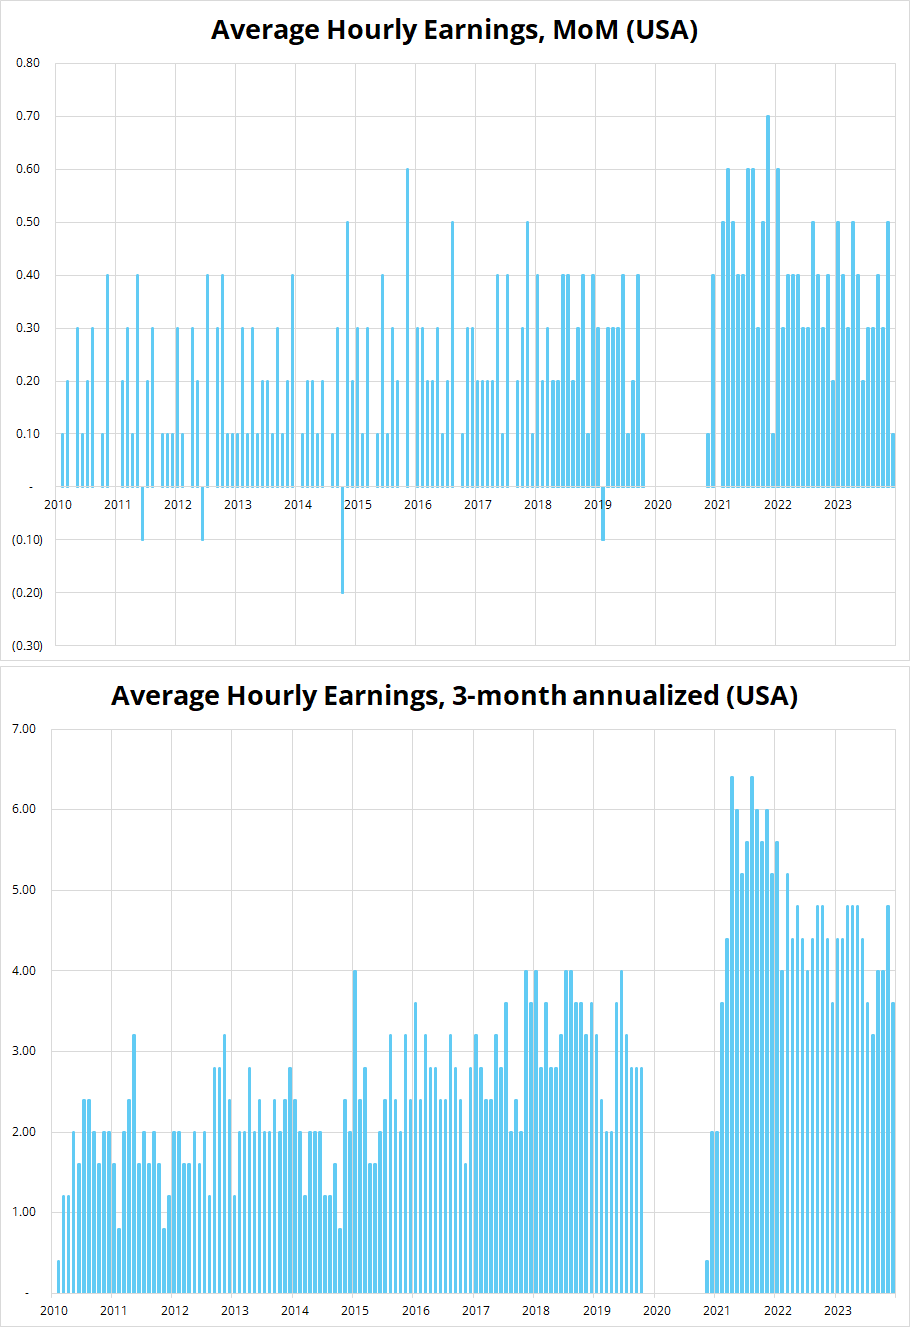
I think that AHE is much more important than the headline figure because Waller has effectively told us that and because the entire macro story right now revolves around inflation and wage growth, not employment.
Still, in the end, it’s the CPI number released next week that will either ratify the USD down trade, or not. If CPI is low, the seasonal quirk story wins and the immaculate disinflation / Goldilocks regime accelerates.
If CPI is unambiguously strong, the market will start to wonder if inflation has bottomed and there’s nefarious inflationary reacceleration going on here.
The market has spent all week selling USD as the “TINA is dead” trade is in vogue. Now, next week’s CPI becomes somewhat of a watershed, imo.
If CPI comes in low, the seasonality theory wins, and we could see a true USD down theme emerge next week with a multi-percent, multi-week move lower into the end of March.
Wage negotiations continue to yield gains for Japanese workers and the March meeting is getting close to being fully priced in. While I see a 67% chance of March hike implied by market pricing, it feels like it’s close to fully expected by the market now. Perhaps it can never get above 80% or so given the number of false starts and fakeouts over the past 18 months.
https://www.japantimes.co.jp/business/2024/03/07/economy/japan-wages-january/
A Reuters story overnight said:
(Bloomberg) — An increasing number of Bank of Japan policymakers are leaning toward scrapping the central bank’s negative interest rate in March given expectations of larger wage increases this year, Reuters reported. Whether the BOJ board will move in March or April is still not decided, Reuters said, citing four sources familiar with the central bank’s thinking.
I think it’s hard to get excited about long JPY at this point given the hike is priced in. Unless you think this will be the start of a much more aggressive hiking cycle in Japan, it’s a tweak that reverses the 2016 rate cut. That rate cut, which was supposed to be a watershed JPY-negative event, had zero impact on the yen beyond about six hours. I would guess now that we have priced this thing in, the JPY trade is all about the rise or fall of global yields (ex-Japan) and now your yen view should simply match your global rates view and your USDJPY view should match your view on the US 10-year.
The CADCHF idea is stale. Bank of Canada was hawkish and the jobs data today don’t offer any reason to hold onto the trade into next week. The trade is short carry and has no relationship to US CPI and therefore I am squaring it up around flat P&L. I am also a big believer in going on vacation with no view and no risk in order to cleanse the mind and defrag the mental hard drive in order to return fresh and fully open minded. The CHF trade remains popular and moderately crowded, but my CAD view is super stale and it’s time to square up.
This week’s Macro Trading Floor podcast with Alfonso Peccatiello covers the USD down story and a ton more. I hope that listening to our conversations will become part of your weekend routine. There is a hard stop on the podcast at 40 minutes, so that’s the most time you’ll ever need to commit. I am less awkward this week than I was last week, though there is one awkward exchange at the end when Van Halen comes up. I like Alf, but his knowledge of popular music is atrocious.
Anyway, here’s the podcast, I hope you like it.
https://www.spectramarkets.com/amfx/tmtf-8mar24/
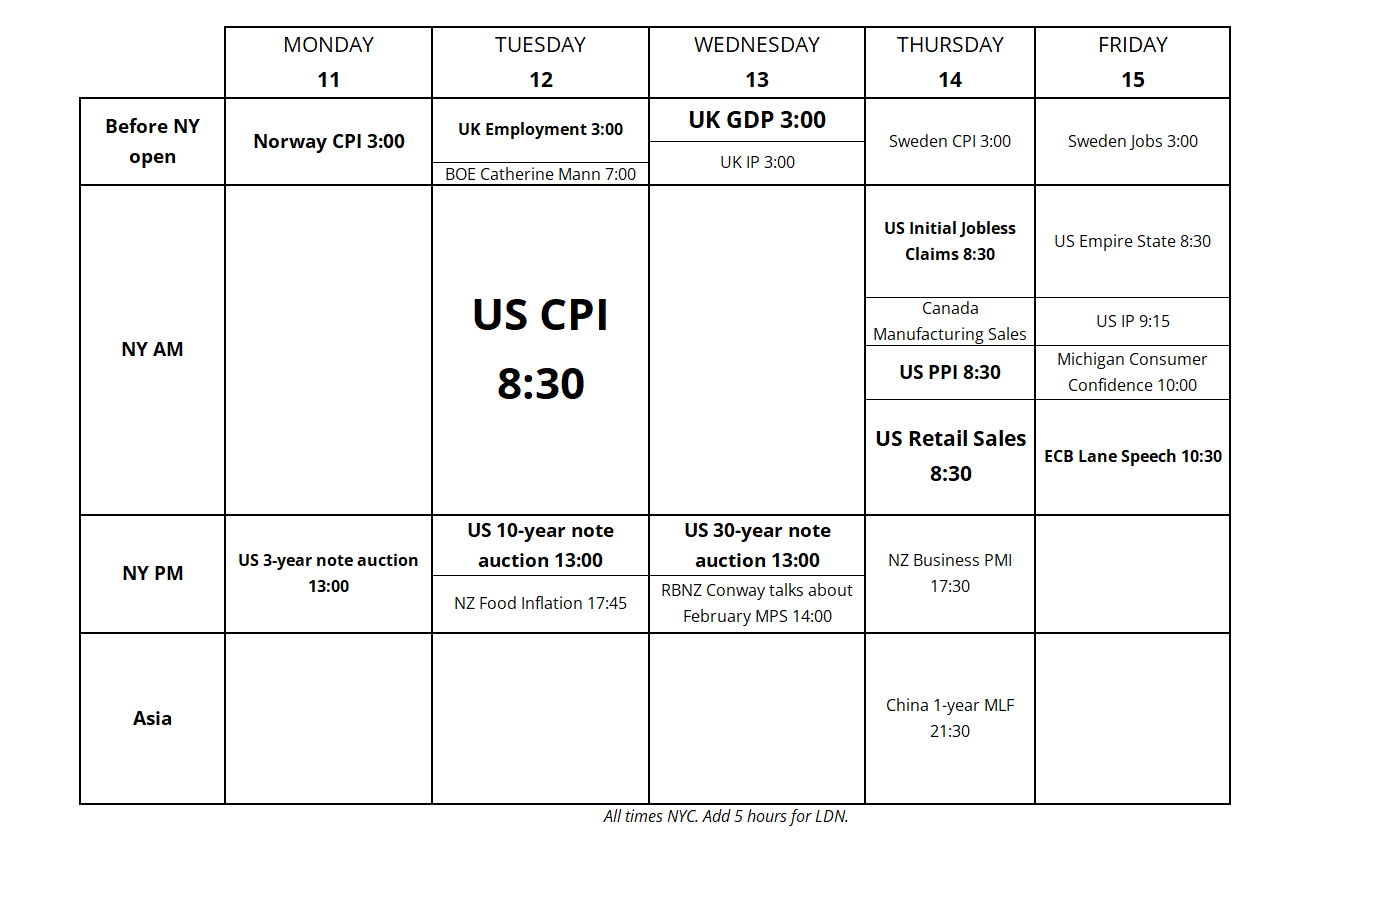
Next week is light on economic events because the Fed is in blackout and usually Fed speeches and TV appearances are half the items in my calendar! US CPI obviously the huge one with some middling stuff out of the UK and Norway. Thursday, there’s a full slate as we find out if January Retail Sales were just a bad weather thing, and Friday’s speech from Lane could be interesting, maybe?
I will be off next week for a family visit. am/FX returns Monday, March 18. Good luck with CPI.