
The second half of April is likely to be much less exciting than the first half but the next few days could remain spicy as Williams says rate hikes are not off the table.

The second half of April is likely to be much less exciting than the first half but the next few days could remain spicy as Williams says rate hikes are not off the table.
Short EURJPY @ 164.10
Stop loss 165.76
Take profit 160.16
As discussed yesterday, I was generally bearish USD on the view that we stay in a mean reversion regime and USD long positioning is extreme and overcooked. That said, I don’t expect an inverted V-shaped top in the dollar, I expect a slow topping out / distribution process. Recent foreign policymaker comments pushing back on USD strength vs. Asia is another reason to think further upside USD progress will be limited and/or unimpulsive.
As Asian central banks intervene in their respective pairs (USDKRW, for example), they will need to buy G10 FX (EURUSD etc.) to rebalance. That is probably what put the bid under EUR yesterday in the 30s.
On the other side of the ledger, Williams opening up the hikes side of the distribution today via this comment: *WILLIAMS: RATE HIKE NOT BASELINE, BUT POSSIBLE IF DATA WARRANTS, makes me question my view. It appears to reopen the hike side of the future FOMC probability distribution, and could push the USD back up into the top of its range.
Still, despite Williams, we are now entering somewhat of a dead zone for data and events as there is nothing major on the docket between now and the end of the month. This is typical as the US economic data is front loaded with ISM and NFP at the start and CPI in the middle. We get PCE near the end, but that is easy to forecast with so many clues provided by CPI and PPI and thus PCE release tends to offer little new information (or volatility) for markets.
You can see this if you look at the volatility of various products by day of the month. The front half of the month is more volatile. Today’s first chart shows SPX volatility by day of the month since 2009.
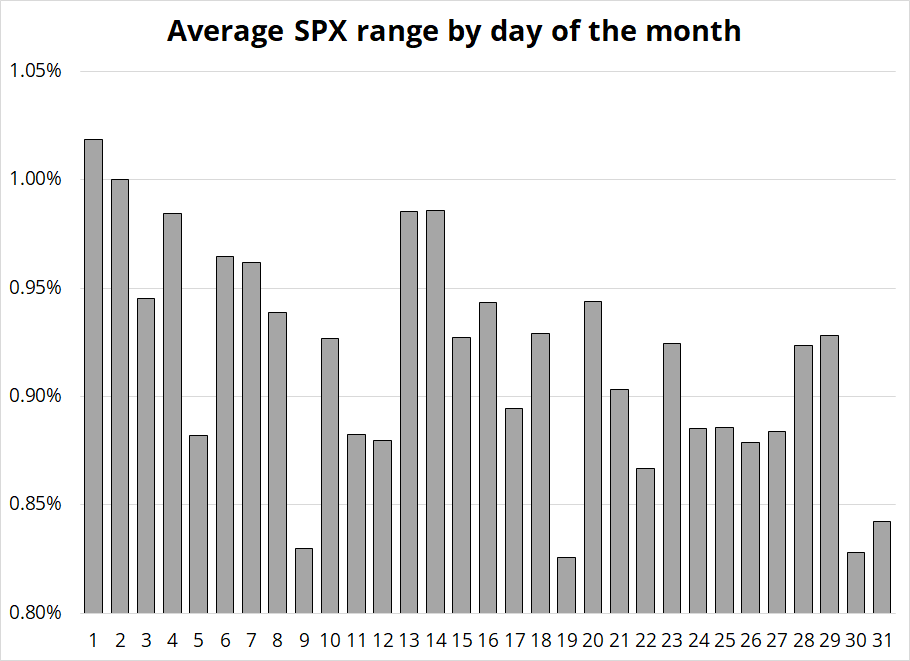
You can see in that chart that the start and middle of the month, when US data gets released, are more volatile than the other periods. Same for USDJPY. The only difference with USDJPY is that the last day of the month is more volatile due to real money and central bank rebalancing.
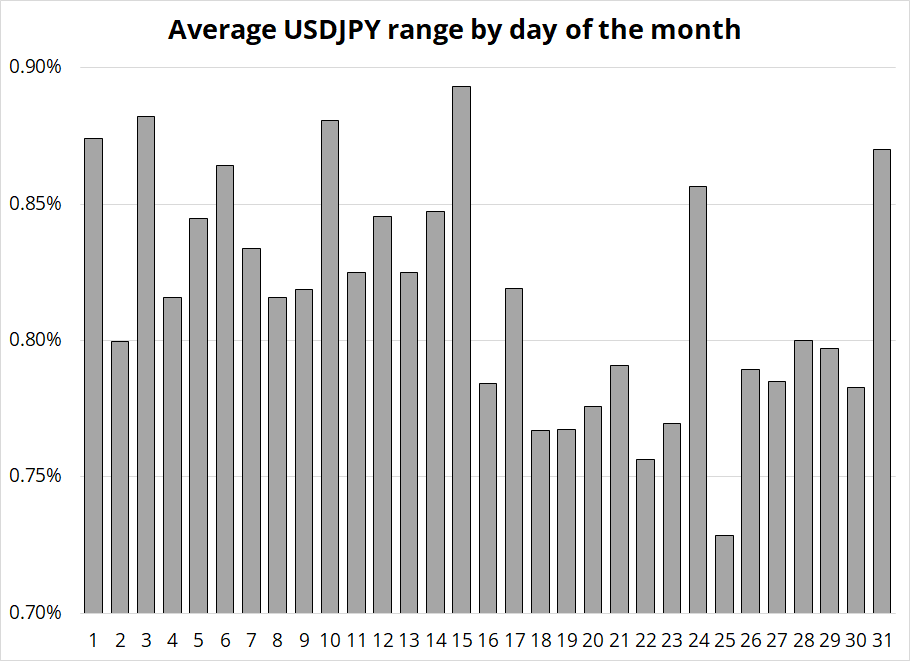
I don’t show it on the chart, but in case you’re curious, corporate month end (last business day of the month minus 2 days) shows an average range of 0.88%, and is thus more volatile than normal.
I think we are entering two weeks of lower volatility as the NASDAQ selloff consolidates and there will be very little new macro information. But today could see more vol as Williams has said the thing that everyone thought the Fed might say one day soon. Still, beyond today’s moves, long vol could be frustrating in FX, especially as the Asian currency interventions tend to be vol-suppressing too.
This makes trades like selling 29APR to buy 1-month in FX options potentially interesting once the dust settles, though these are trades for options gurus, not for spot monkeys like myself. The USDMXN curve is inverted right now due to recent high realized volatility, but I don’t think the currency will continue to realize at these levels, so selling that elevated vol (with good risk management!) is probably nice.
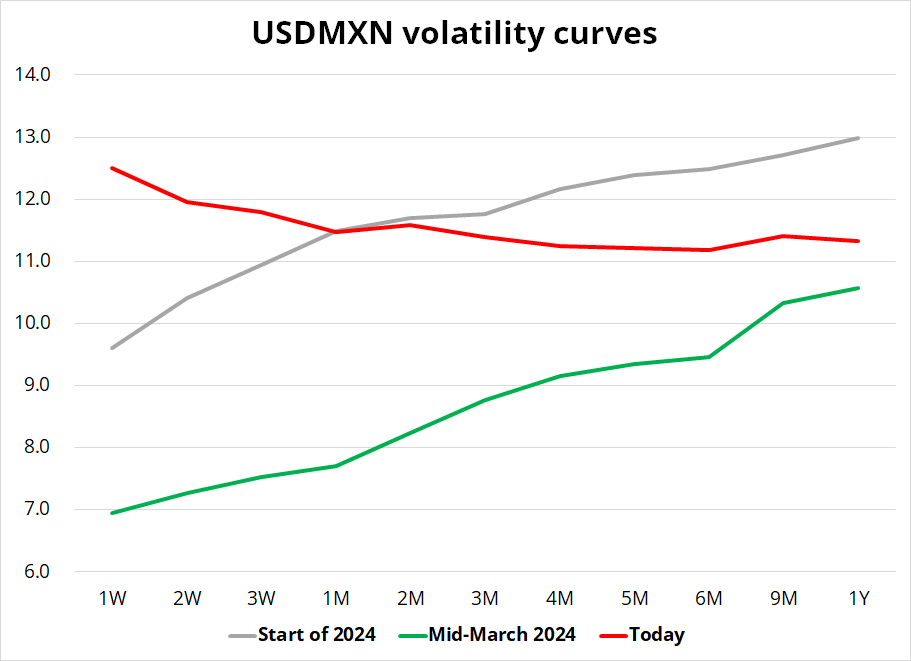
Above you can see the evolution of MXN vol, comparing the start of 2024, mid-March (when stocks made the all-time highs) and now.
Note that as you look over the horizon into May, the 1st is a double play with ISM and FOMC and then we have nonfarm payrolls on the 3rd. That’s a juicy little window and you probably don’t want to be short that given the uncertainty around Fed policy right now.
In conclusion, now until 29APR is theoretically a dead zone for volatility, but the Williams comments could trigger a new surge of fixed income vol and USD upside over the next day or two. And while I was bearish USD coming into today, Williams makes me think there is no immediate rush to sell vol or sell dollars.
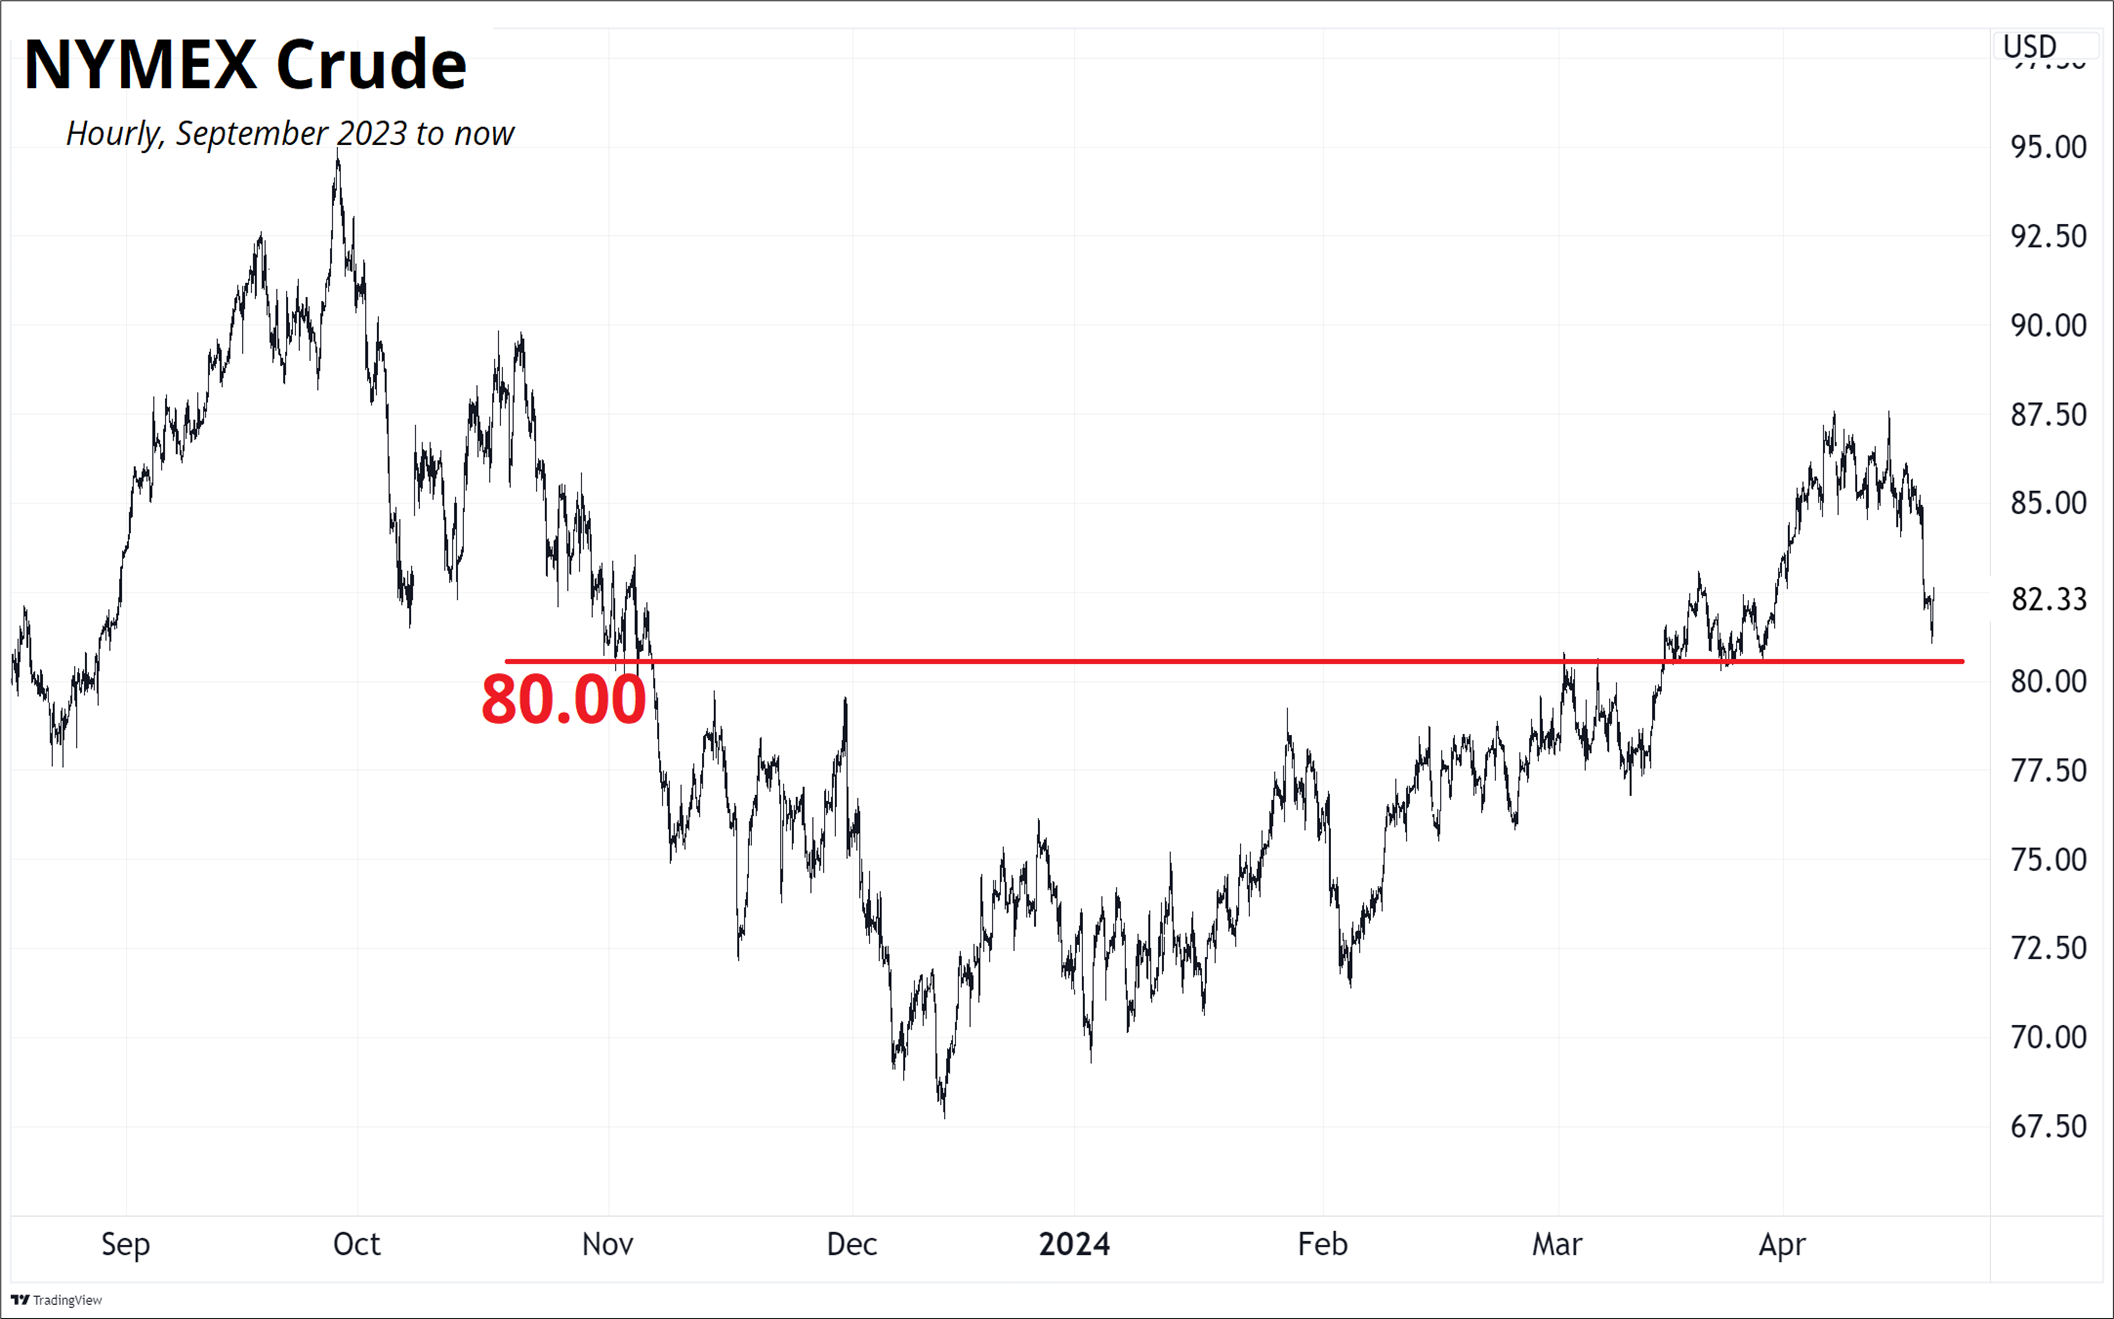
Oil. Hmm. We need to hold above $80 to avoid a large capitulation of geopolitically-inspired longs. You can see that once we broke 80.00 in November, we entered a new range (68/80) and once we recovered the 80 level that became support again. $80 is a good pivot to either buy ahead of if you’re bullish here and flat, or to exit longs or go short if that’s your way.
Finally, I’m surprised how many veteran FX people whom I respect do not think MOF intervention is a high odds scenario for USDJPY between here and 156.00. I have high conviction on this. There is rarely this much policymaker smoke without imminent fire and the parallels to September 2022 and October 2023 are thick Both of those times, policymakers successfully squashed raging rallies.
But I’ll do my best to keep an open mind.
Bee good, honey.
HT CnD


This piece is mostly for people who are interested in backtesting

