Deep Thoughts
I tried to sell the rally in CADJPY, but it didn’t quite get to my level. My view is that global yields are probably topping out for now, so I have turned from bullish cross/JPY to bearish but the entry points here are not great. I don’t think yields are going substantially lower, I think they will just have trouble going up. While USDJPY moved on the BOJ news last night, my view remains that global yields matter for USDJPY and BOJ is a red herring or single-day story.
Outside of Japan, we are still in a period of central bank convergence where everyone turned dovish, then they turned a bit less dovish, but they’re all still ready to cut once the last mile of inflation looks doable. The RBNZ is on board the dove train now too.
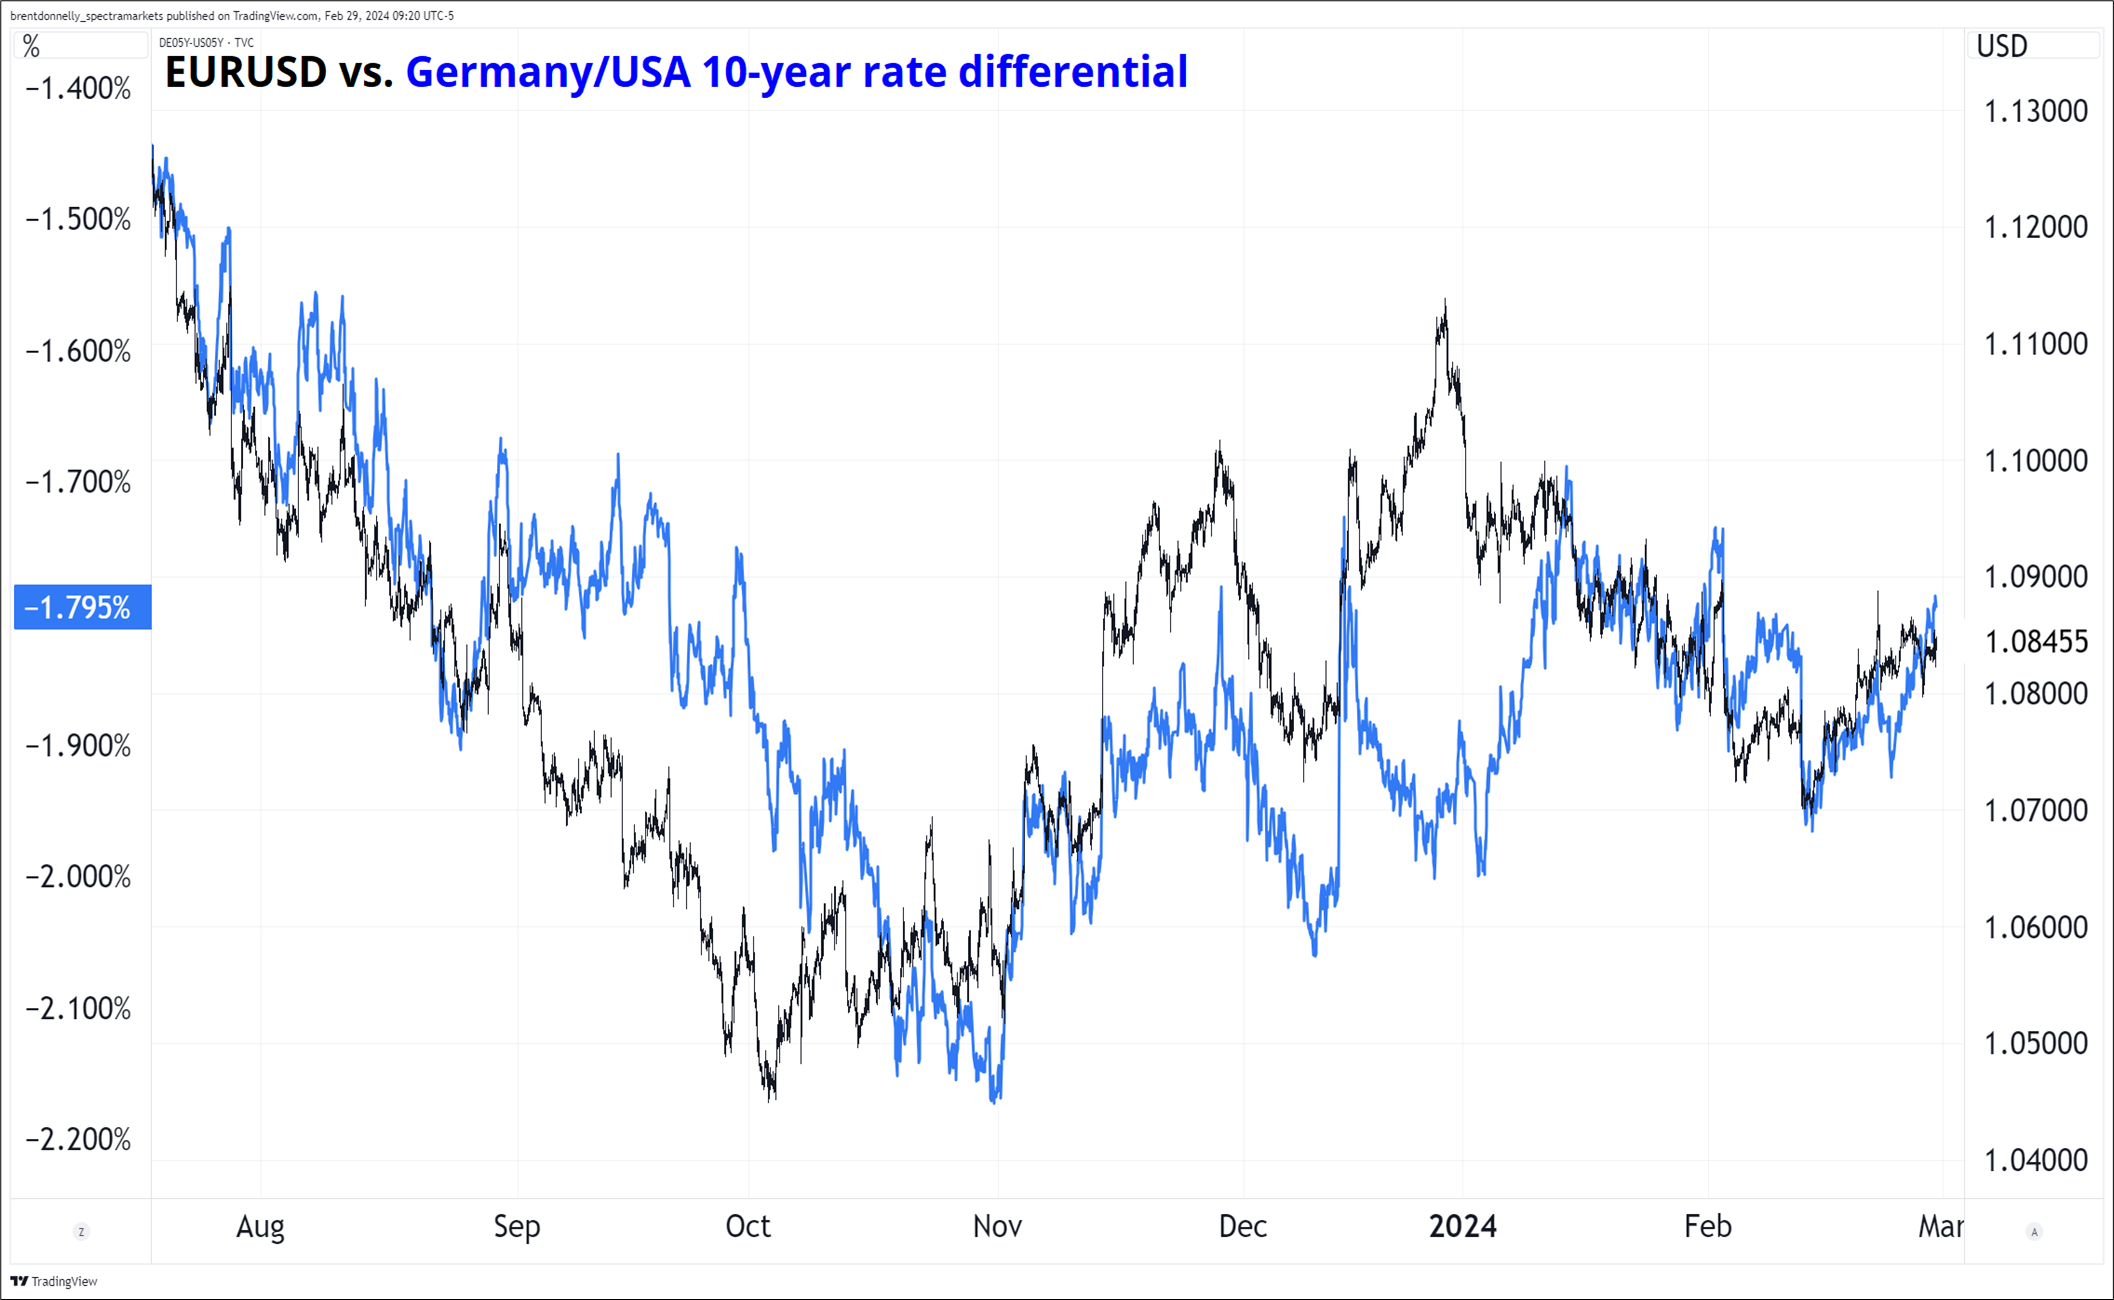
So you end up with a lot of overlays that look like this chart here. Note how the rate differential is an EKG since November as the Fed and ECB are echoing one another, saying cuts are on the table around the same time and then pushing back on a March cut around the same time.
The whip inflation now mission is not yet fully accomplished but we don’t know if January data is simply skewed by the hard-to-adjust seasonal or if we are reaccelerating. We have a very poor understanding of inflation, and while most people are pretty sure the Fed doesn’t have much to do with the reversal of inflation, they still have to do what they do and keep things restrictive until inflation is clearly beaten. We might have a good idea by March or so.
Meanwhile, with pricing now matching the dots, my supposition is that further elimination of cuts will be more difficult as the market should be sticky right here around three cuts given that’s what the Fed is thinking for now. It’s unlikely the dots would go to two cuts in March, but by June that is easily possible.
If inflation does reaccelerate from here, it would be worrisome because that would be a more organic inflation caused by a strong economy, rising wages, interest rate stimulus for households who own fixed income, equity wealth effect, and the new psychology post 2021 where businesses include raising prices as part of their strategy. Before COVID, most companies just did some kind of monotonous pricing strategy with small price increases but now they think hmm, if we can raise prices 8% this year and lose 4% of our volume, should we try? It worked last time!
At the end of the day, I still believe that the secular factors will eventually dominate as technology and demographics win and we go back to some kind of secular stagnation+ regime where things are not roaring like the 90s but they’re not sucking wind at the ZLB like the 2010s. But it won’t happen in a straight line and if February inflation data released in March is surprisingly strong, everything is going to reprice and the narrative will flip from disinflation, yay! to something more like “hmm, what’s going on here?” The Fed telling the market that they are done hiking and are ready to cut at some point doesn’t help as it juices financial assets and maybe housing.
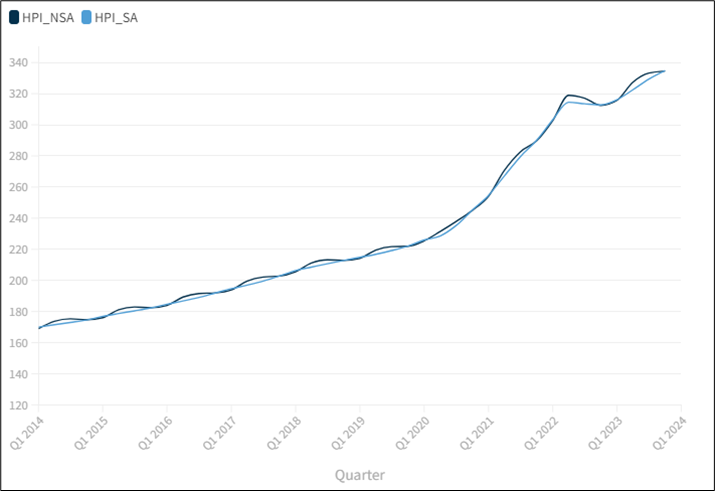
Speaking of housing, the resilience has been amazing. Here are home prices.
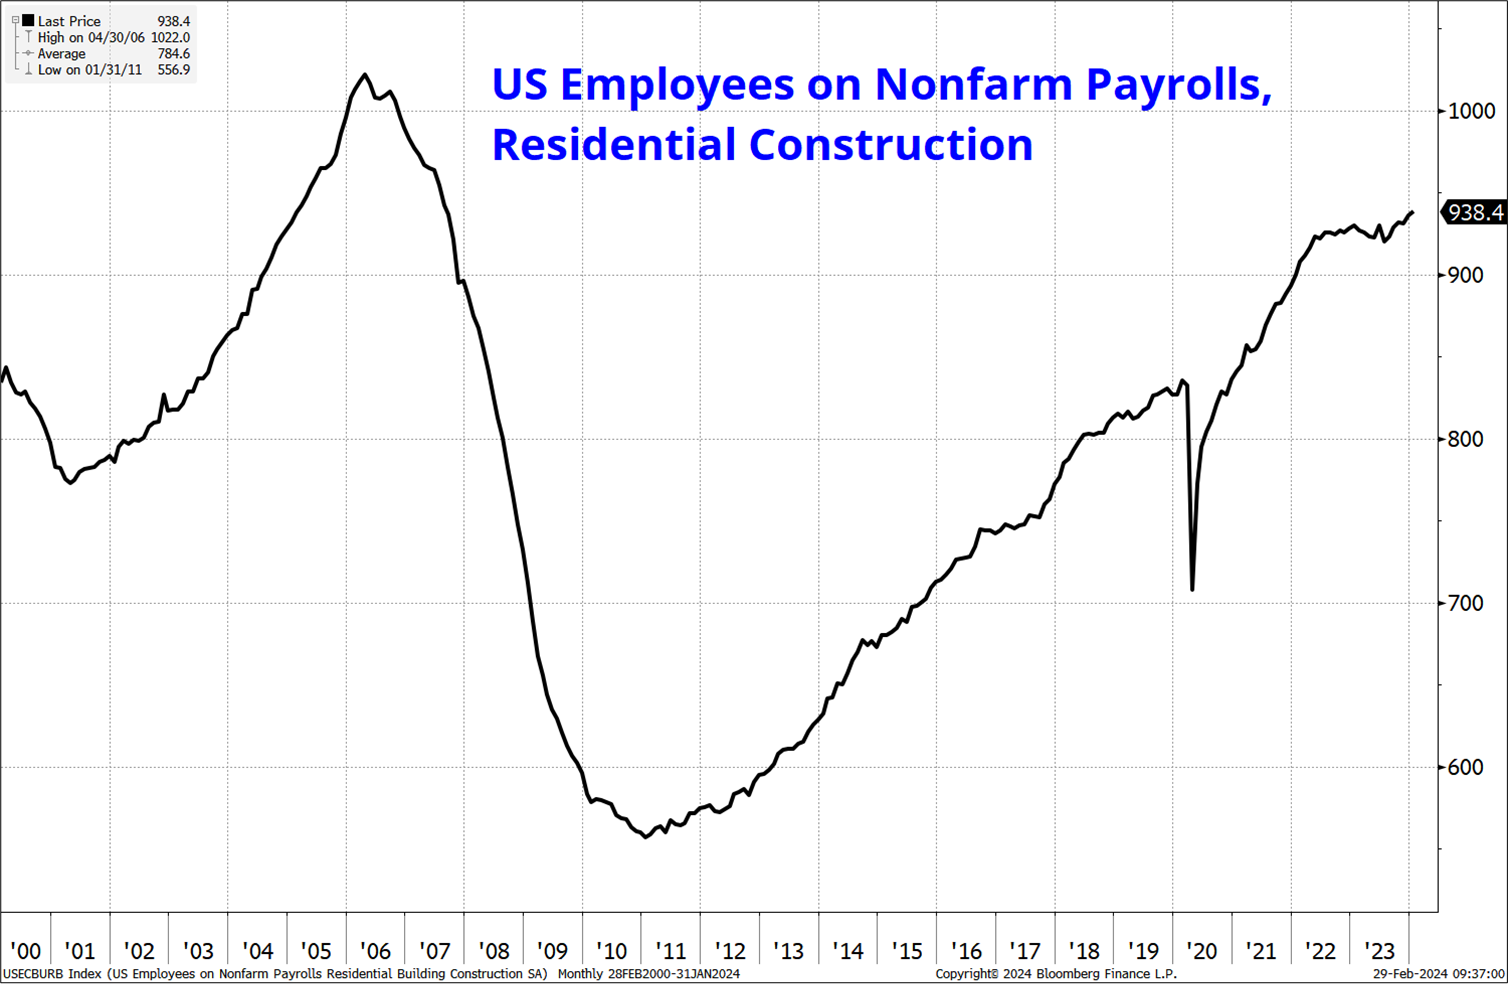
This spring housing market in the US will be interesting as we are now well out of the emergency WFH buy a house in the suburbs thing and there must be tons of trapped demand that now has to decide if they want to secure a mortgage at these rates and a house at these prices. Waiting for the dip can be costly as there just aren’t very many. In 1996, I bought my apartment at 72nd street and 1st avenue for $119,000 and when I decided to leave finance and pursue a career as a writer or movie producer or something (!) everyone said: “Dude, housing prices in New York have been going straight up for 10 years, hit the bid!” Needless to say, the $139,000 bid I hit looks pretty low today.
Final Thoughts
Trading FX in these low-vol regimes (similar to 2006, 2014, and 2019) is difficult but not impossible. Carry tends to work well because vol is so low, and selling vol in reasonable ways can still work too. The temptation is to see where vol is and buy it, but any DNT you bought a month ago paid out 4:1 or 5:1. These low-vol regimes can be sticky. The best thing I find in these regimes is to focus on events and catalysts because stuff still moves on those days, it just doesn’t lead to a macro narrative or trend.
Have a singular day.