An update on USDJPY’s return to normal. And a 6-month USDINR idea where if it’s wrong you can blame Phil and if it’s right you can thank me.
This is the least-used emoji

An update on USDJPY’s return to normal. And a 6-month USDINR idea where if it’s wrong you can blame Phil and if it’s right you can thank me.
This is the least-used emoji
Flat
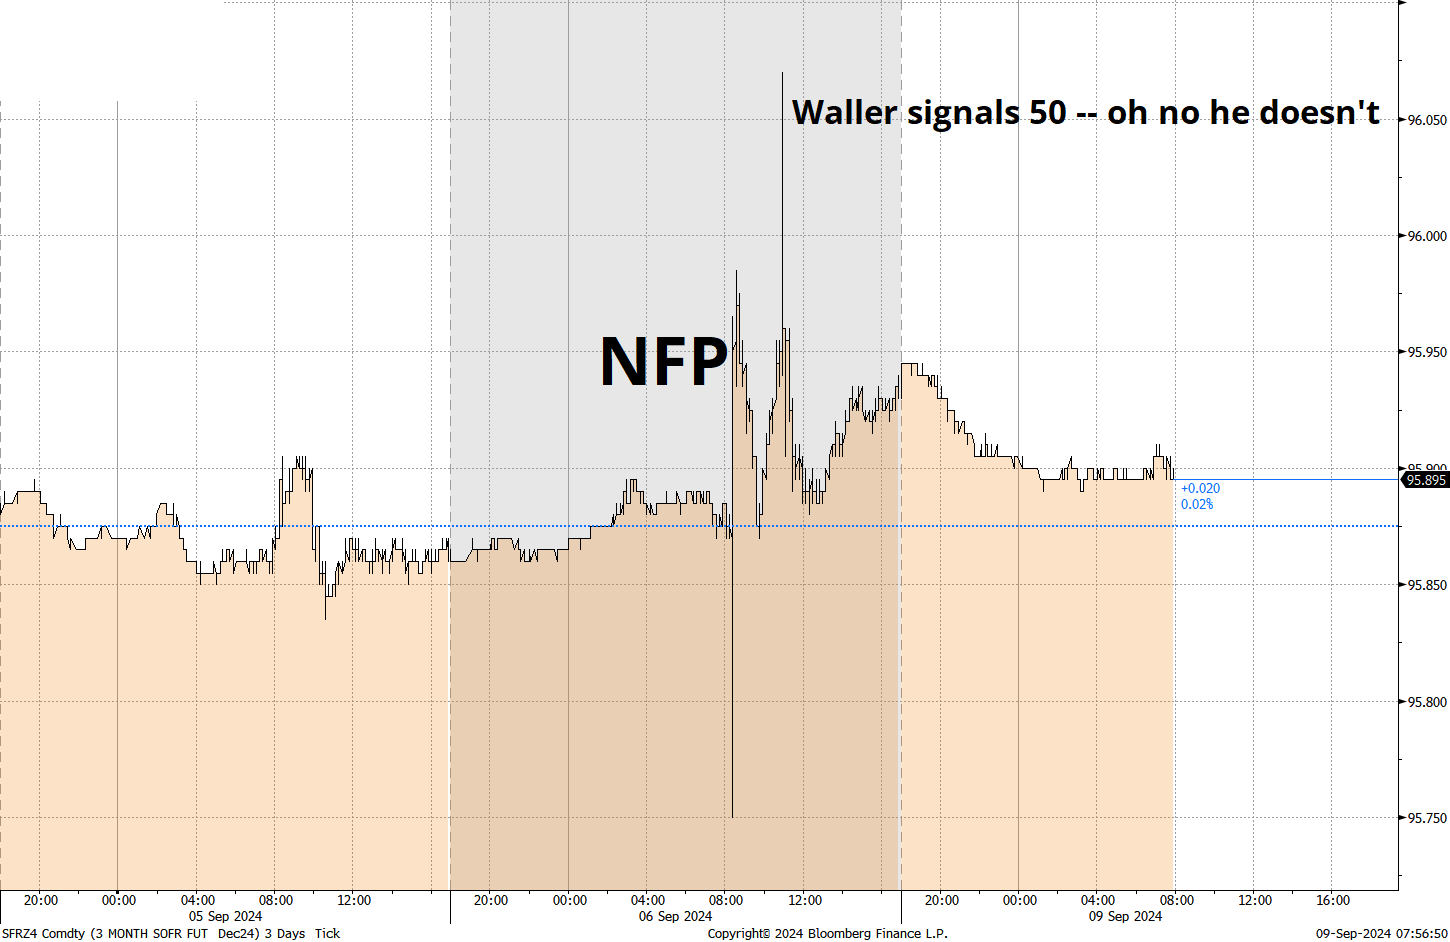
In case you missed it, here is a chart of SFRZ4 on Friday as NFP was mildly soft, and then initial headlines indicated Waller prefers 50 bps, but subsequent headlines and a reading of the text suggested he was not offering clear insight into his preference of 25 vs. 50.
Here’s Nick Timaraos:
Fed governor Chris Waller’s speech doesn’t explicitly say “25” or “50” but it leans into endorsing a 25 bps cut to start, explicitly reserving the option to go faster “as appropriate” if “new data” show more deterioration Waller pats the Fed on the back for not overreacting to the banking crisis, the lower inflation prints of 2H 23, the higher prints of Q1 24.
Then he says, “Based on the evidence I see, I do not believe the economy is in a recession or necessarily headed for one.” Watch these “if” statements (emphasis mine): “*If* the data suggests the need for larger cuts, then I will support that as well. I was a big advocate of front-loading rate hikes when inflation accelerated in 2022, and I will be an advocate of front-loading rate cuts *if* that is appropriate.”
“Those decisions will be determined by new data” [presumably, that does not include today’s data] “While I expect that these cuts will be done carefully as the economy and employment continue to grow, in the context of stable inflation, I stand ready to act promptly to support the economy as needed.”
“Front-loading” was in the first batch of Bloomberg headlines, but “carefully” was not. And Waller’s words were essentially a series of confusing “if” statements that sent SOFR on a 17bp round trip to nowhere.
USDJPY made an impressive double hold of the critical 141.80 level and is now firmly in the middle of what looks like a 141.80/145.50 range. It has gone back to tracking yields very closely as you can see in the 5-minute below. USDJPY has been trading with a tight correlation to yield diffs since mid-July.
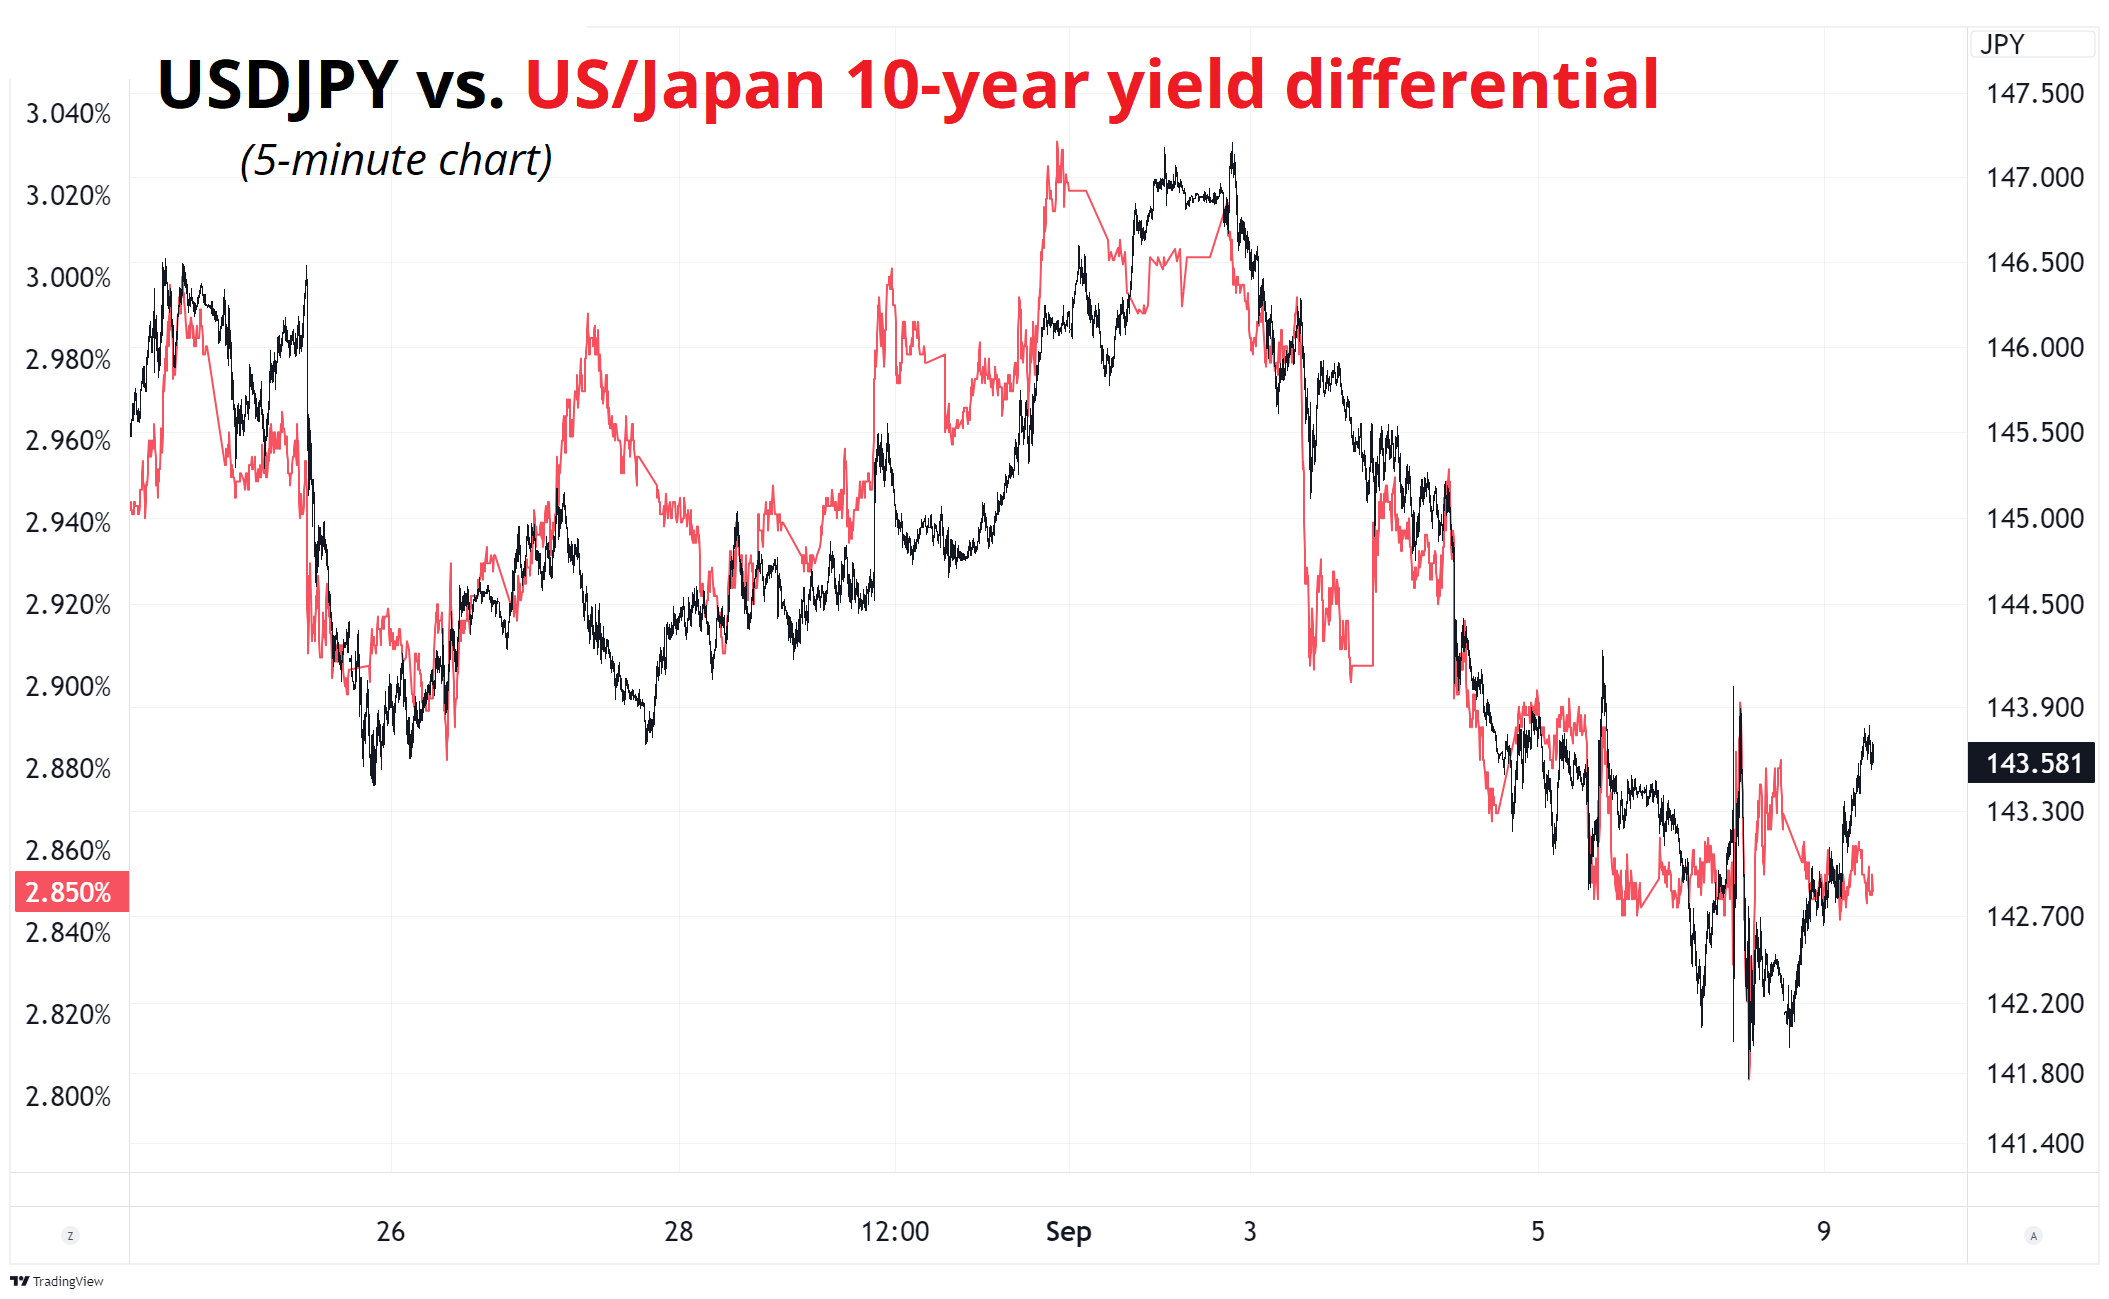
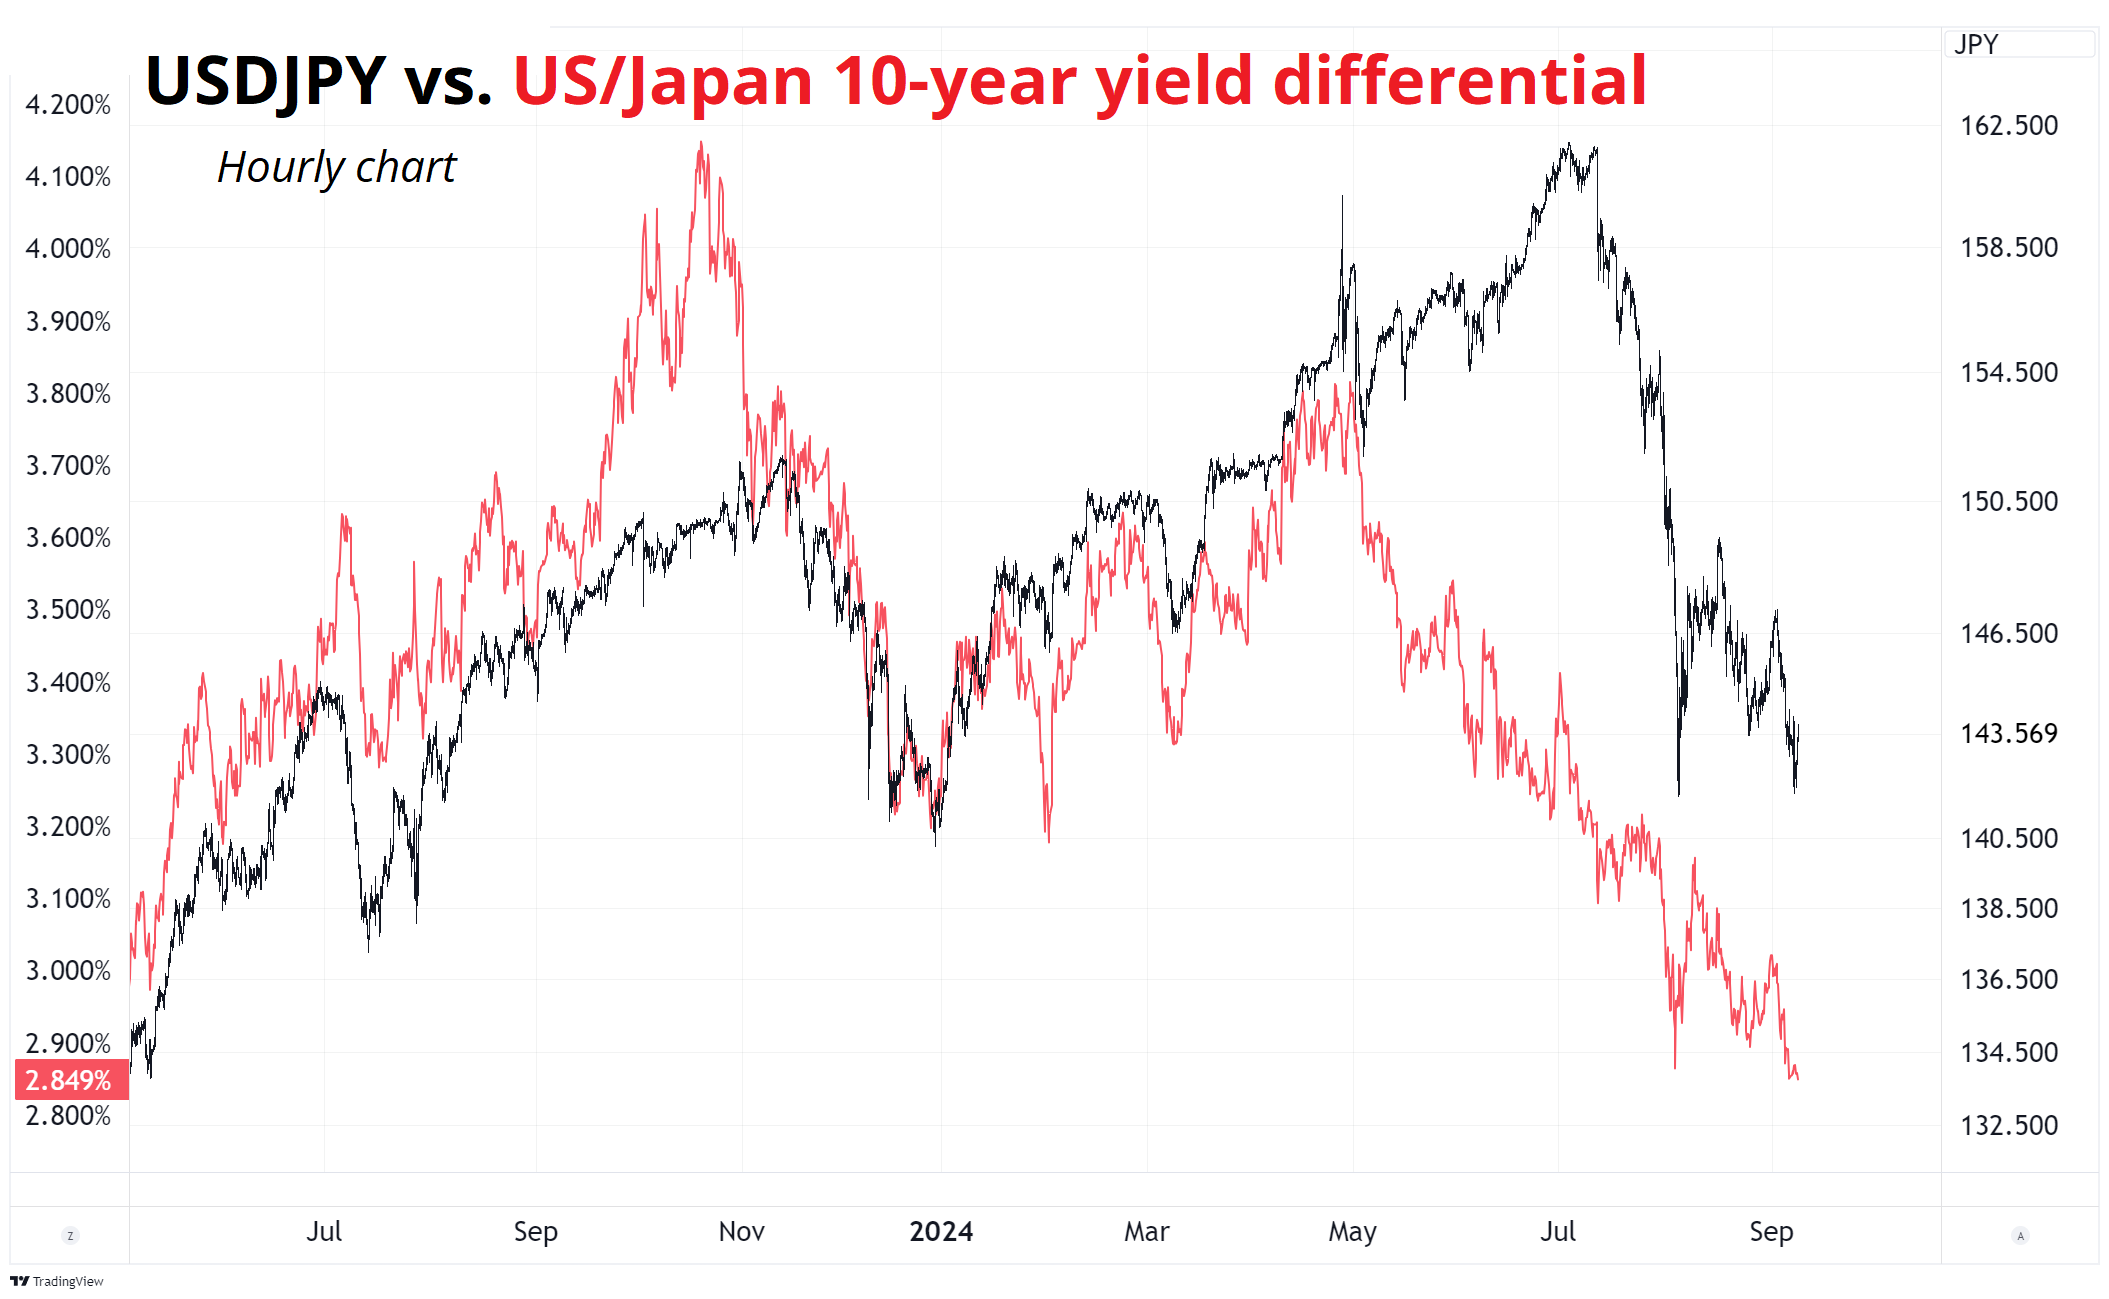
This is a return to normal form after the summer weirdness, where USDJPY decoupled from rates between June 7 and July 15. See the second chart, which shows the same thing zoomed way out.
You can see that in May/June, the market began to believe that there was nothing that could stop the JPY depreciation and the market justified continued USDJPY bullishness by noting that levels of rate differentials were still significant despite negative changes (i.e., it went from 3.8% to 3.4%, but people said “yeah it’s lower but 3.4% is still a lot!”)
Skeptics at the time (like me) lost money because the MOF took forever to get involved and the divergence between USDJPY and yields persisted for so long. It was nigh impossible to trust the signal from yields after it had been wrong for 6 weeks or so.
Then, the MOF came in and crushed it. And then the BOJ hiked rates. And more rate cuts got priced in the USA. This is a textbook example of how FX intervention is supposed to work. You intervene in order to staunch the momentum, then pray for help from the macro side. The MOF got help from both sides as (probably not coincidentally) the BOJ came in very hawkish and then US yields dumped.
It’s a win for the MOF, though it’s worth pointing out that they also sold at 147 in 2022 and while macro cooperated that time, too, yield differentials and USDJPY both went on to make new highs.
Massive reserves, no stop loss, no mark-to-market, and an unlimited time horizon make life easier for central banks than specs who have limited capital, fixed stop losses, real-time revals, and yearly compensation cycles.
I don’t follow India or INR at all, but Phil Valori here at Spectra pointed out something interesting so I’m sharing. Here’s his comment on why 6-month topside USDINR options make sense if you think Trump is going to win.
This INR situation is a really strong trade IMO. The response is: “Oh it never moves” “OH RBI just squash it every time”
But the whole point of this is that until now INR has not been an election trade. The moment that Trump talks about attacking dedollarization, he is aiming his sights at the BRICS, so INR is now on the table for the election for sure.
There is literally NOTHING priced for it. The day weight in INR is the lowest of any FX pair globally for the election.
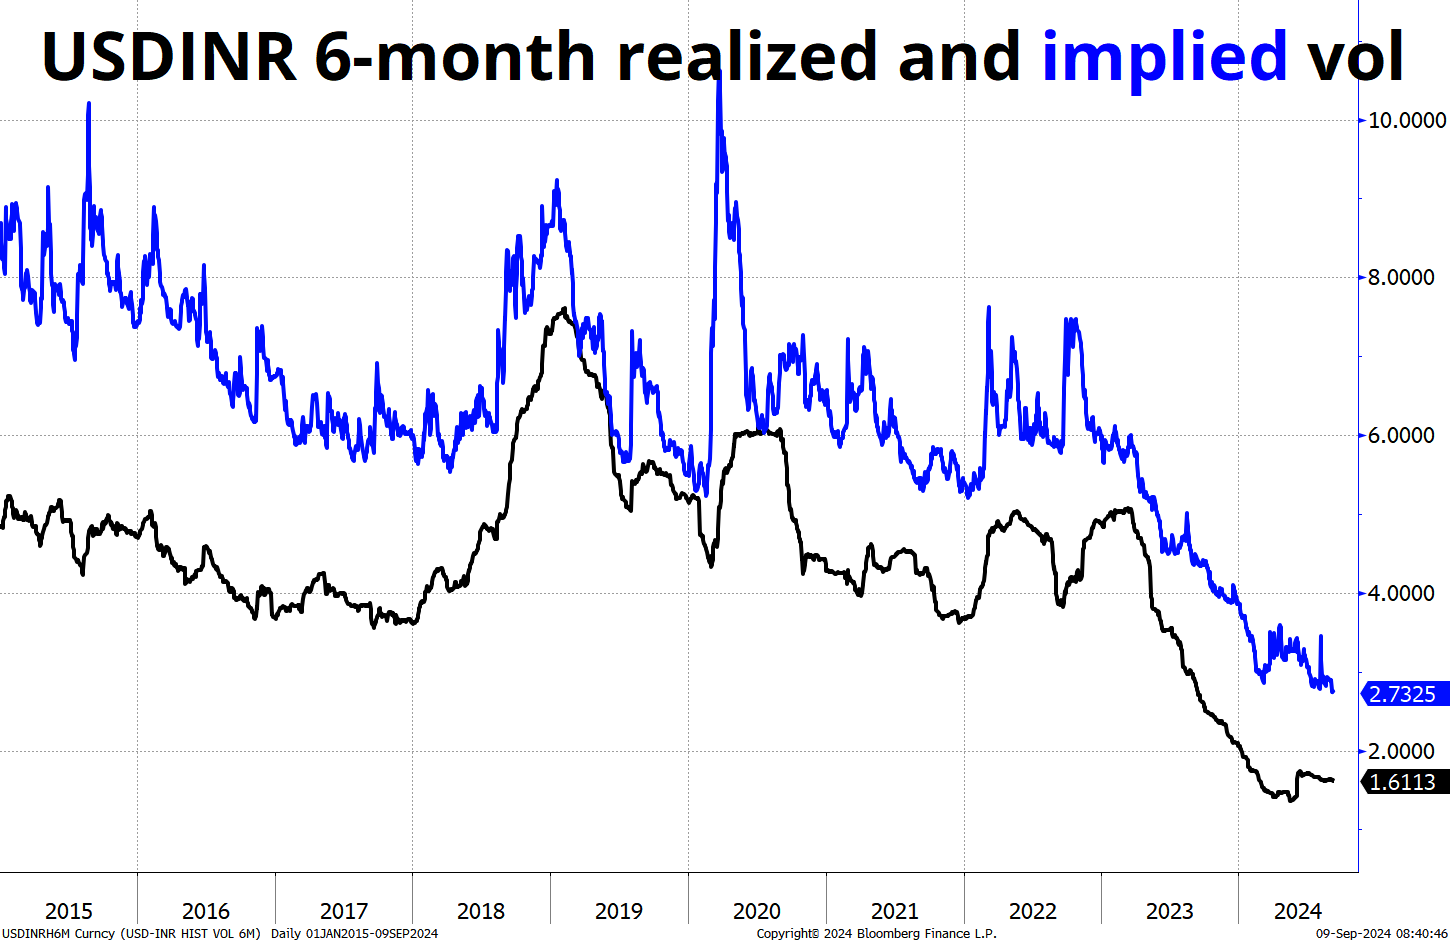
I think this is one of those where you buy it with 0 priced and work out if you really believe in it once everyone else has hedged up and pushed the vols back to 6 which was bang on NORMAL for years for INR.
Like I said, I don’t know USDINR at all, but I took a look at the daily chart, and it screams: THING THAT IS BEING HELD OUT OF EQUILIBRIUM BY AN INTERFERING FORCE. This is what disequilibrium looks like, and the chart honestly reminds me of USDTRY.
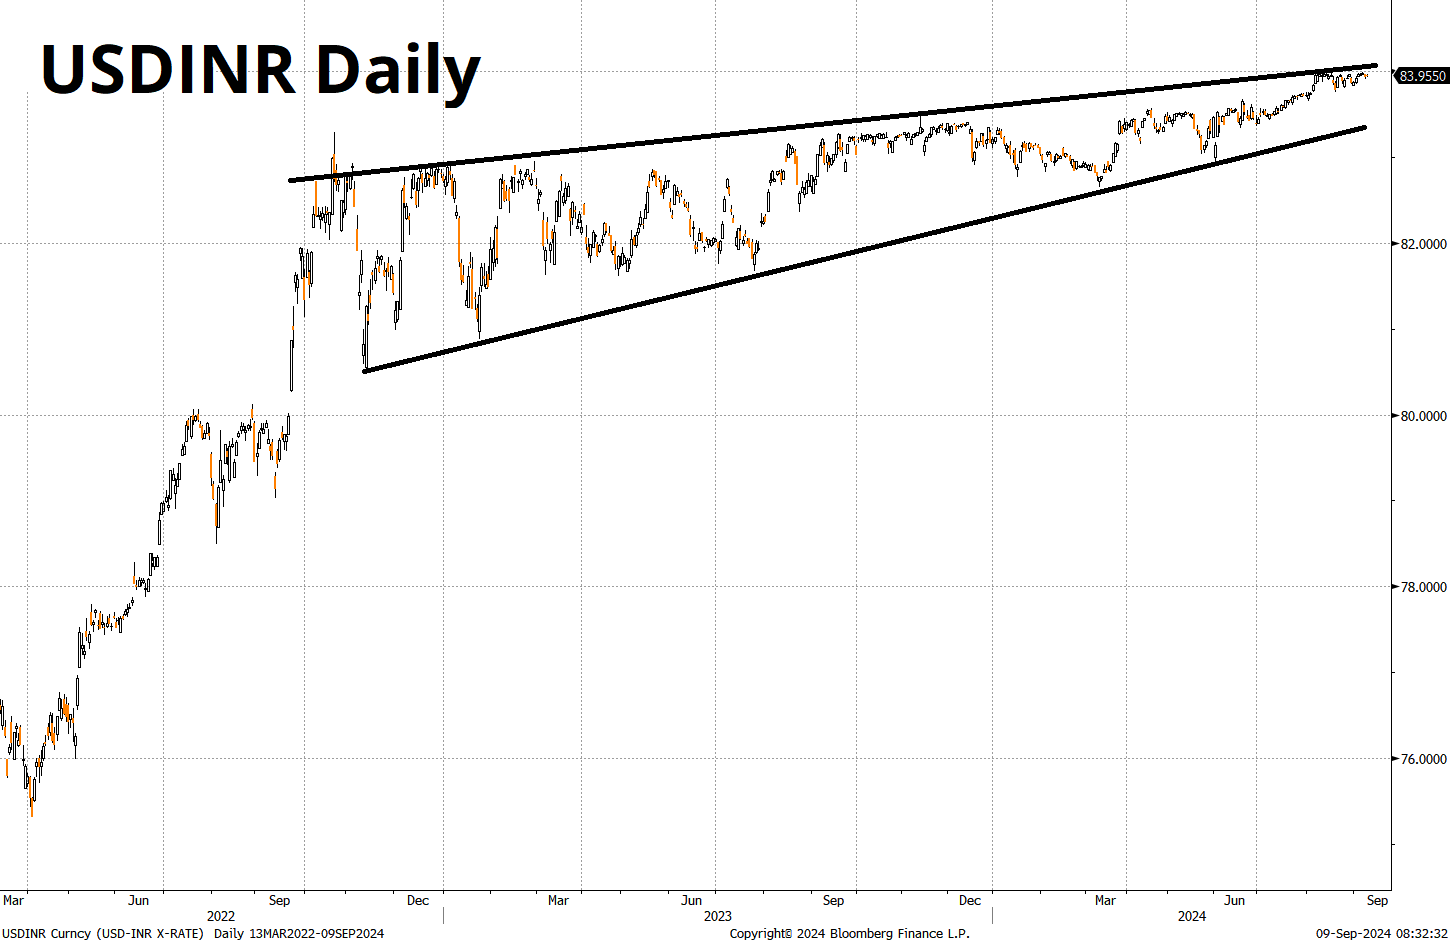
Look at the last 10 days or so, there has been almost zero volatility. As realized volatility collapses, implied vols are following suit, but it’s not necessarily correct to extrapolate this unprecedentedly low vol regime into the future. Trump tariffs and anti-dedollarization are at odds with his supposed desire for a lower USD but in the end, it’s probably tariffs that matter first and foremost if he is elected because they are easy and immediate to implement and have a direct impact on the fair value of the USD vs. Asia.
Take a look at the next chart, which shows 6-month historical and implied volatility for USDINR. The six-month tenor covers the election and inauguration. You can see that USDINR vols are at the all-time lows (data back to 2008 shows 5% to 10% is the normal range, approx.).
If you’re thinking of doing this, probably makes sense to do it before the debate?
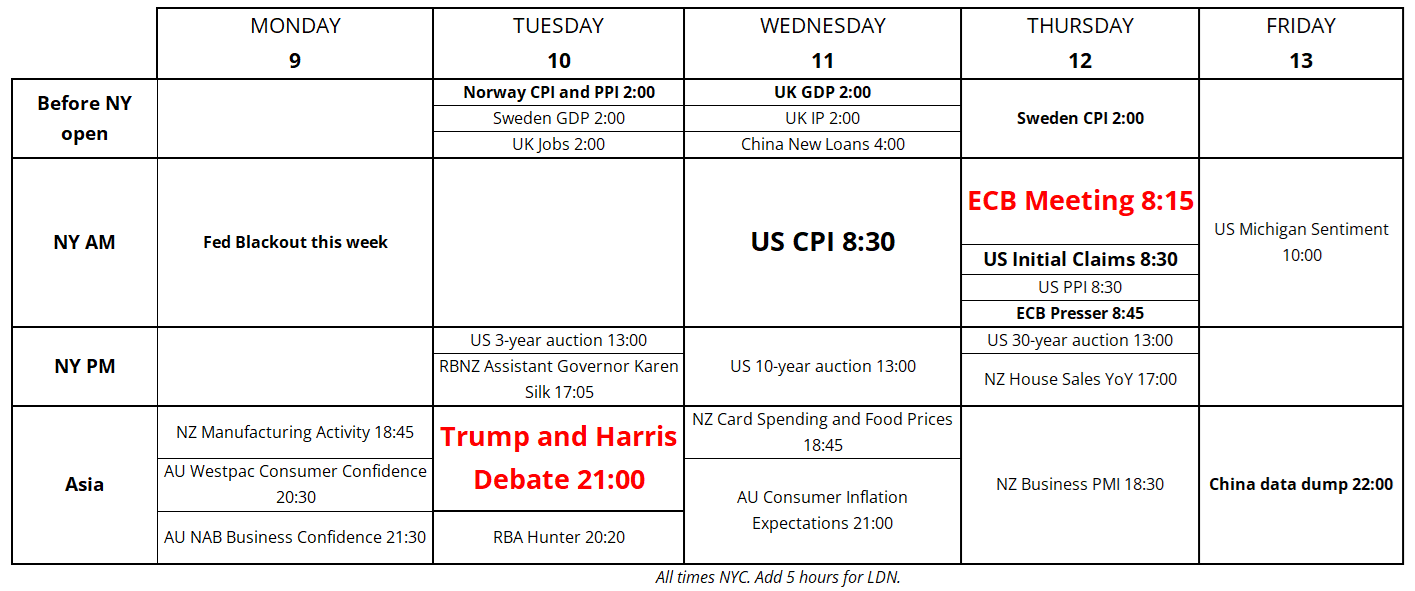
I left out the debate, so here is the updated calendar.
I liked this piece from Ed Yardeni.
Have a symbolic day.
The least-used emoji on Twitter is “Input symbols for symbols”.
Watch for infrequent updates at the Least Used Emoji Bot: