April 28, 2023
Lazarine Dollar
I am surprised and a bit confused by the size of the move in USDJPY. I suppose you can argue a lot of late FOMO shorts came in pre-BOJ and the late BOJ release increased the short base even more, but still, the move is much larger than I would have expected. The idea was wrong from inception, and I will chalk it up as a clear L.
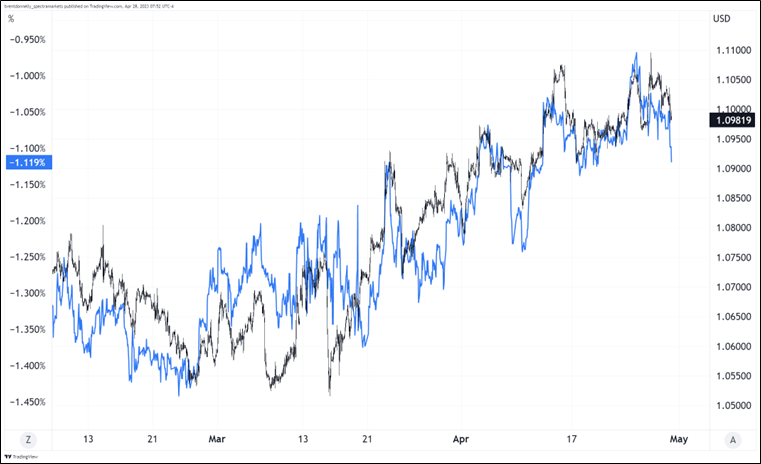
Meanwhile, EURUSD is trying desperately to hold onto the channel as German inflation is a bit weak and rate differentials point to modestly lower EURUSD, but nothing dramatic.
EURUSD vs. Germany/USA 10-year spread
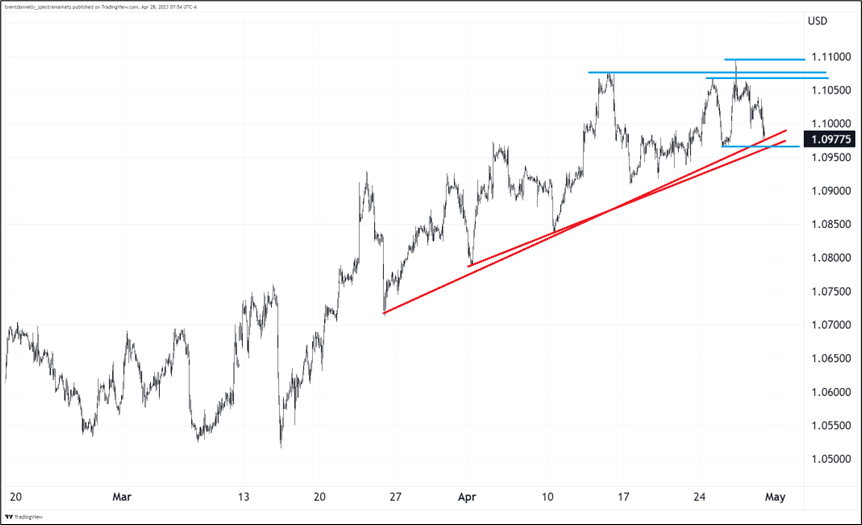
We are getting into the nervous zone for longs here as the steady uptrend that began March 27 is now in jeopardy just as the USD-bearish April seasonal expires and USDJPY rips. Through that bottom cyan line and the trendlines at 1.0950 could trigger more malaise for USD shorts across the board.
EURUSD with primary up trend and series of jaggedy tops
Next week
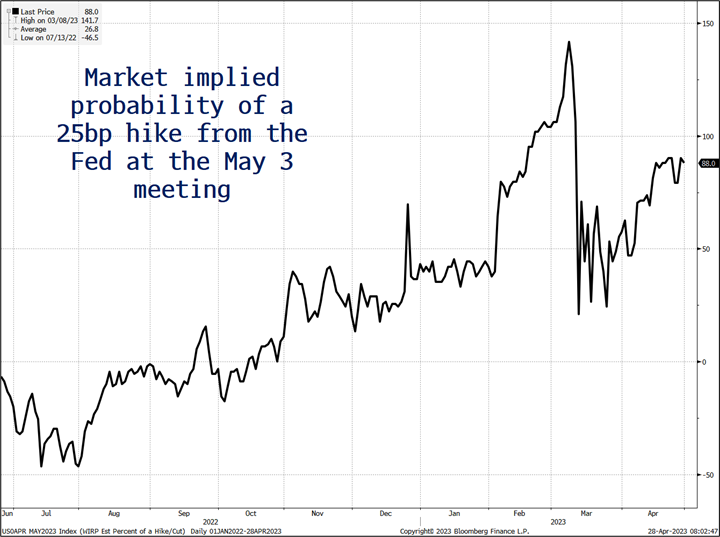
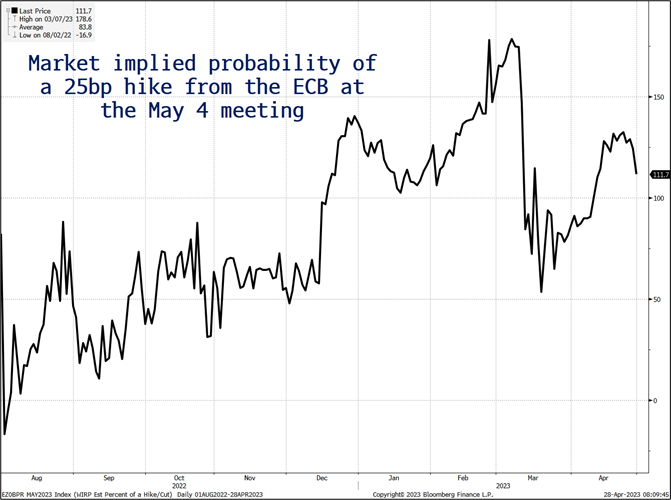
Next week is serious with two ISMs, FOMC, and NFP plus the ECB, RBA and jobs reports in NZ and Canada. Here is the evolution of pricing for next week’s Fed and ECB meetings. The Fed was pricing almost 50/50 of 50bpps at one point before Silicon Valley Bank went bust, and is now around 88% of a 25bp hike next week.
The ECB was almost priced for 50bps, went to 50% of 25bps and is now back to 111% chance of 25bps (i.e., tiny chance of 50bps but consensus strongly at 25bps). Six out of thirteen economists in the Bloomberg survey are still calling for 50bps, which is surprising given those forecasts are not stale, they were updated yesterday. Let’s see.
The market hasn’t priced anything for the RBA, though CBA has the odds of a hike at 55/45, so there is some tiny lean out there towards the possibility of a rate hike in Oz. Real rates are deeply negative in Australia, and I keep waiting for them to do something about it, but they never do. The RBA’s actions have become highly politicized, and this is making their policy harder to predict and more out of line with peers.
Final Thoughts
Excerpt from the Capital One conference call, courtesy of CR:
“The 30-plus delinquency rate within domestic card at quarter end increased 134 basis points from the prior year to 3.66% and is now essentially at its March 2019 level. The charge-off rate hasn’t caught up yet, but based on what we see in our delinquencies, we think the monthly charge-off rate will get back to 2019 levels around the middle of this year.
Our credit metrics tend to move a quarter or two ahead of the industry – we saw that in the global financial crisis, and we saw it in the pandemic, and we’re probably seeing it again here. We are assuming a material worsening of labor markets with the unemployment rate rising from today’s very low levels to above 5% by the end of 2023.”
Have a weekend that is fashionable, overall.
good luck ⇅ be nimble