
Macro, technicals, positioning, and cross-market correlation point to higher EURGBP.
Here we are now. Entertain us.
Macro, technicals, positioning, and cross-market correlation point to higher EURGBP.
Here we are now. Entertain us.
Stop loss 0.8479
Take profit 0.8694
Wages are softer in the UK, and yesterday’s KPMG report is consistent with slowing demand and slowing jobs growth. 200-word summary from claude.ai:
The UK job market continued to weaken in February amid ongoing economic uncertainty. Permanent staff placements and temporary billings both declined markedly as employers hesitated on new hires due to cost pressures. Overall demand for workers dropped at the fastest pace since January 2021, driven by a fall in permanent role vacancies. Temporary job openings also decreased slightly for the first time in over three years.
However, candidate availability rose sharply for the 12th consecutive month as redundancies increased and hiring slowed. The rates of starting salary growth for both permanent and temporary roles eased to nearly three-year lows, though pay continued rising due to high inflation and candidate scarcity.
Regionally, all monitored English areas saw declines in permanent placements, led by London. The Midlands was the only region with growth in temporary billings. Job categories like retail, construction, and executive/professional saw the steepest drops in demand.
Meanwhile, EURGBP is tracing out a quadruple bottom at 0.8500 while interest rate differentials suggest it should be closer to the top of the range, not the bottom.
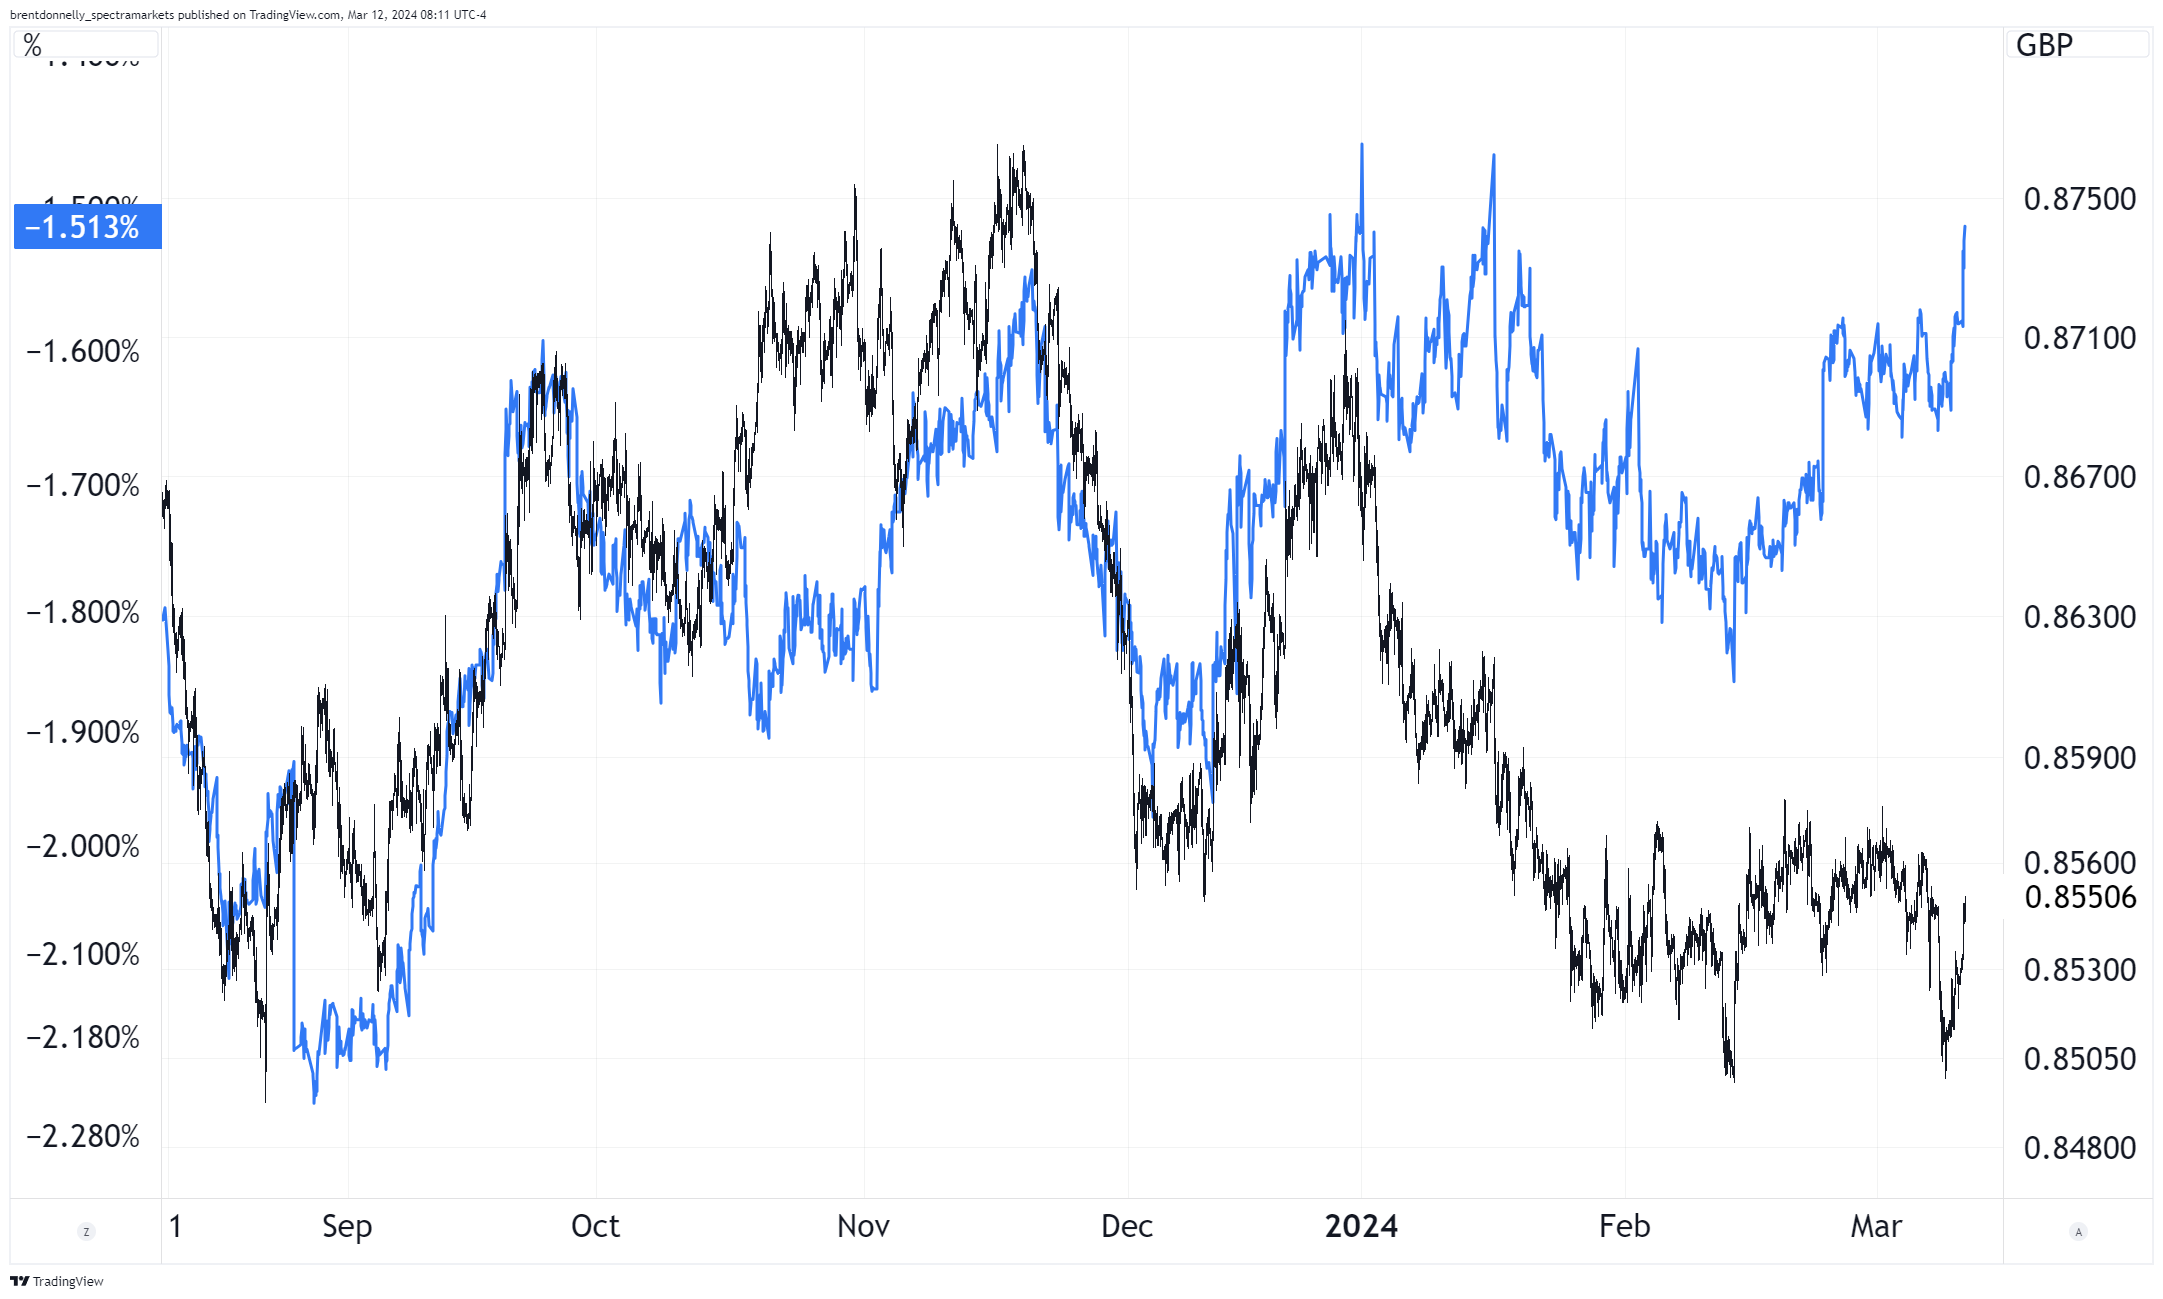
Add this week’s Spectra FX Positioning Report (see further down this page) and you have a nice setup here for long EURGBP. I like spot better than options simply because the stop loss is pretty obvious and somewhat nearby.
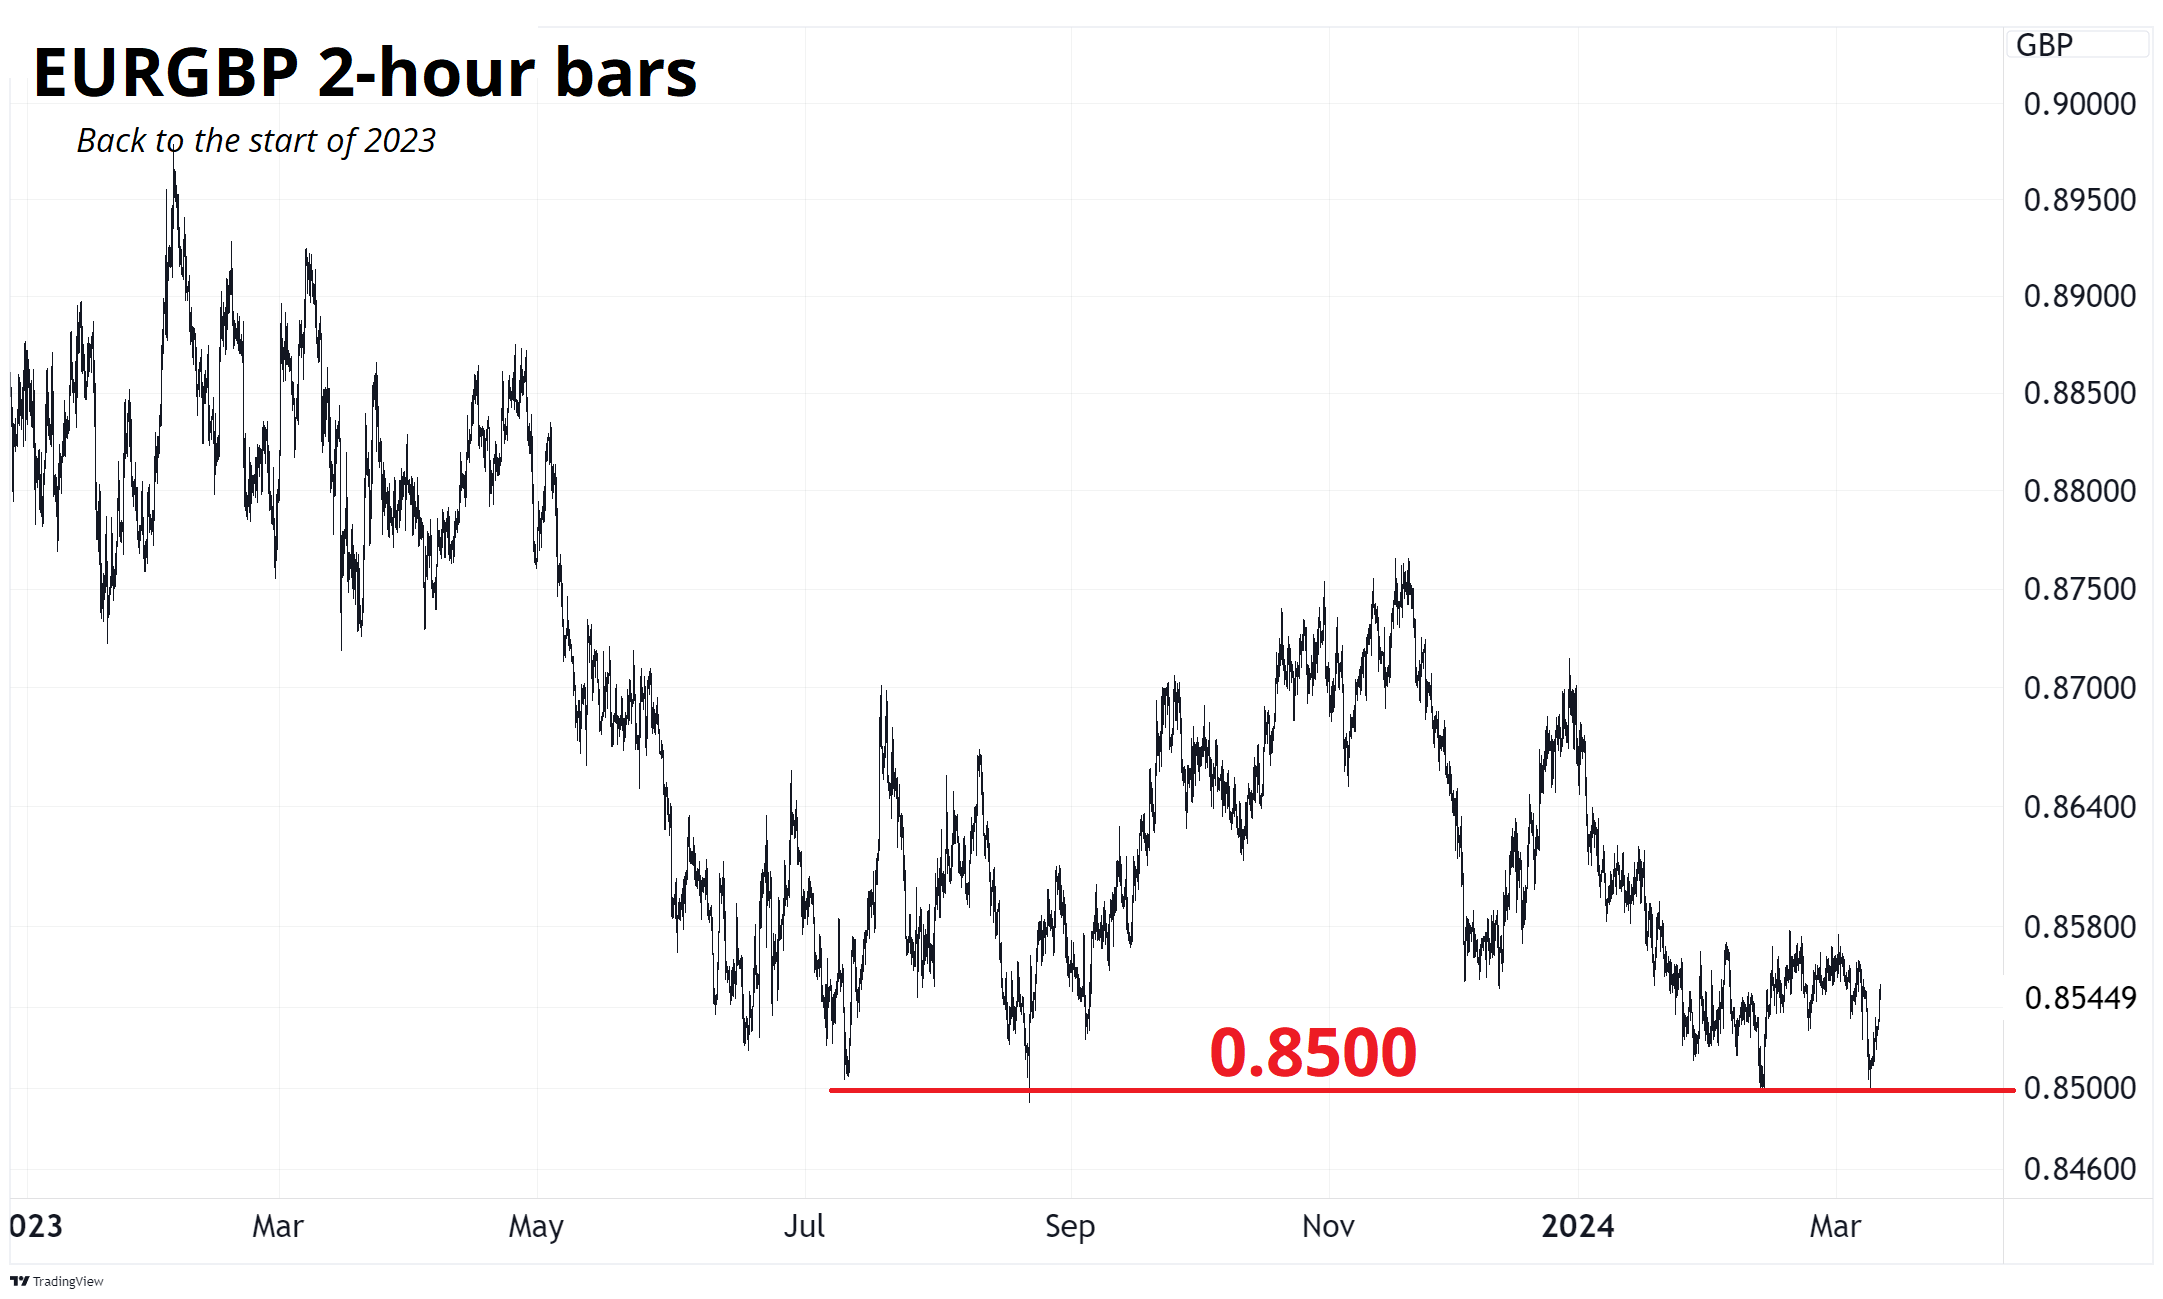
So, it’s a simple thesis: Economic momentum, rate differentials, positioning, and a lovely chart. Long here (0.8552) with a stop loss at 0.8479 looking for 0.8694. Risking 71 to make 144.
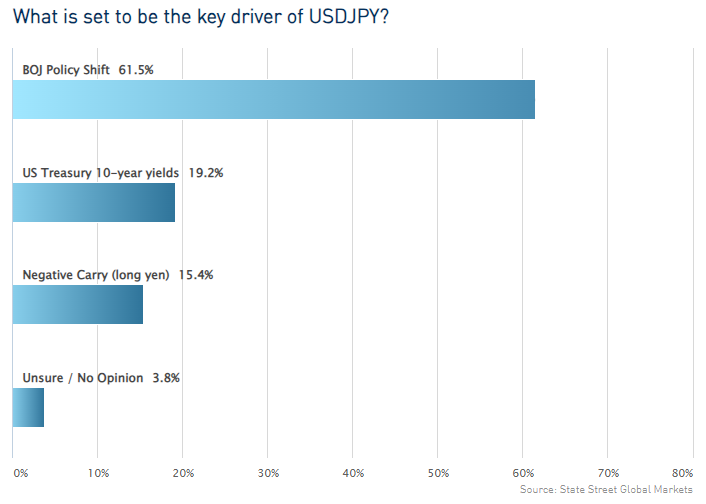
CPI as expected, or close enough. Doesn’t change much. This survey from State Street is interesting. I could not disagree more strongly, but I’m trying to keep an open mind. My vote is that US 10-year yields are the dominant driver going forward. But wages are roofing in Japan, it looks like, so perhaps some kind of proper normalization is possible and this is more than a story of baby steps? Imagine if JPY became a normal currency with actual yields that go up and down. That would be a huge paradigm shift. Open mind is good.
Interesting snippet from Chuck:
“60% Of Office Vacancies Concentrated In 10% Of Buildings: JLL” (full story from bisnow.com). That headline stat is a very moderating one for CRE bearishness. A small pool of underperforming office buildings is bearing the brunt of lost occupancy and dragging down absorption data, according to a new analysis by JLL.
Despite record levels of overall negative net absorption, only 12.7% of offices reported negative absorption, JLL said. That is the lowest proportion since the third quarter of 2017 and below the average of 14.4% over the last 20 years. “One of the interesting paradoxes of the office market over the past few years is that there has been record occupancy loss, but the share of buildings experiencing the ‘down market’ is small,” Jacob Rowden, research manager of U.S. offices, told Bisnow. “The vacancy increases in that segment of the market have just been especially intense.”
Over 60% of office vacancy is centralized in 10% of buildings, with 39% of buildings having no vacant space, according to the brokerage.
I hope your teenage angst has paid off well.
Tentative USD shorts are building
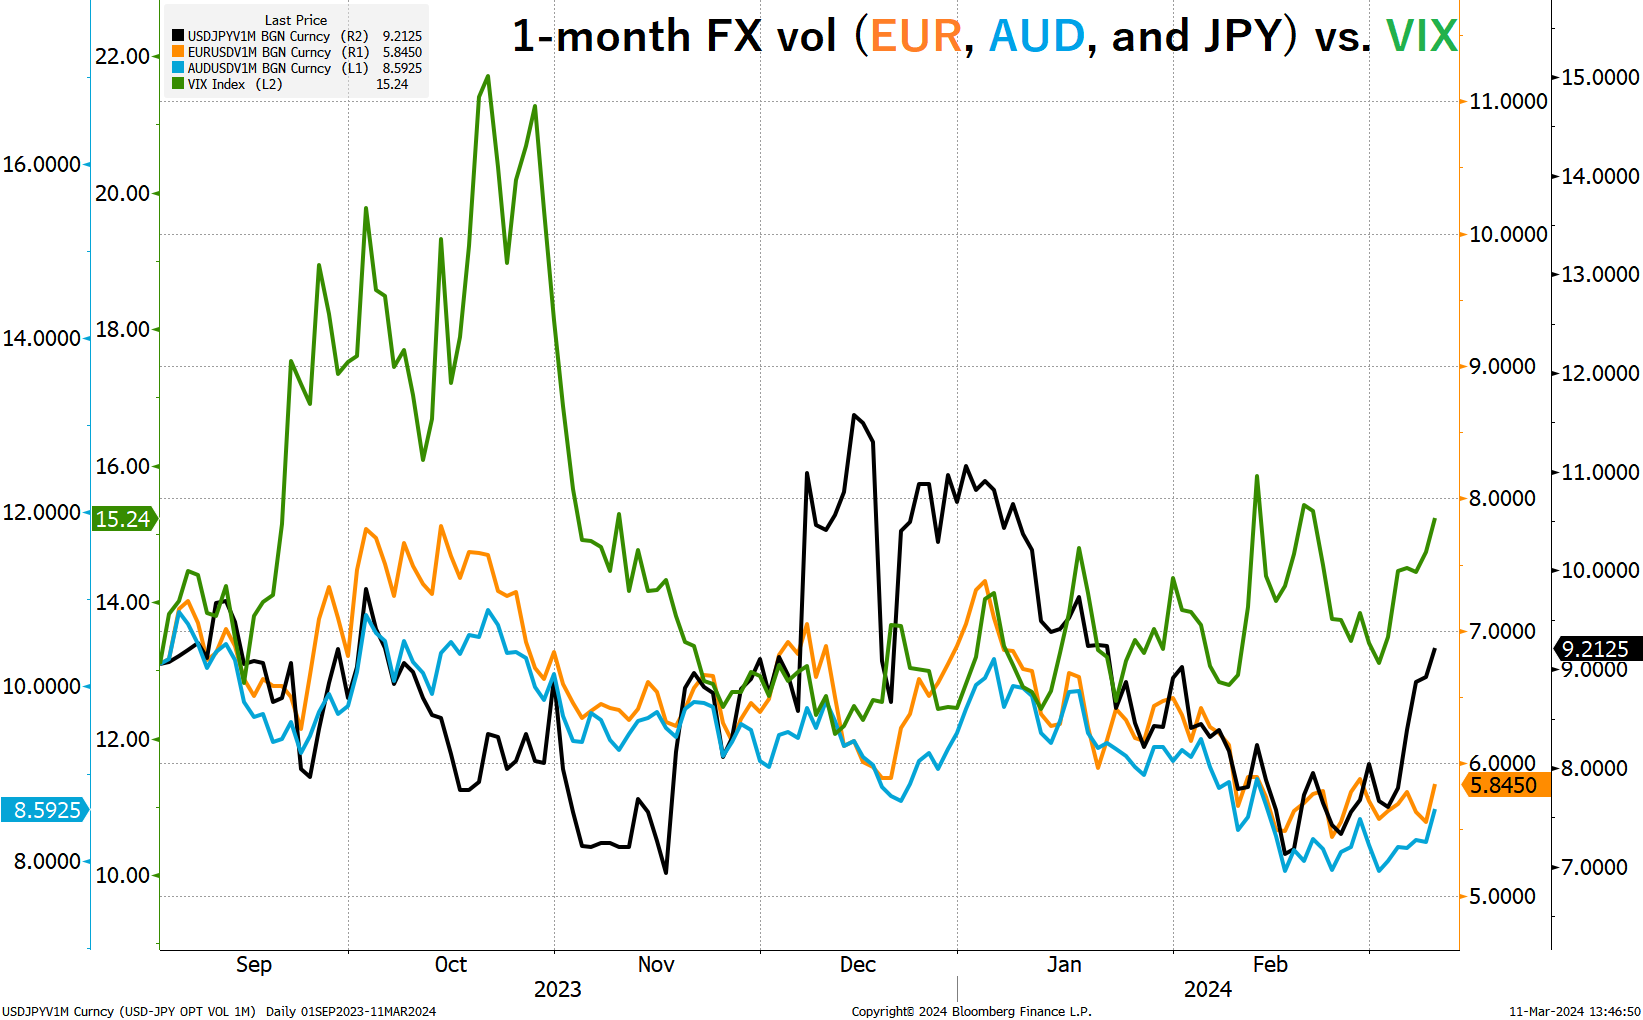
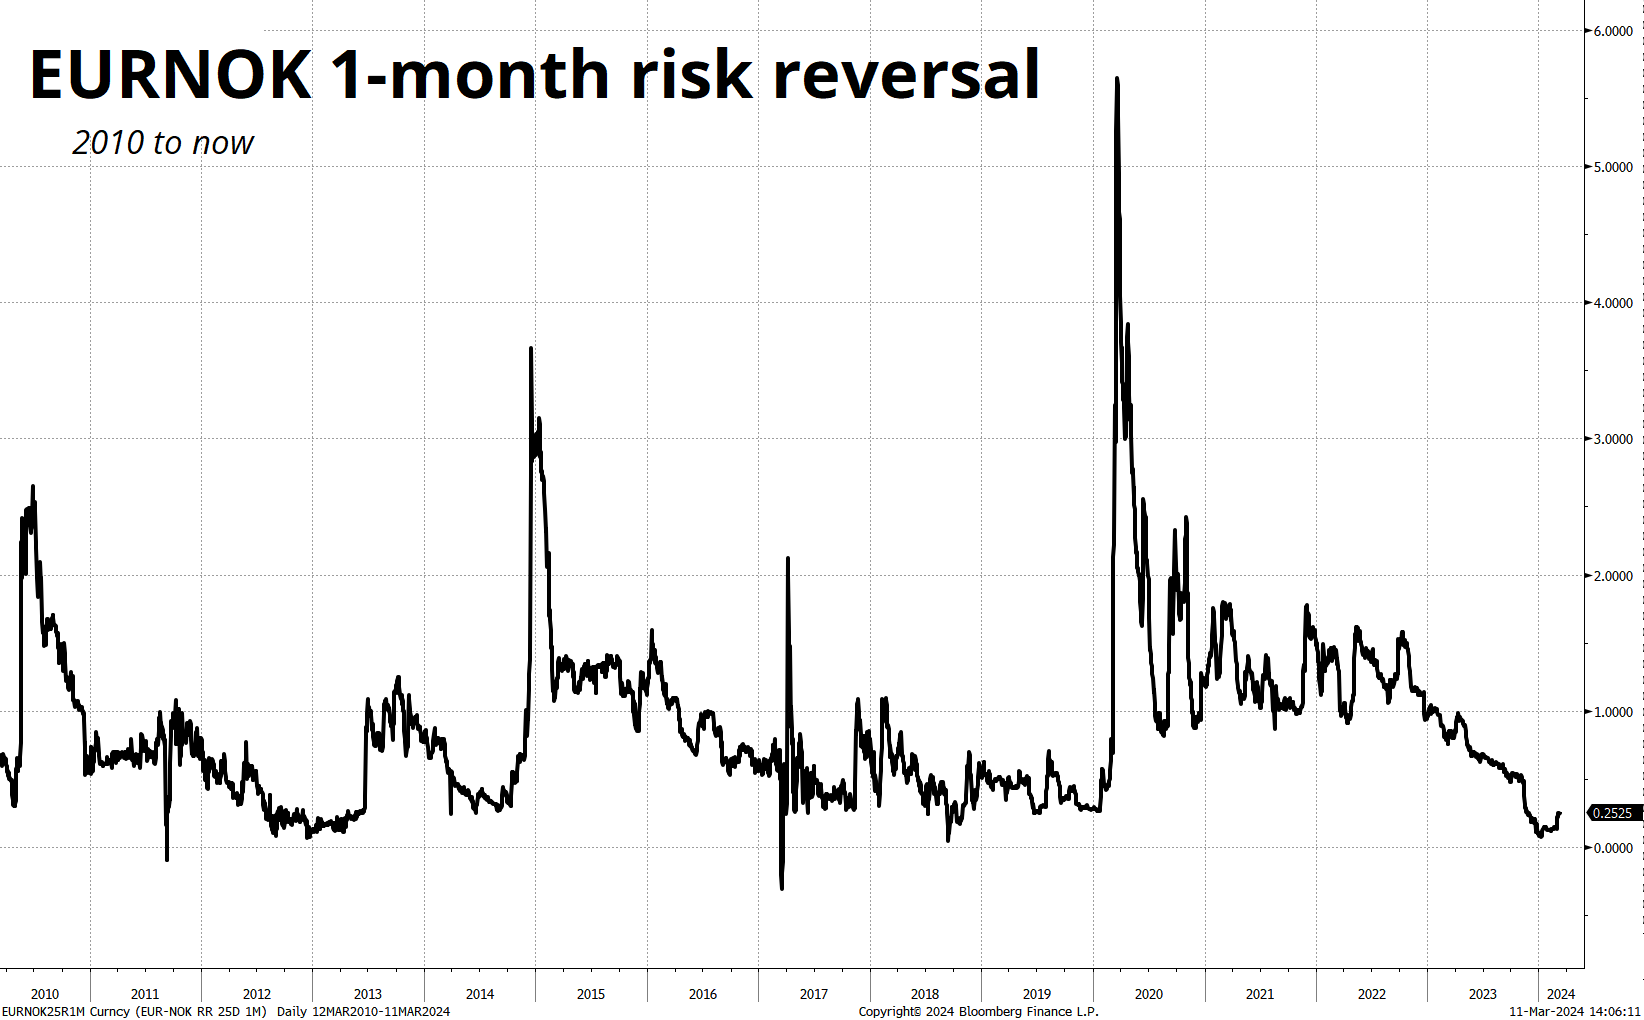
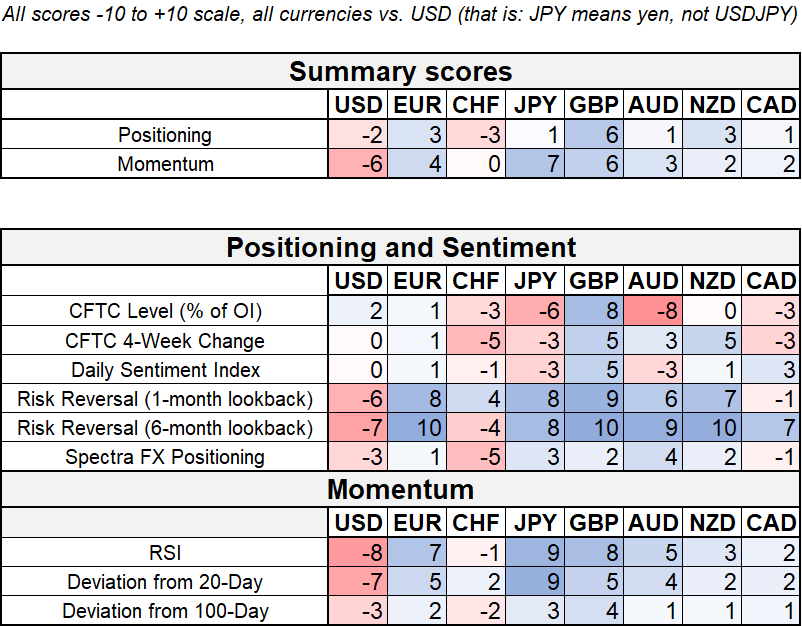
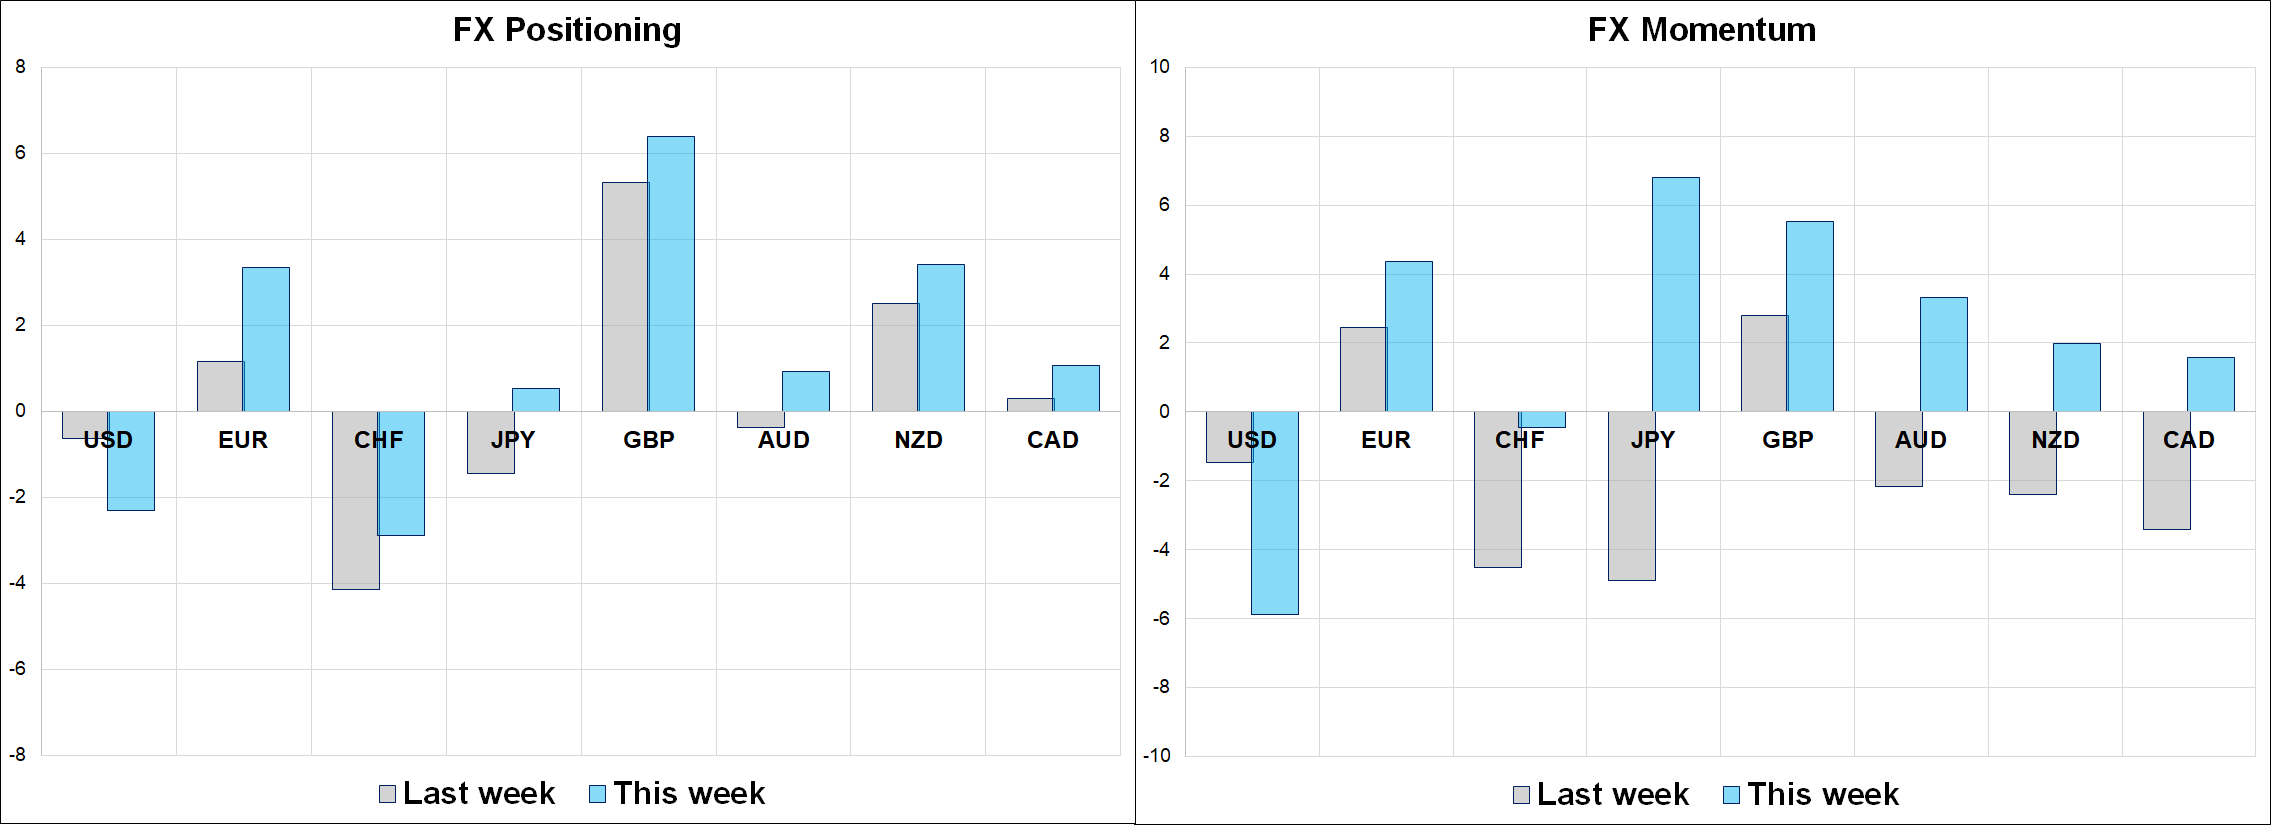
Hi. Welcome to this week’s report. While equity volatility has picked up, FX vol remains low in most pairs, with the exception of JPY. The market is gradually building a low-conviction USD short in response to falling yields and flying gold and BTC. The coming BOJ meeting has triggered a resurgence in interest for downside xxx/JPY structures as the market favorites (e.g., CHFJPY and CADJPY) have turned substantially lower. This week saw a huge momentum shift in the JPY as US yields slowly melt back towards 4% and the BOJ is in play once again.
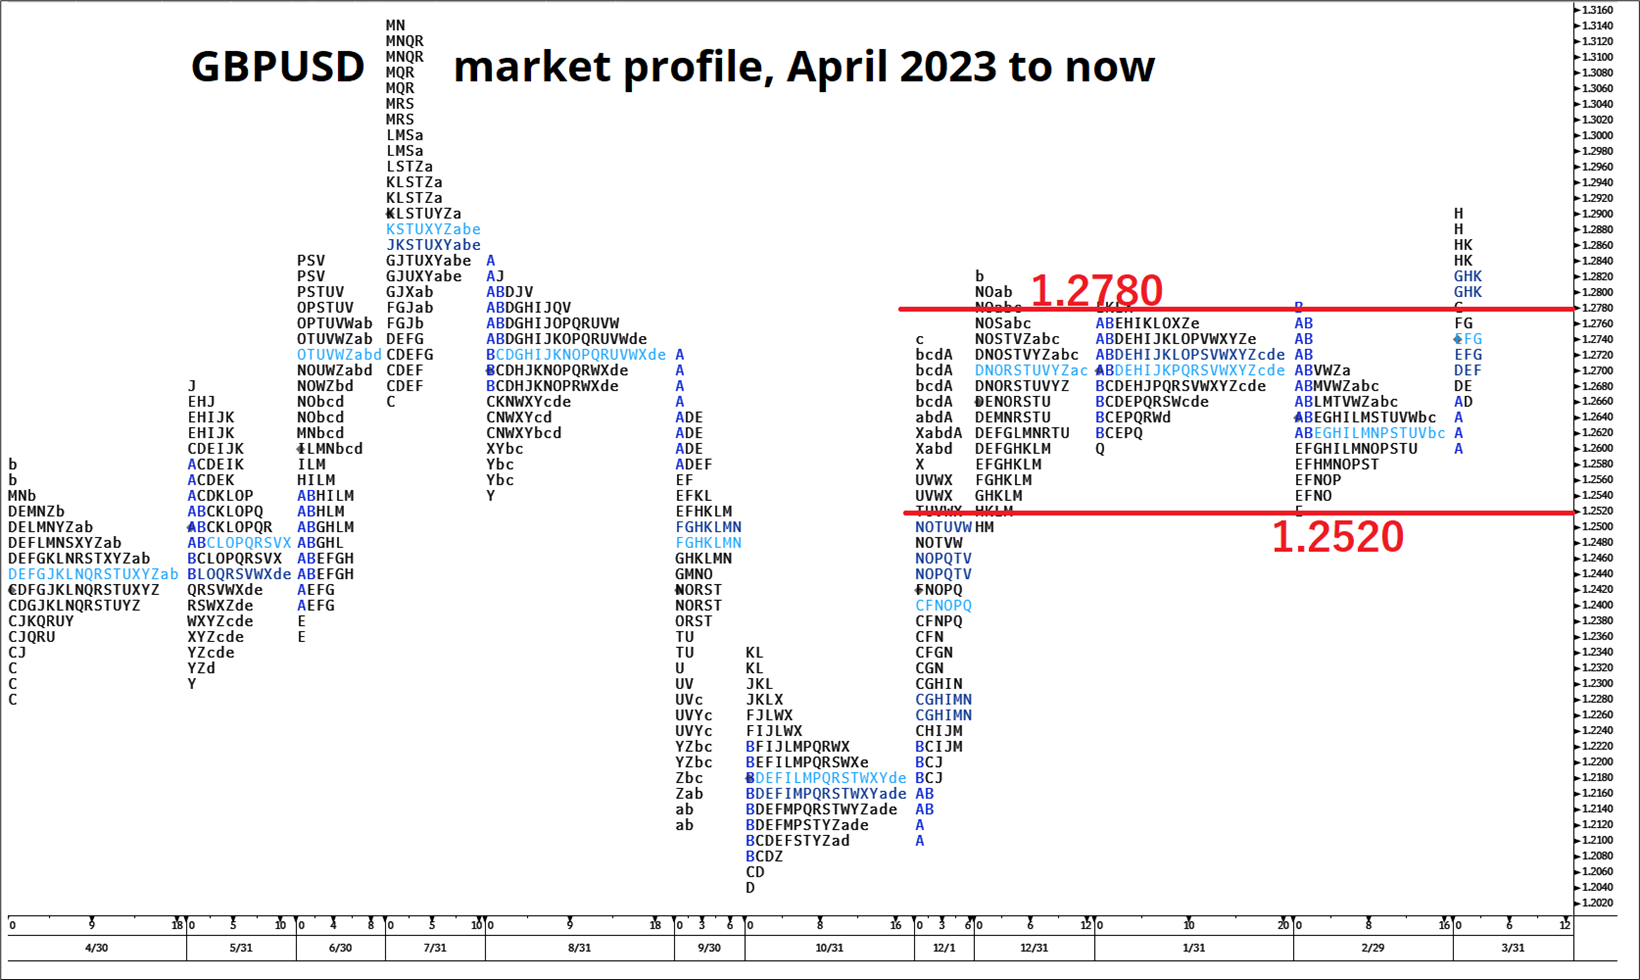
This would likely trigger a flush of late longs and invite a resumption of the 1.2520 / 1.2780 range trade.
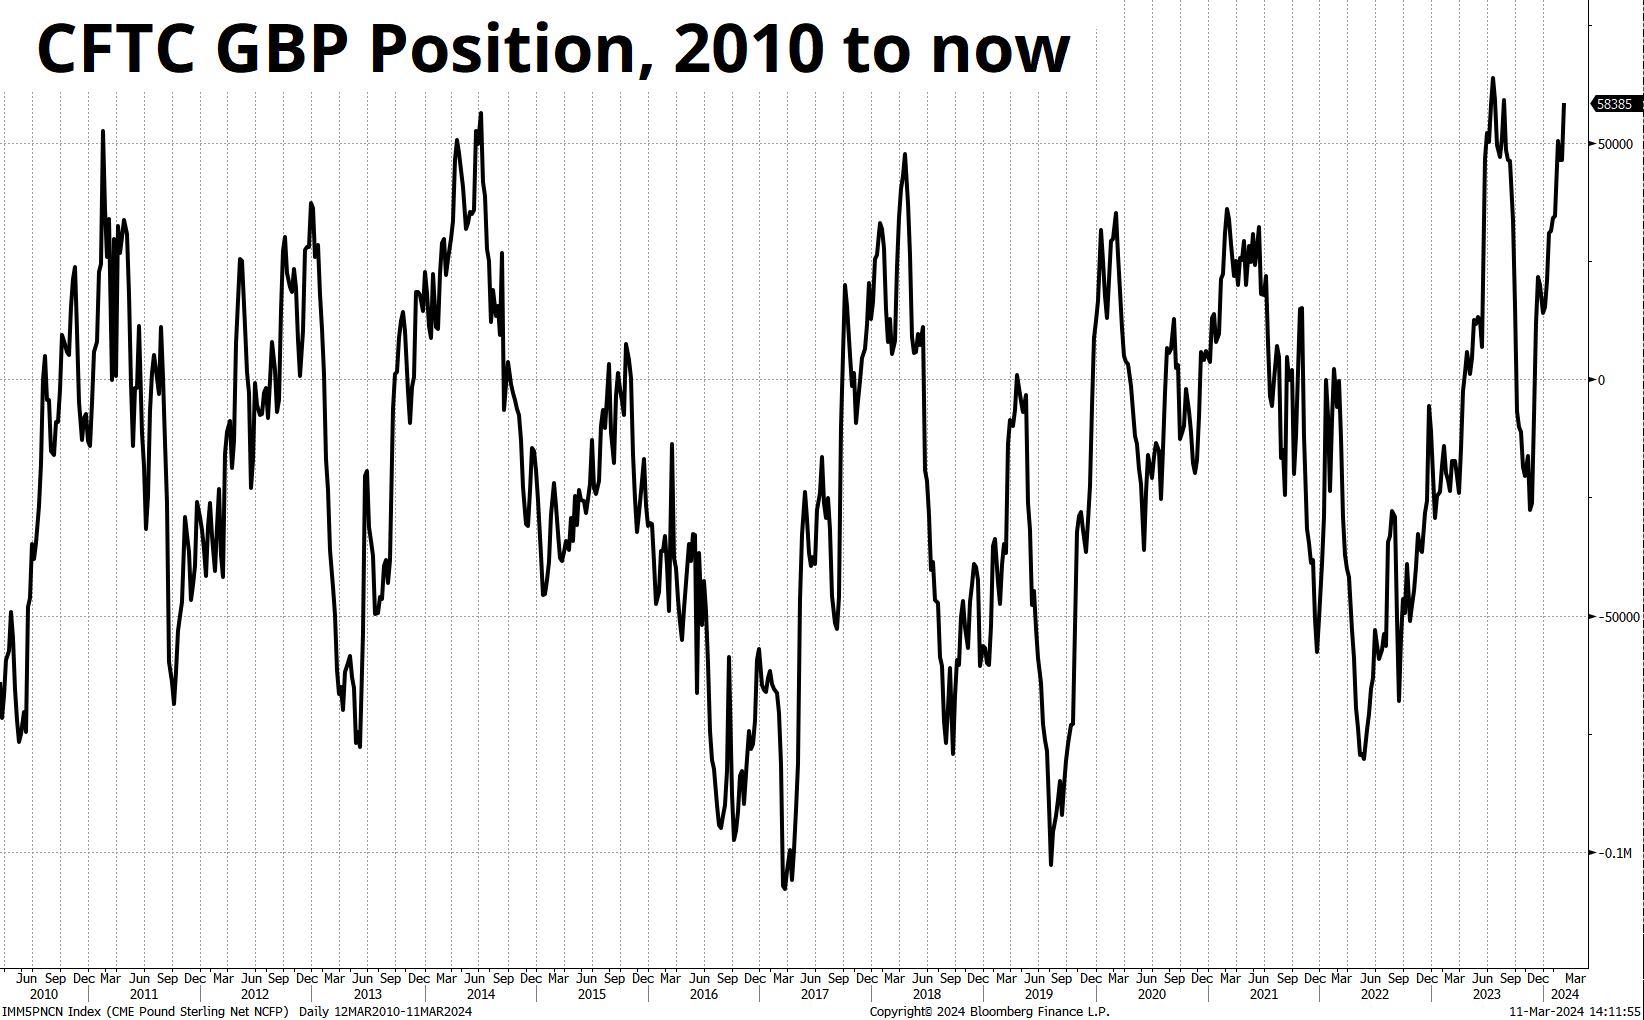
GBP has benefited from a weak USD environment and strong risk appetite. But if risk appetite is waning a bit (as suggested by the reversals in NVDA, Nikkei, and others), the USD is stabilizing, and there is no particular macro thesis to back up the rally in GBP… The rally looks suspect. That said, positioning has been long for a while and GBP has continued its grinding move up. This looks like up the escalator, down the elevator at some point.
Thanks for reading.
She’s overbored and self-assured


This piece is mostly for people who are interested in backtesting
This could be a consolidation week as crosswinds now blow in FX and equities
