Canada
I would keep a close eye on the Business Outlook Survey in Canada today. While the vibes have been bearish on Canada and many (including me) have been talking about the potential for a BoC cut in April (maybe) or June (probably)… GDP data for January (released last week) came in much stronger than expected and while one data point does not make a trend, it’s worth keeping an open mind just in case it is the start of one. We have had this slow bleed of bad, but not horrendous data in Canada, so a turn toward sunnier vibes might catch the market off guard.
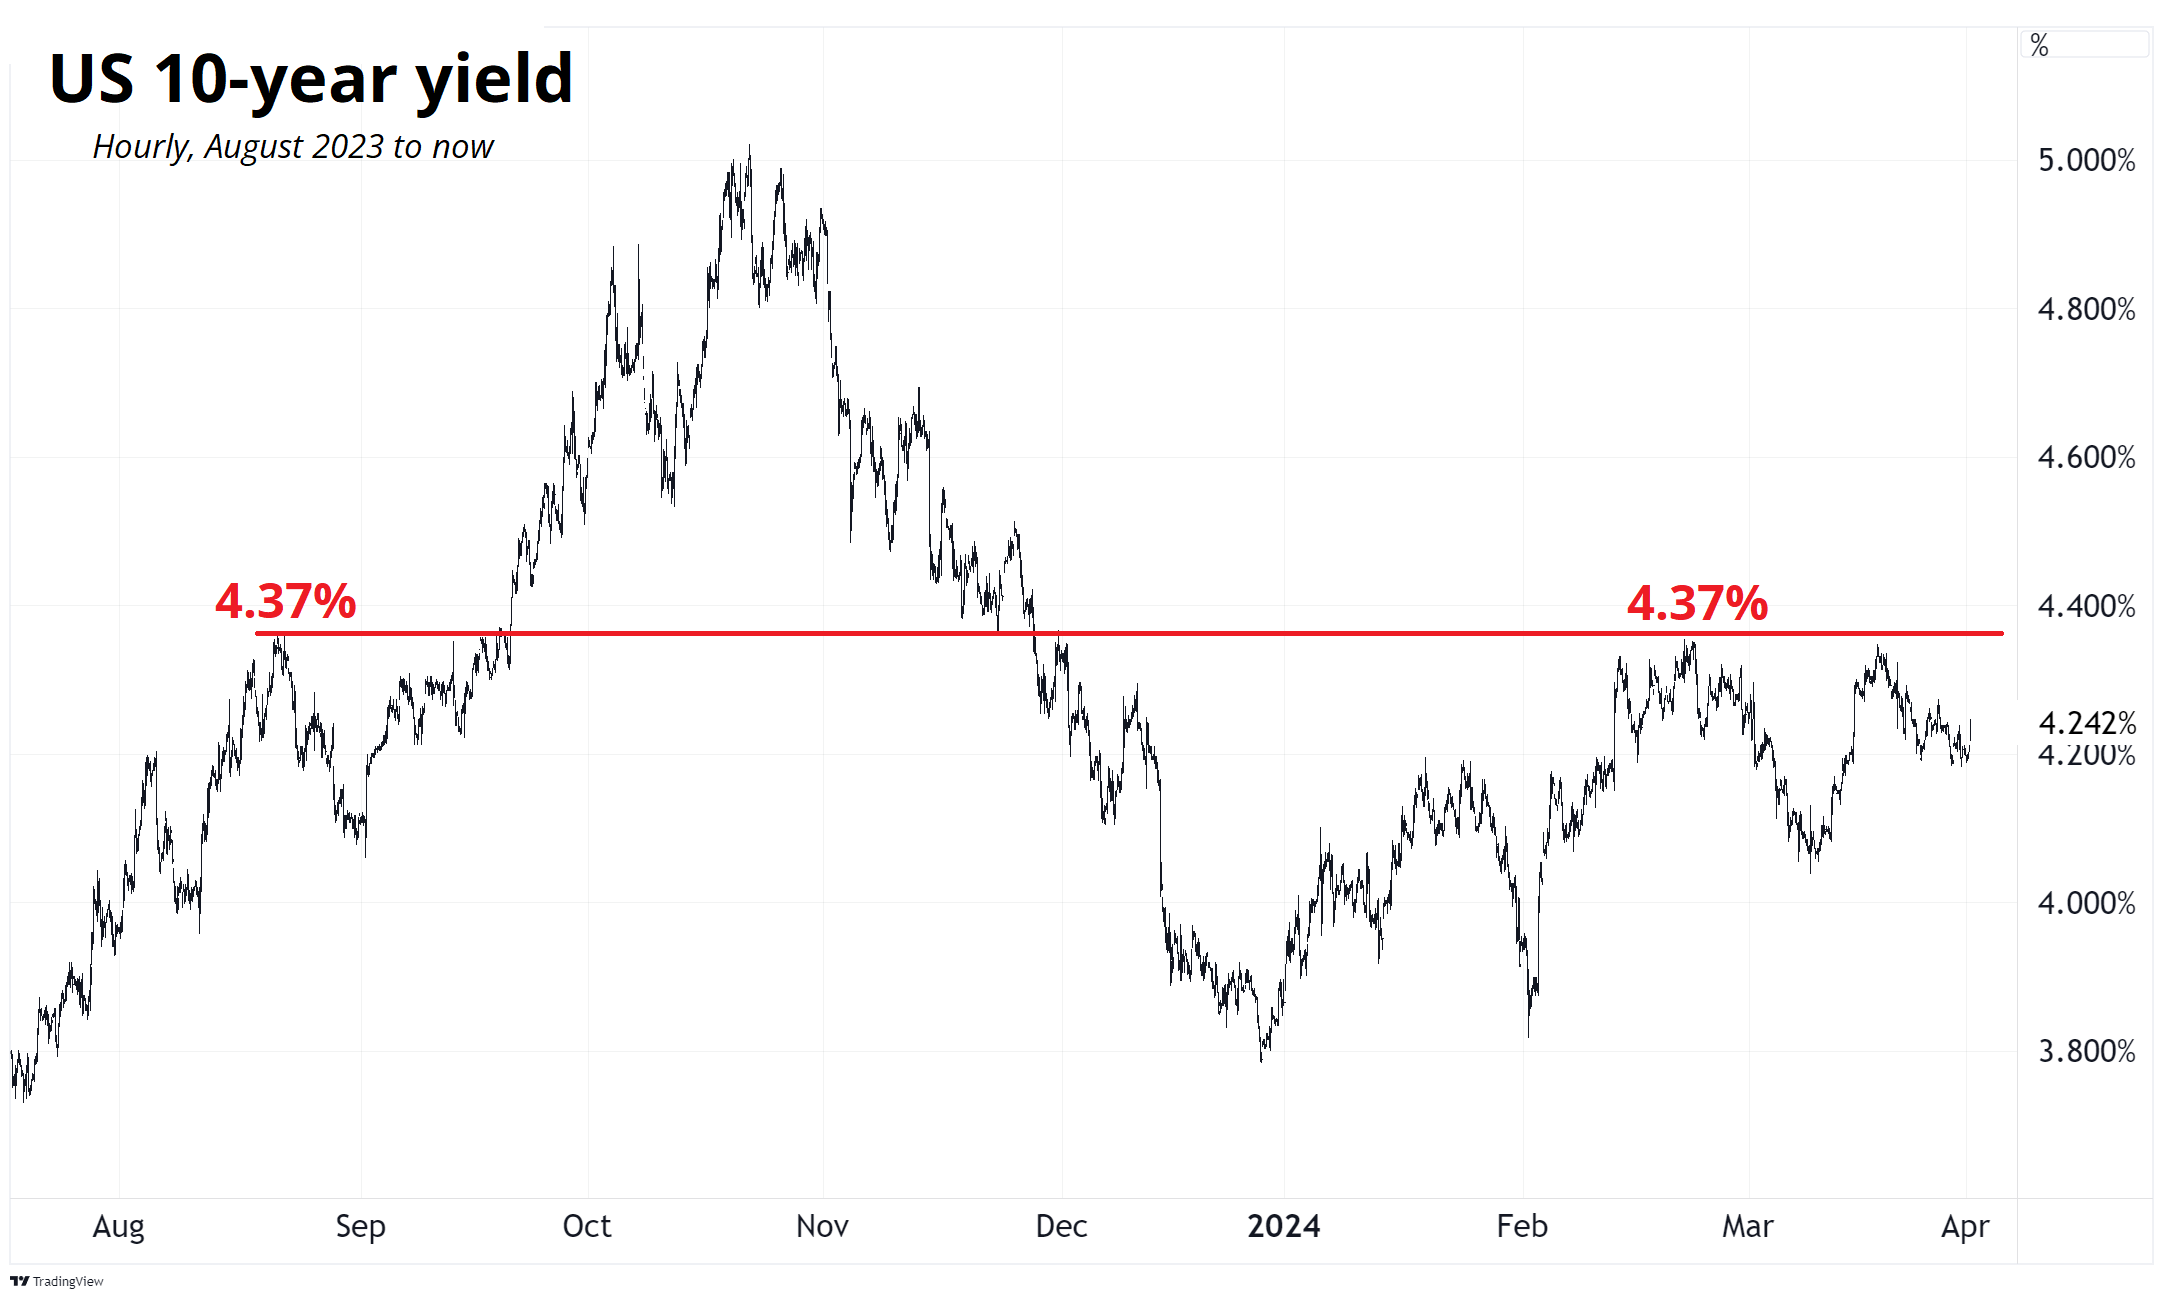
US 10-year yield
I have been writing a fair bit about how the collapse in fixed income volatility is one of the major drivers of risky asset joy. What might reintroduce more rates vol? Chart-wise, I think if we take out 4.37%, we could see a reinvigoration of vol as that level has been a critical pivot both before the shot to 5% and after. You can see in this chart that the action over the last year has been split fairly nicely into two regimes. The panic and reversal that took place as we shot to 5% and then Yellen put out the fire. And the subsequent 3.80%/4.37% range trade. In both regimes, 4.37% served as a significant reference point.
I don’t think there is any Fed banter that could get us up and through there; it would require another run of strong data. We get ISM and NFP this week, and those could be a start, but evidence that commodity price inflation is flowing through to services and housing would be the ultimate way we get a true reacceleration higher in the 10-year yield.
Trades
I have taken the “buy the dip” idea in USDJPY out of the sidebar. It’s getting late in the bullish seasonal period for the pair, and we have simply consolidated in a boring range ahead of the critical 152 level. The MOF has put itself in a bit of a tricky position where 152 has become a line in the sand, somewhat. Soon, they will have to decide what to do. My best guess is that they will let it go through but will then come in and intervene before 155 trades in order to maintain credibility and avoid an aggressive and impulsive topside overshoot.
While the EURGBP long trade is incredibly boring and very slightly negative carry, I still like it. Rate diffs are still pointing towards 0.8700, and I think it was month-end GBP buying that knocked EURGBP back down to my entry point. The strong base continues to form 0.8500/0.8530.
Calendar
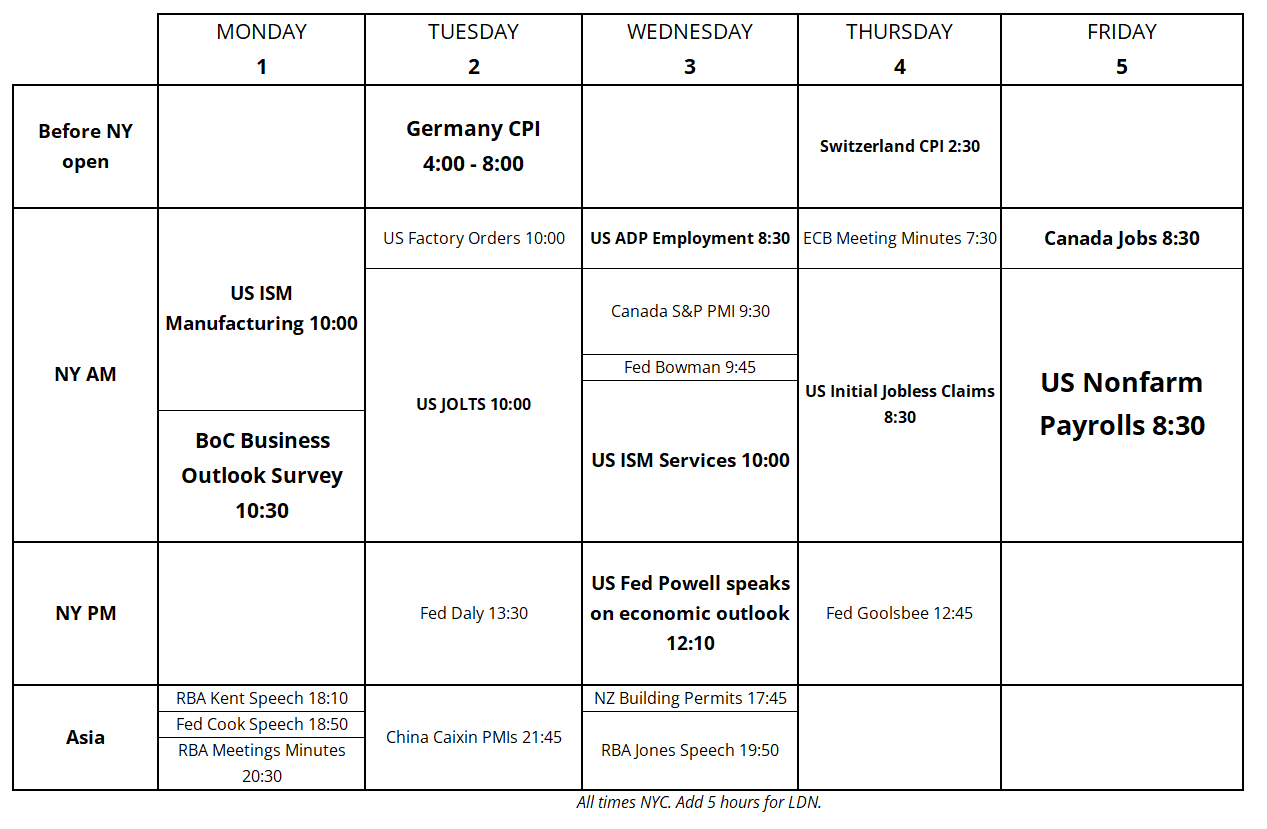
We have the usual first week of the month events this week, with ISM, The BoC Business Outlook Survey, German and Swiss CPI, and the US and Canadian jobs reports as highlights. There are also about 765 Fed speeches, though I have only highlighted a few majors here. Powell is on the docket yet again, as the Fed continues to overcommunicate in a time when so much communication adds nothing but sometimes subtracts or distracts from the overall message.
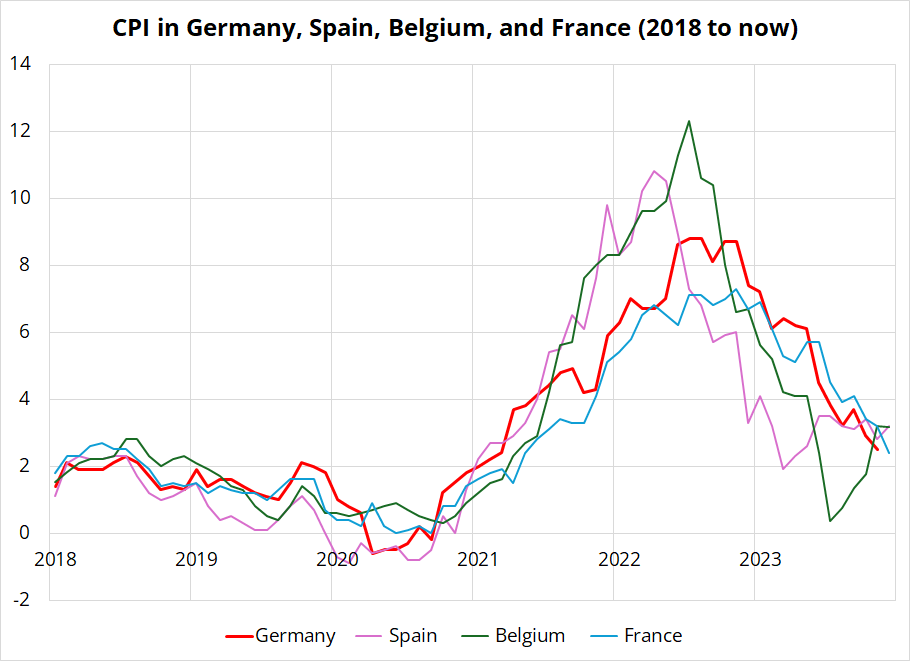
After last week’s soft CPI print in France, one might be inclined to lean towards a weak German CPI number tomorrow, but my analysis suggests it’s a mixed bag. Readings have come out in Spain and Belgium which suggest a possible bottoming in Eurozone inflation and therefore I think German CPI looks like either a coin toss or perhaps even a small asymmetry towards a stronger number as the market has been prepped for weakness by the French release. Here is German CPI in red, with three neighbors shown. You can see the cyan line is France making new lows while the purple line shows Spain bottomed last June and the green line shows Belgian inflation bottomed in October and has bounced off super low levels.
The market narrative leans strongly in the direction of European disinflation. A figure that corroborates that narrative would not be as interesting as one that does not. Don’t forget that the individual state CPIs for Germany start coming out at 4 a.m. NY time, so when the national data is released at 8 a.m., it’s old news. You can easily create a spreadsheet that calculates the national data using the state-level data and therefore by 6 a.m. or so, we have a good idea of what’s coming out at 8 a.m.
Final Thoughts
From Morningstar: Trump Media is not a meme stock. It’s a cryptocurrency. I think this article is interesting in the context of people talking about the company’s financials and valuation, etc. There is no valuation story here, it’s simply a question of when people with affinity for the DJT ticker get bored and all decide to sell at the same time. The terminal value is zero but that doesn’t mean it can’t go to infinity first.
Have a hawkish week.