

The Fed’s acknowledgement that higher real and long yields are tightening financial conditions should lock the front end and lead to lower fixed income vol and a recovery in EMFX.
Peak FI Vol?
Subscriber-only
BD
by Brent Donnelly
Current Views
Long 2-month EURMXN
18.70/18.20 put spread
~50bps EUR
off 19.16 spot
Go short USDJPY at 150.09 (limit order)
Stop loss 152.26
Take profit 146.57
October 10, 2023
Equities, Fixed Income
Before we get started, here’s this week’s calendar. Thursday the highlight with CPI on the docket.
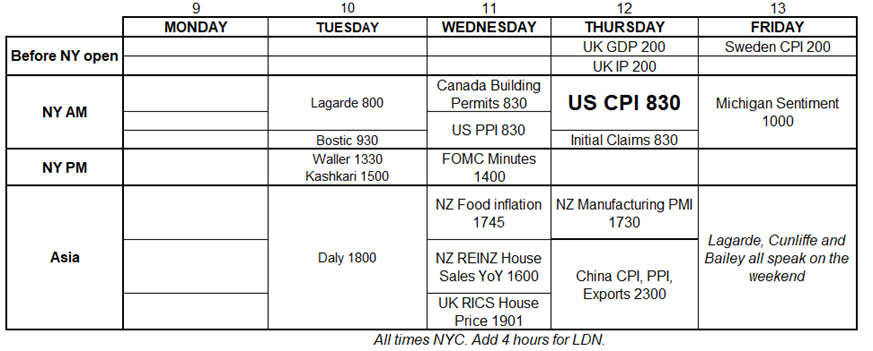
CPI will be interesting, as we will get to see if stocks can go 3-for-3 rallying on bad news after a strong NFP and the violence in the Middle East both clearly showed a huge imbalance between buyers and sellers.
NASDAQ futures, September 5 to now
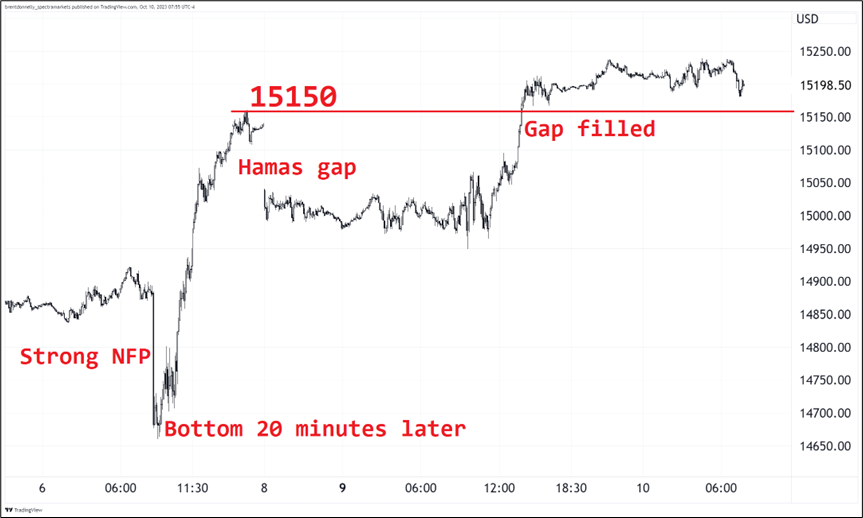
While 14500/14600 is the real level in NASDAQ futures, the 15150 level is now a short-term level to watch as we have twice rejected aggressive selling and have entered the bullish seasonal period that runs through to the second week of December.
At this point, maybe equity bears are praying for a weak US CPI given the backwards reactions in markets after NFP and the weekend violence.
The weekend speeches from Fed Vice Chair Philip Jefferson and Lorie Logan, President of the Dallas Fed, both clearly tell us that the rise in real rates and longer-term US yields puts the Fed on pause for now. Nominal and real rates are both in restrictive territory by just about any measure. We are now in the higher-for-longer phase and the bar for additional Fed rate hikes is extremely high. November odds of a hike have moved down to 16%, and should dribble towards zero as the meeting date nears.
I always recommend that anyone who is serious about trading or macro read all the major Fed speeches, but in case you are pressed for time, here are the key excerpts. All bolding is mine.
From Jefferson:
As I mentioned earlier, real long-term Treasury yields have risen recently. In part, the upward movement in real yields may reflect investors’ assessment that the underlying momentum of the economy is stronger than previously recognized and, as a result, a restrictive stance of monetary policy may be needed for longer than previously thought in order to return inflation to 2 percent.
But I am also mindful that increases in real yields can arise from changes in investor’s attitudes toward risk and uncertainty. Looking ahead, I will remain cognizant of the tightening in financial conditions through higher bond yields and will keep that in mind as I assess the future path of policy. I will be taking financial market developments into account along with the totality of incoming data in assessing the economic outlook and the risks surrounding the outlook and in judging the appropriate future course of policy.
From Logan:
Financial conditions tightened substantially in recent months. Much of the tightening came from movements in longer-term interest rates. Higher long-term interest rates have also contributed to equity price declines and dollar appreciation over recent months. In the remainder of my remarks, I’ll discuss how I interpret the rate moves and what they might mean for monetary policy.
Since the July meeting, the yield curve has steepened notably. The market-implied peak fed funds rate is little changed, and policy-sensitive rates through 2025 are 60 basis points higher. But the 10-year Treasury yield is up roughly 90 basis points, and the five-year yield, five years forward, is almost 130 basis points higher.
Importantly, the rise in rates has come almost entirely in real interest rates. Inflation compensation has hardly moved. Market participants remain confident, as they should, that the FOMC will achieve the inflation target.
Putting together analytic estimates with the information I have gathered through these channels, I see a mixed story. There is a clear role for increased term premiums in recent yield curve moves. But the size and persistence of the contribution are subject to uncertainty.
Financial conditions have tightened notably in recent months. But the reasons for the tightening matter. If long-term interest rates remain elevated because of higher term premiums, there may be less need to raise the fed funds rate. However, to the extent that strength in the economy is behind the increase in long-term interest rates, the FOMC may need to do more. So, I will be carefully evaluating both economic and financial developments to assess the extent of additional policy firming that may be appropriate to deliver on the FOMC’s mandate.
All other things being equal, higher back end yields now mean less Fed tightening as the official perception is now that high real and nominal market rates will apply more restrictive pressure on top of an already-restrictive Fed Funds rate. This is probably bearish fixed income vol as the front end is now locked for a while and this should anchor the back end somewhat.
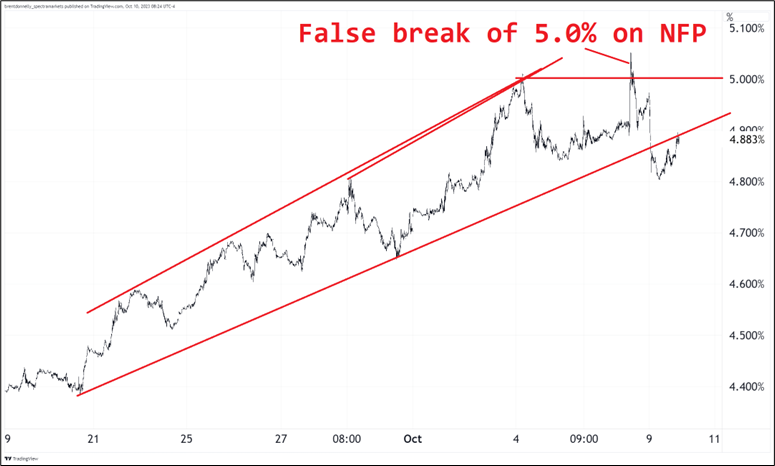
The failure of 30-year yields to hold above 5.00% on the strong data is another sign that peak fixed income vol and probably peak yields have been reached for now.
I continue to think stocks go higher into yearend as they benefit from stabilization in fixed income, oversold conditions and positive seasonality. This does not require yields to go down, it just requires them to stop going up.
US 30-year yield, hourly early September to now
Stable fixed income, higher stocks, and lower volatility should work to stop the rot in EMFX. Here is VIX vs. EURMXN.
EURMXN (black bars) vs. VIX
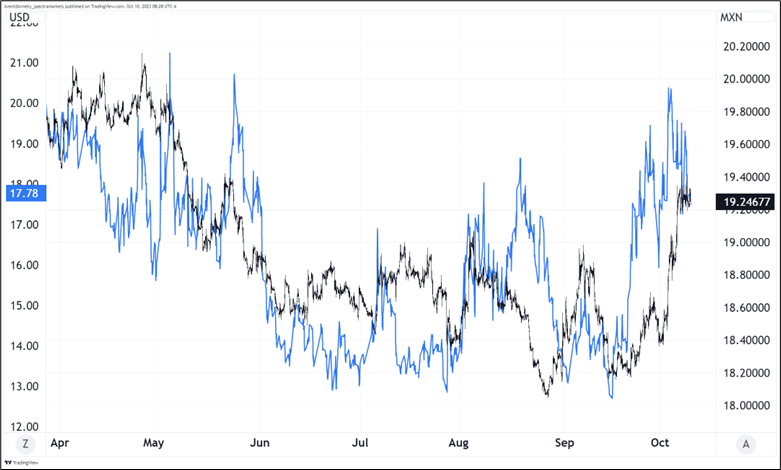
The 2-month forward in EURMXN is 19.49 and spot is around 19.24, so that obviously gives you a nice head start. I’m adding a 2-month put spread in EURMXN to the sidebar. 18.70/18.20 strikes for a cost of about ~50bps EUR (price is ballpark off 19.21 spot, please ask your friendly salesperson for a live quote). Risking 50 to make 260.
I believe the macro setup will be carry-friendly into year end as lower fixed income vol leads vol lower across the board, and the positioning has been sufficiently blown up in MXN. The US continues to plug along and reshoring is still relevant at the margin so the MXN positives are still there, despite the huge wipeout in positions. A scary and obvious risk is that Iran gets involved in the Middle East. I don’t feel that’s something I can handicap very well. At least the put spread gives you staying power if a bunch of scary headlines hit.
Final Thoughts
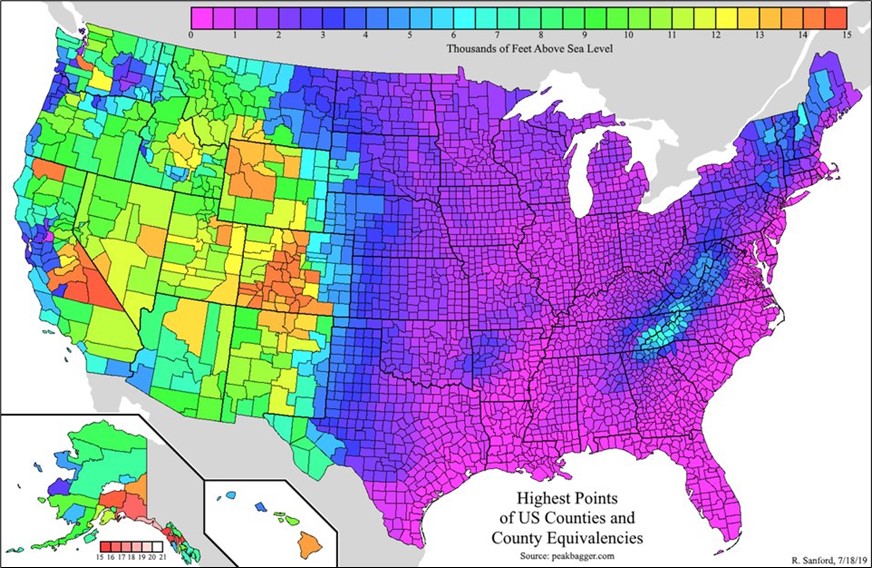
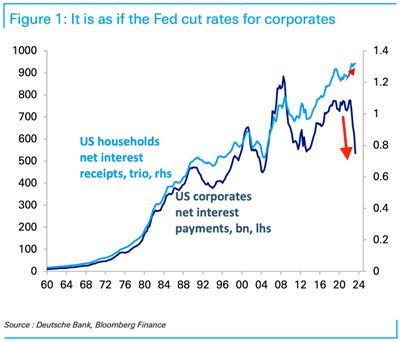
Cool chart from DB.
Have a colorful day.
good luck ⇅ be nimble
https://twitter.com/Amazing_Maps/status/1444467238166220803/photo/1
Highest point in each US county. Nicely-executed visual!
Click here to subscribe to am/FX
More recent posts




Rabbit Holes
CAD and Rabbit Hole #18
This piece is mostly for people who are interested in backtesting