
The ECB cuts are slowwwwly getting priced out. This is good for EURUSD.
Where does the expression:
“The cut of his jib”
Come from?

The ECB cuts are slowwwwly getting priced out. This is good for EURUSD.

Where does the expression:
“The cut of his jib”
Come from?
Long EURUSD 1.0870 or better
if both US PMIs below expectations
Stop loss 1.0789
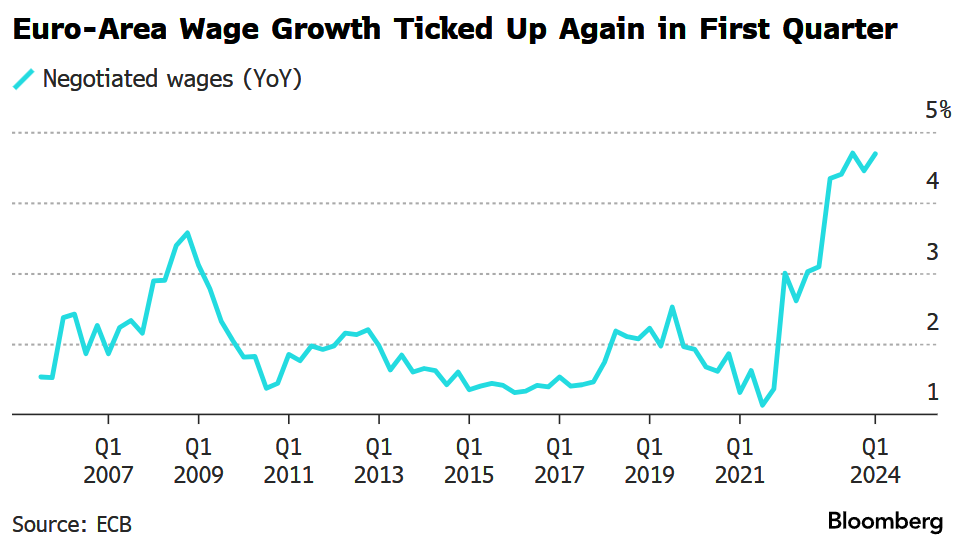
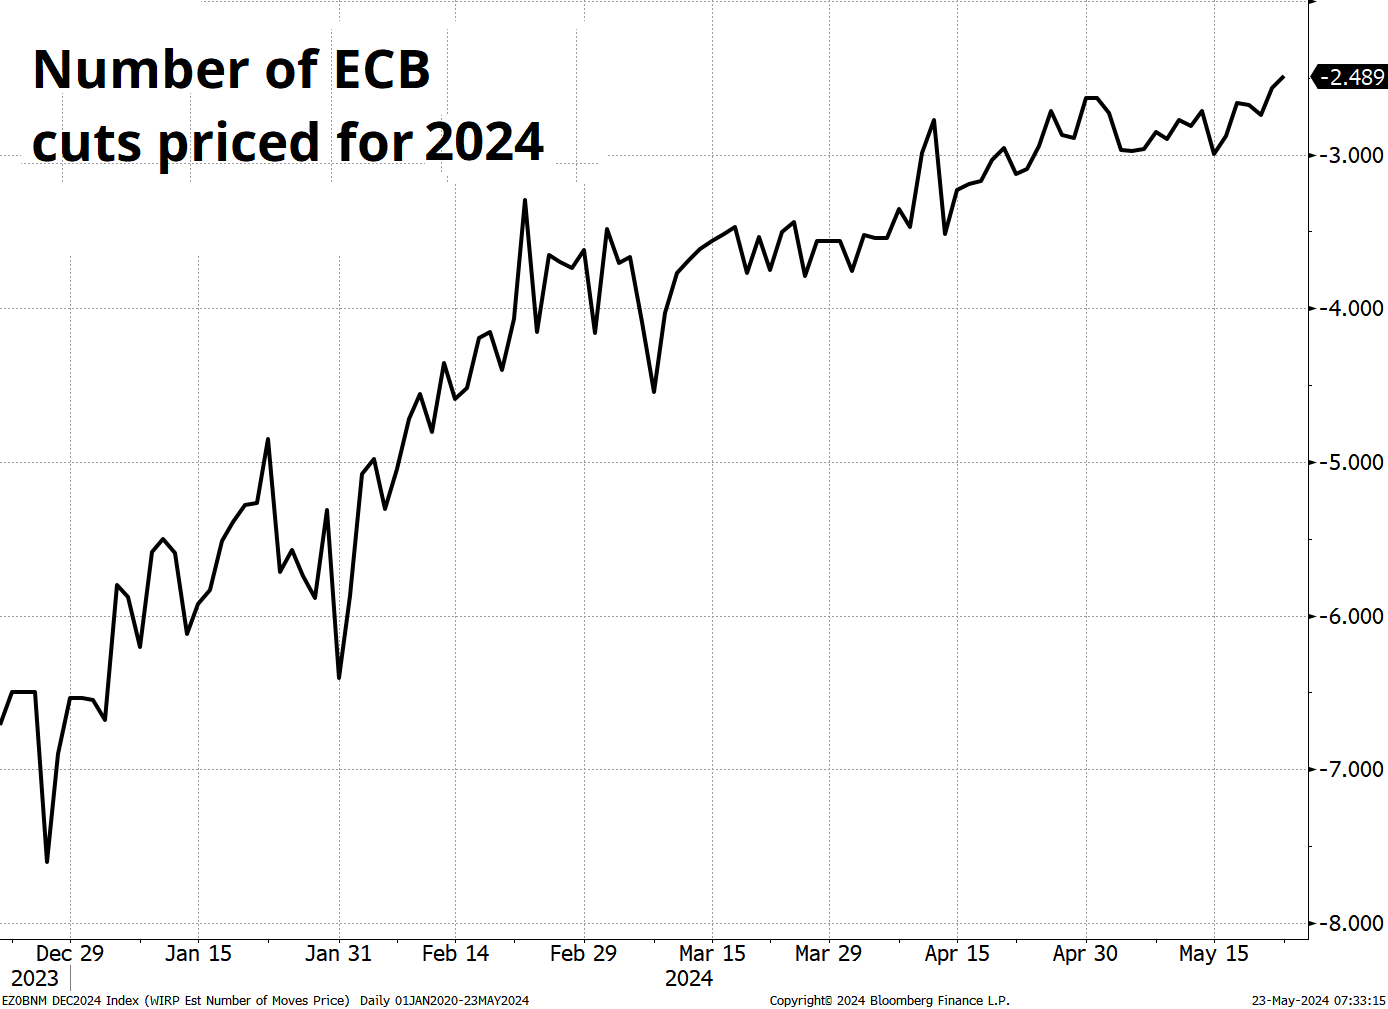
Europe is reconverging with the US with total ECB cuts priced for December 2024 having travelled from >6 in January to 2.45 cuts priced now. While June 6 is locked in, ECB language has been saying anything is possible after that cut. Wage growth and PMIs (and commodity inflation) not screaming for more cuts.
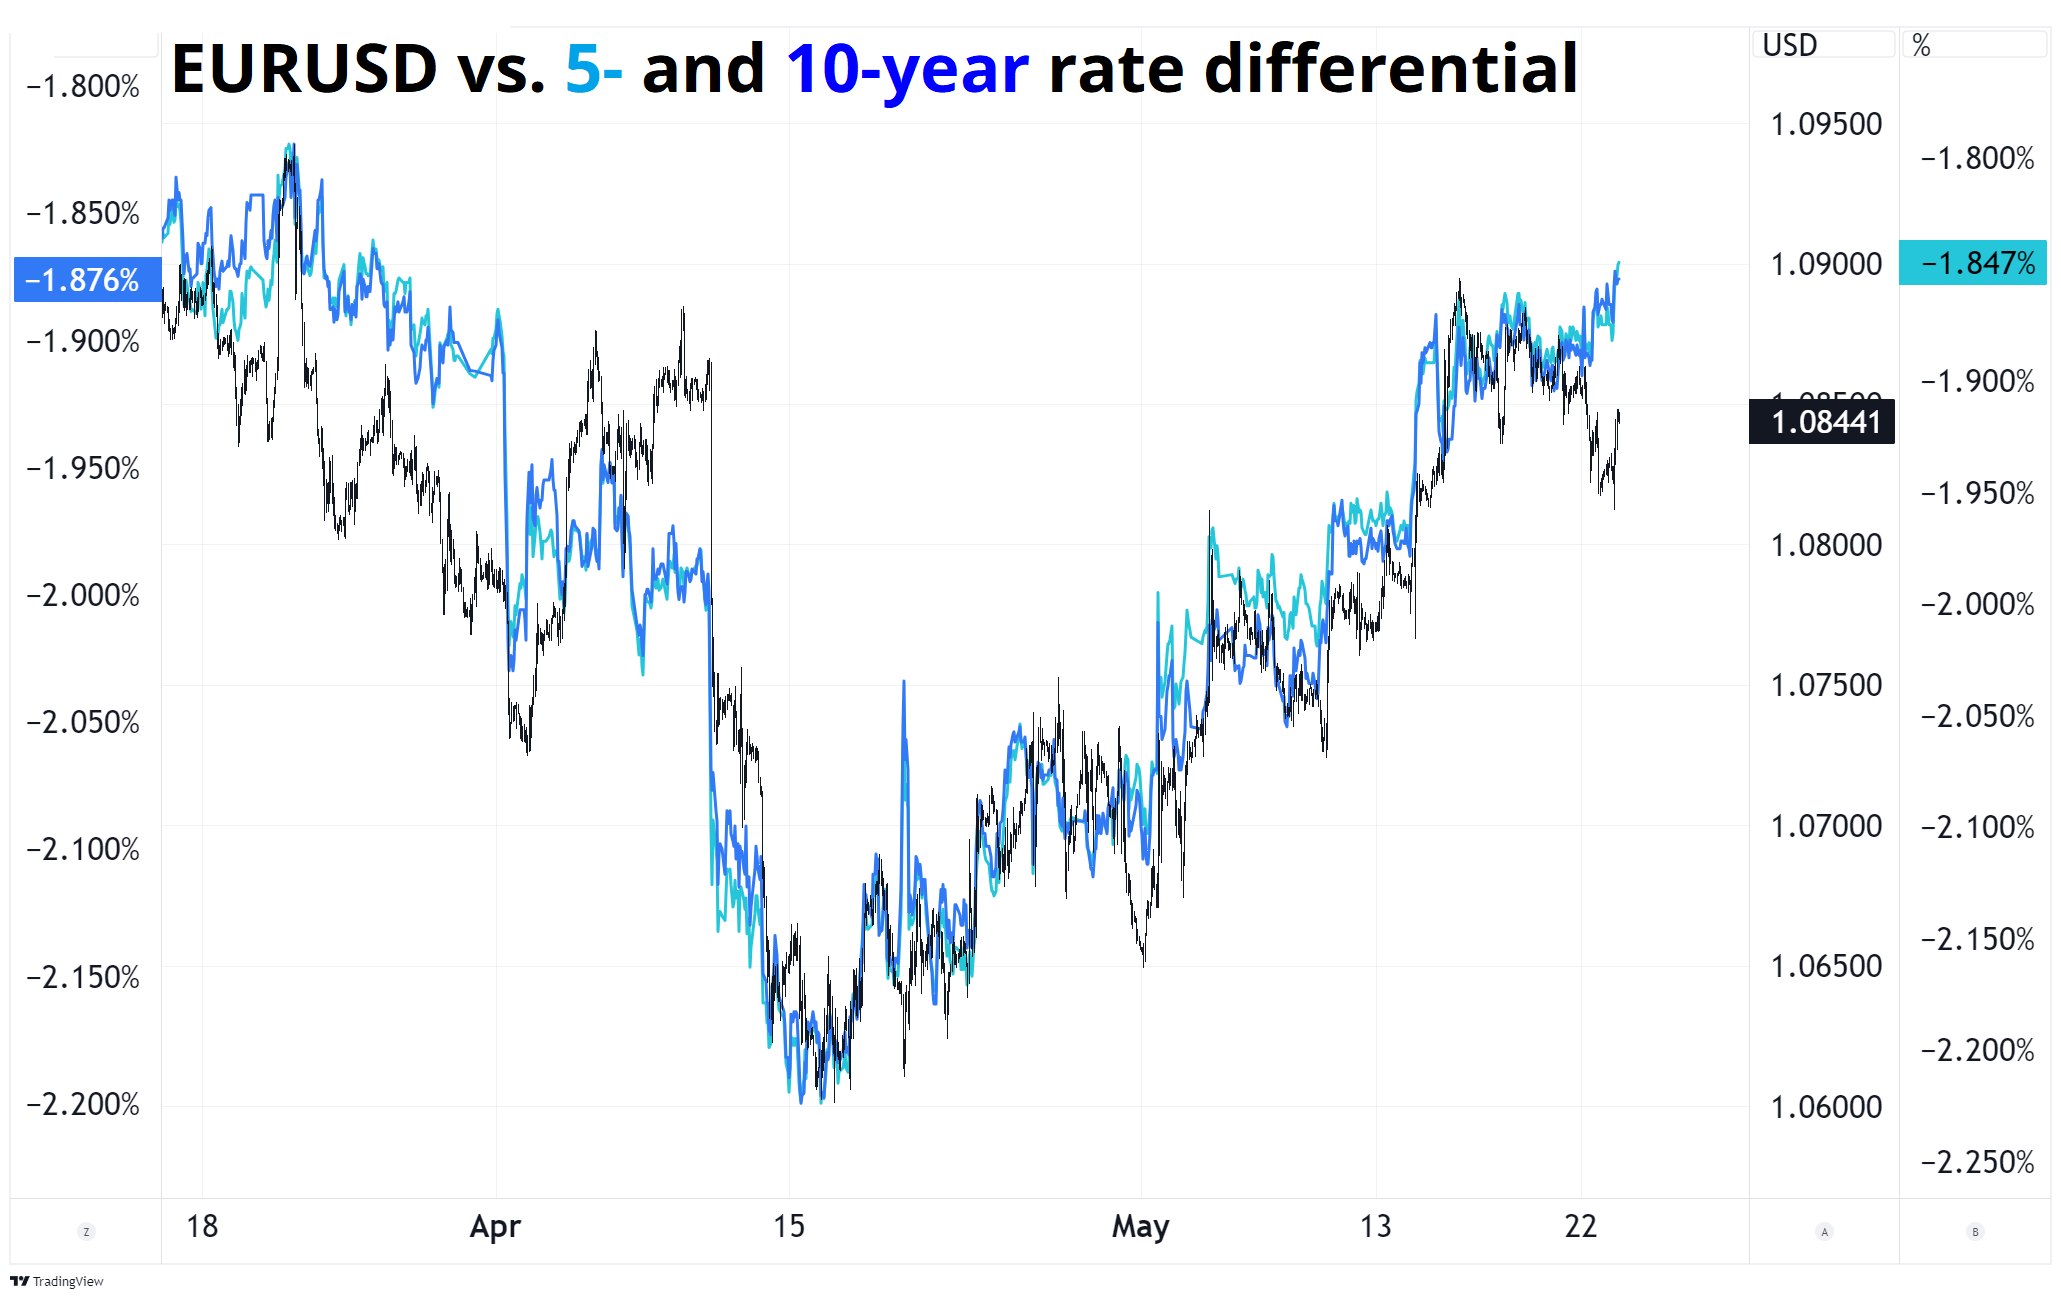
The rate diffs chart I post here shows 5 and 10-year differential has contracted enough to suggest 1.09 or maybe a bit higher.
Hard to act immediately on this with S&P PMI in the US today. But if those PMIs are low, and you can get EURUSD sub 1.0870 – that’s probably a good trade as the EU/USA divergence trade fizzles.
The story about six weeks ago was that Europe sucks wind and they will cut like crazy while the Fed might even hike rates and so that’s it for euro is not playing out. China is bouncing, the US is slowing from torrid levels, and the ECB language is leaving plenty of optionality after the June 6 cut. A hawkish cut at that meeting looks increasingly probable.
I don’t want to risk short USD into the S&P PMI at 9:45 a.m. today, but if both Manufacturing and Services are below forecast, I will buy EURUSD. The stop loss is 1.0789.
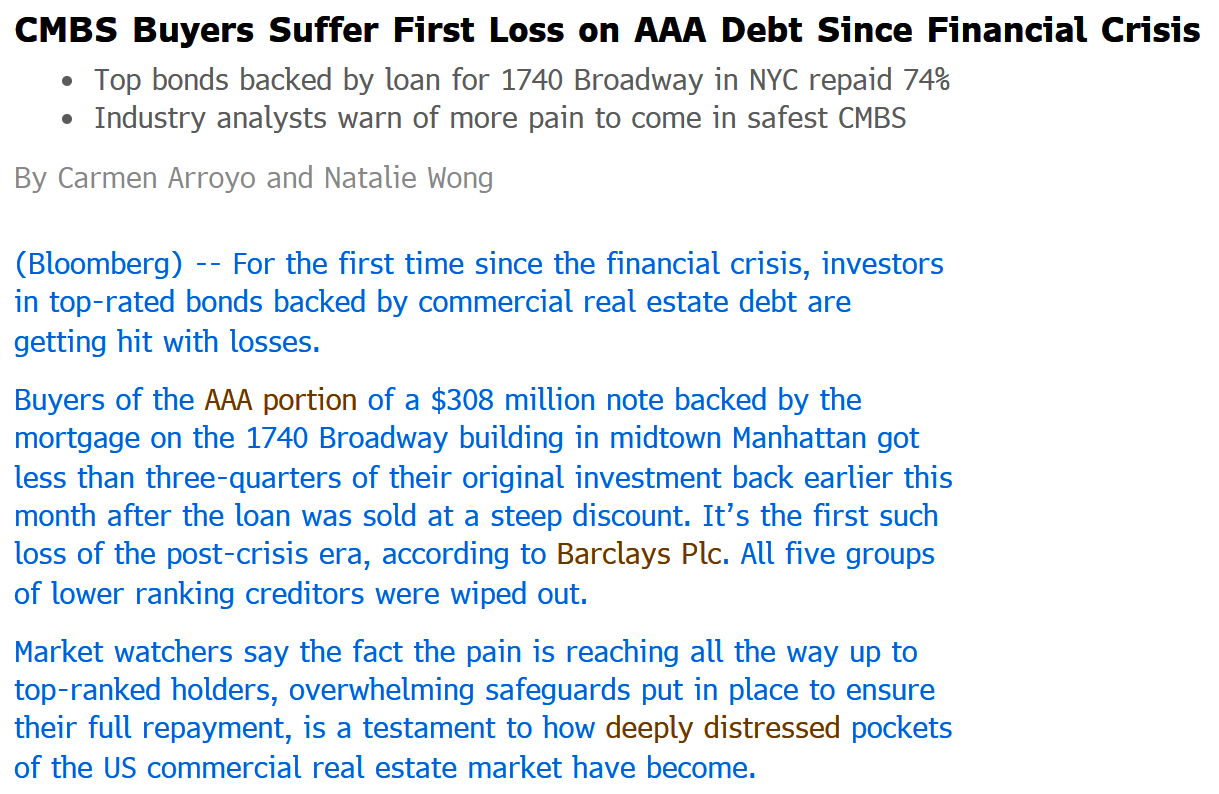
For your radar: I have pointed out recently that credit card delinquencies in the US are on the rise. Now, we have the first AAA default since 2008. Maybe the credit cycle is finally rolling over as higher for longer actually matters, eventually?
And finally. It would stand to reason that much as macro traders were in heavy demand in 2022, then there was a culling in late 2023… There are going to be cuts for FX traders soon if currency vol doesn’t pick up.
Meanwhile, everyone is opening a commodity fund and paying up for commodity traders. Yet it was impossible to raise money for a commodity fund in 2017, for example. I remember the same thing in 2007, when Lehman hired scads of new EM traders after a 7-year bull run in emerging markets.
This procyclical hiring and firing cannot be good for business, can it? Has anyone ever seen a firm that hires countercyclically instead of procyclicality? That seems like it would be an edge. Still, it may be impossible due to investor and management metagame and career risk.
Hiring a commodity trader now and firing an FX trader is easy to justify right now, but probably negative EV. Procyclical extrapolation bias dominates hiring and firing of traders, but investors are procyclical too, so maybe it’s their fault? Investors chase past performance and the hottest asset classes and thus the money comes in and needs to be deployed and so firms simply react to that much of the time. Anyway, just something to think about. Even if you can’t be countercyclical, you can at least be less procyclical.
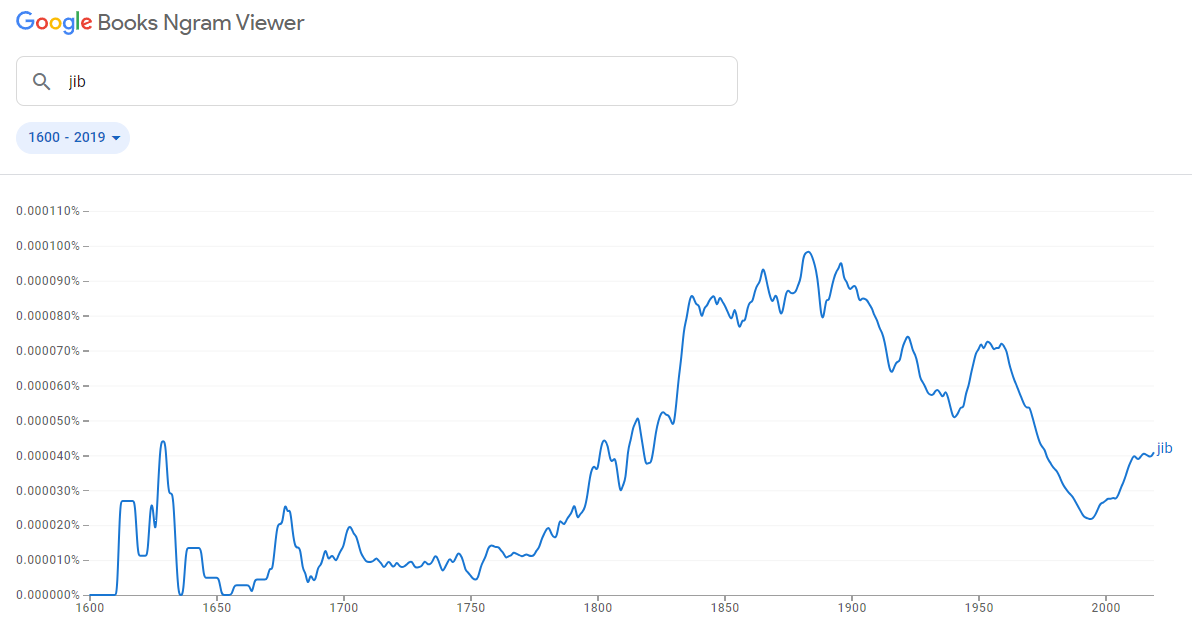
Hope you liked the cut of my jib today.
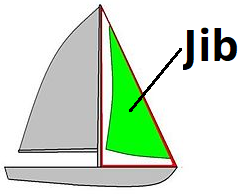
In pre-industrial sailing, you could rely on the foremost triangular sail on a ship (the “jib”) to identify a ship in the distance (perhaps using a telescope). By the way this sail was cut, sewn, and constructed, you could tell whether a ship was friend or foe – British, French, etc.
So, if you don’t like the cut of someone’s jib, it means you don’t like the signals they’re sending – you don’t like their personality or demeanor.
1600 to now


This piece is mostly for people who are interested in backtesting

