Last week’s NZ budget and the scorching immigration numbers make short NZD into RBNZ a bad trade, imo. I am covering the tactical short from last week.
subscriber-only
RBNZ and CNH
Current Views
20JUN USDCHF
0.8850 digital put @ 20%
spot ref. 0.9275
May 22, 2023
RBNZ and CNH
The NZD tactical short idea has expired. The RBNZ meets tomorrow night, and I am taking profit on the trade. It’s mildly disappointing, despite being a 1% gain, approximately, because the thesis was solid (lower inflation expectations in NZ + China narrative flip) but we are now more than 1% off the lows and missed the original TP (0.6166) by a few hairs. Still an OK trade overall and I feel strongly that risk/reward of staying short NZD into RBNZ is extremely poor.
The key to my view on May 11 (am/FX: Tactical Short NZD) was that 2-year inflation figures would be weak last week and that is what happened. NZ dumped and angst about China increased, and it looked like we were good.
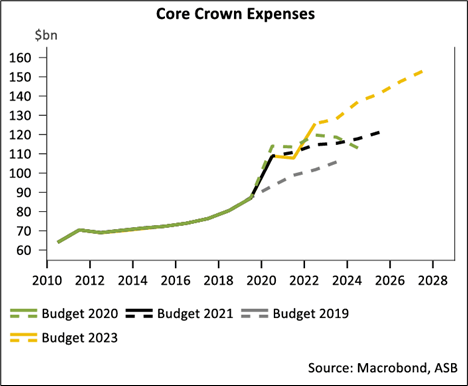
Unfortunately, the NZ budget is not supportive of lower NZD as we get the old “we’re gonna spend more money to offset the inflation problem” situation(!) Below is a chart of NZ federal spending from ASB with the yellow line showing you the post-budget trajectory vs. prior years.
The RBNZ meets tomorrow (10 pm NY time) and I’m concerned they will sound hawkish. There is also some risk they go 50bps, and that will be impossible to risk manage in spot. While inflation expectations dropped significantly, the rise in immigration and the fiscal impact of the NZ budget mean that even if the current situation looks fine, the forward outlook on inflation remains dicey as the NZ population influx is large and the jobs market is tight like every other G10 jobs market. Here’s how market pricing changed while I was away late last week.
RBNZ pricing for May 24 meeting
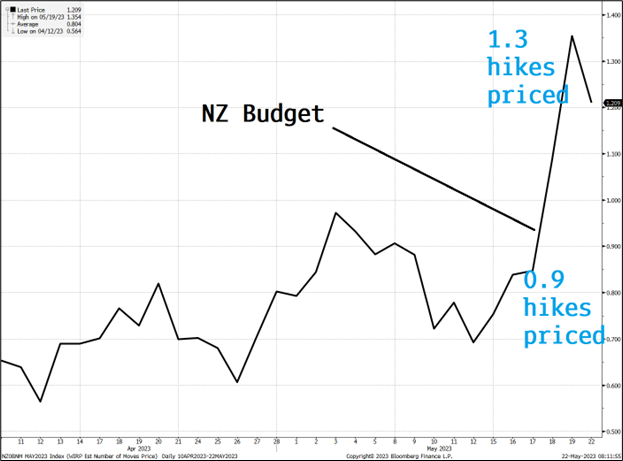
Meeting is May 23 NY time, May 24 Wellington time
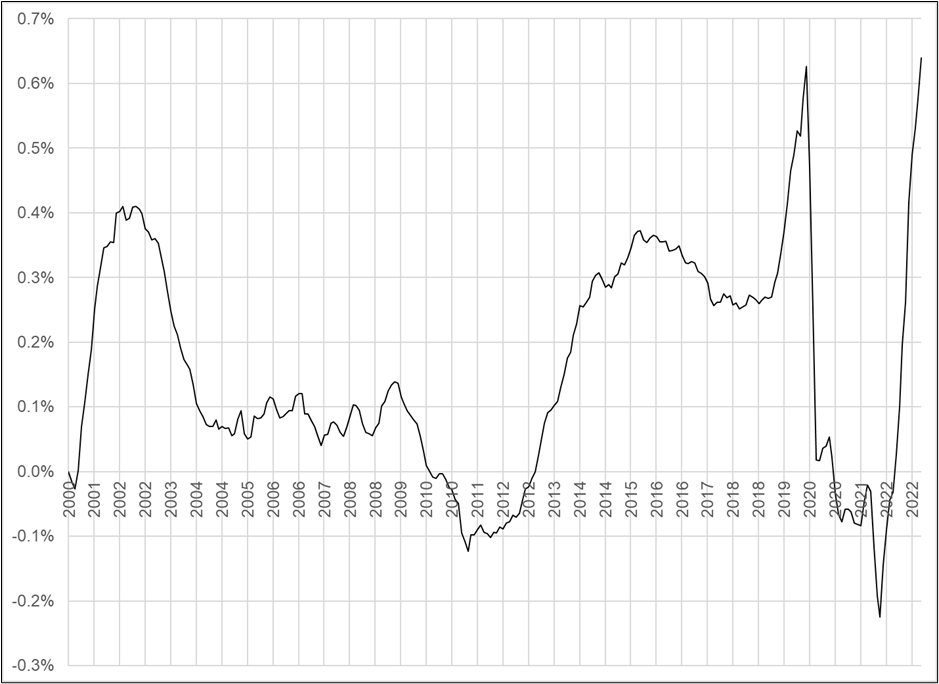
And for context, here is the immigration data. That data came out ages ago, I’m just saying that in conjunction with the NZ Federal Budget I don’t think risk/reward on short NZD into RBNZ is at all good. The central bank could choose to focus on the encouraging inflation expectations and inflation data (and reduced pressure from China reopening), but they are more likely to continue on their aggressive campaign as non-tradable inflation remains high, immigration is surging, fiscal is accommodative, and labor markets are generationally tight.
3-month sum of net immigration divided by total population of New Zealand
If you’re short NZD and want to stay with the China slowdown trade, just switch to an AUD or CNH short.
China
The breakout in USDCNH has captured the attention of the market and we have been seeing good interest to buy topside. I think USDCNH can continue higher and complete the round trip to 7.30/7.35.
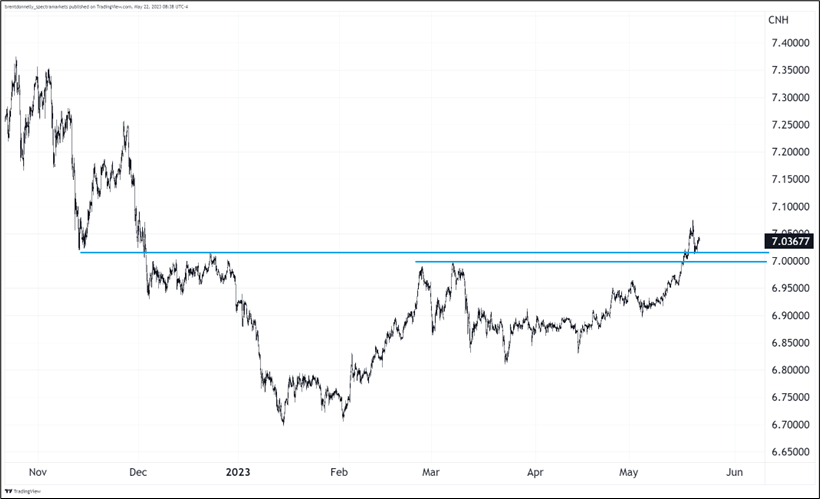
You can see the path of USDCNH followed the path of interest in China reopening, just about perfectly.
USDCNH (top panel) vs. Bloomberg stories about China reopening (bottom panel)
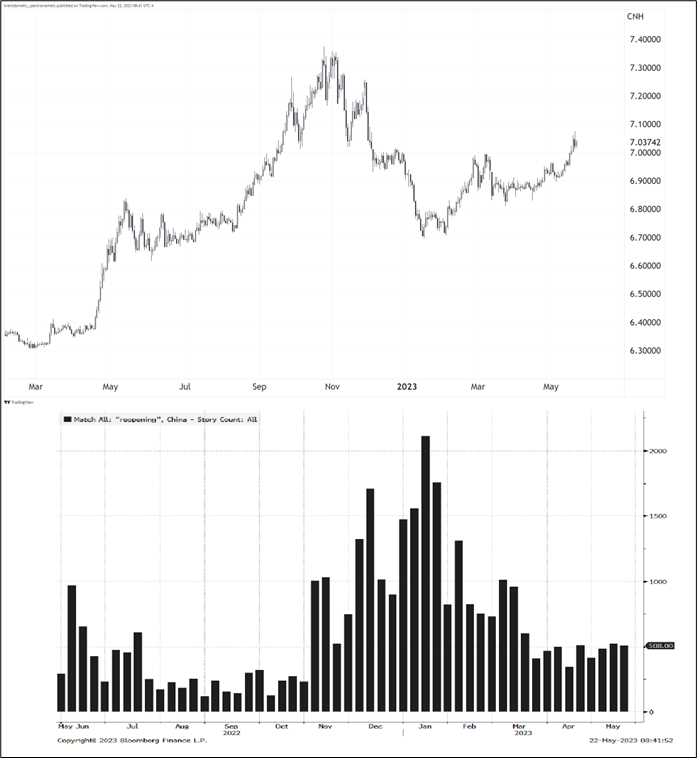
You can see that as interest picked up in November 2022, USDCNH peaked. The top for China reopening stories (mid-January 2023) was the bottom for USDCNH. Now, as discussed last week, I think the China narrative is rapidly reverting to the old issues of disinflationary balance sheets, local debt crisis, a weak real estate underbelly, more communism, less capitalism, and a docile consumer.
The market has certainly got on the USDCNH trade, but with no rate cut this month and a rapid flip in the narrative, I don’t think the market has fully pivoted yet. Many specs were slow to embrace the China slowdown trade because they still had deltas the other way (short USDCNH for reopening juice). It takes people (and the market) much longer to embrace a theme if the exact opposite theme was very recently en vogue. Switching and flipping is not fun, and many traders hate to do it. But eventually, the FOMO, or the logic of the new narrative becomes irresistible. I don’t think we are close to the point where the final specs get sucked in. That will more likely happen at 7.20/7.25.
Debt Ceiling
Wildcard. Impossible to handicap. Even if we knew what the result was (short-term extension, abrupt end of talks, complete happy surprise resolution…) we would not know what the trade is. While a resolution is bullish risky assets on the surface, many people believe that the liquidity implications of a deal are raging bearish risky assets as the TGA gets refilled (TGA explainer here) and money will get sucked out of the system. The implications for the dollar are not obvious in most scenarios, either.
I suppose one outcome that seems clear is that a complete resolution is bearish gold. There has been a frenzy of bullish gold sentiment over the past month and that triple top feels ominous. If the debt ceiling were resolved, I would expect a big capitulation in gold. Down to 1843 or so. $1843 is the midpoint of the broad range since 2020.
Gold with triple top and 2-year range marked
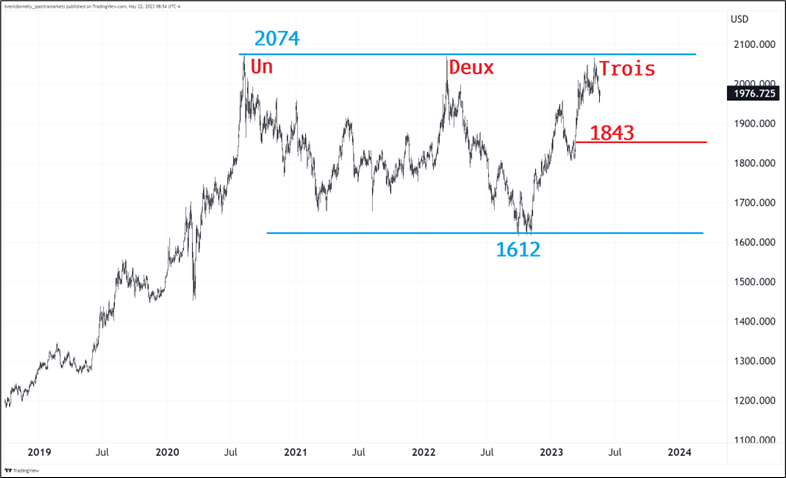
Then again, on a technical default gold is probably at $2700 or something, so nobody is going to cut now. Gold is often viewed as insurance and in this scenario, that makes sense.
Final thoughts
Bullard loves to stir the pot, as we saw this morning.
*BULLARD: EXPECTING TWO MORE RATE HIKES THIS YEAR
I know forecasting is hard, but just for fun… Here’s a flashback to July 2021:
*BULLARD SAYS HIS DOT REFLECTS RATE LIFTOFF IN LATE 2022
By the end of 2022, the Fed had already hiked seven times for a total of 17 twenty-five basis increments.
Have a Kevinly day.
good luck ⇅ be nimble
“The name Kevin (usually spelled Kévin) came into popularity in France in the early 1990s, thanks to the pop culture influence of actors like Kevin Costner, Kevin Bacon, Kevin Spacey, and the character of Kevin McCallister (played by Macaulay Culkin) in the 1990 classic Home Alone. In 1991, Kevin was the most popular name for baby boys in France. But in the intervening years, the name suffered a steep decline, and a French parent today wouldn’t dream of using it.”