Stocks
Sometimes you do the work on something, and then it ends up being a waste of time. That’s okay. That is what has happened with PPI and CPI for me as all my carefully tossed number salads end up in the compost heap. There was no edge in CPI as the PPI miss was not conclusive.
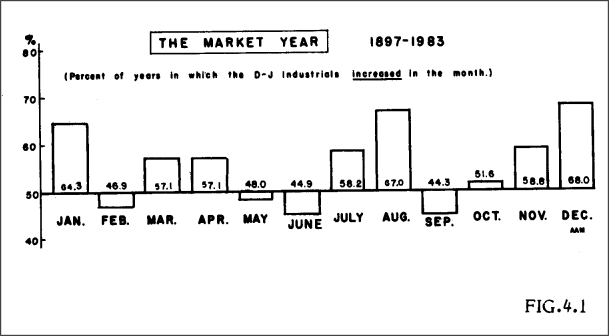
Moving right along! It’s amazing how the bearish equity seasonal has worked so well out of sample for so many years. I was curious whether it matters if you short stocks in the second half of September or wait until after Triple Witching. Answer is: It doesn’t seem to matter.
This chart shows the cumulative P&L of going short S&P 500 on September 15 or going short at the close on Triple Witching (for this year, that would be next Friday). If you have ever done any backtesting of S&P 500 strategies, you can appreciate how extraordinary this is. It’s almost impossible to find any persistent bearish event test for stocks.

Shorting the S&P over any random two-week window loses 0.4% to 0.5% on average and wins only about 40% of the time. Shorting the second half of September has a 55% win rate and an average return of +1.2%. Pretty mind blowing, especially as this thing was unearthed in the late 1960s. Back then, Walter Merrill identified September as the worst month of the year in his 1966 book: The Behavior of Prices on Wall Street.
Shorting stocks in the back half of September does not work every time, obviously. And it always seems way too obvious, like, “It can’t possibly work again this time!” With VIX at 17, you are not paying much to take your shot. Here are the stats for the two strategies.

I am away for the next two weeks on a family trip, so I bought 25SEP VXX calls yesterday as a simple way to get some leverage for a possible stock swoon. I don’t need to tell you why stocks could dump. There are plenty of reasons right now. Then again, there are always reasons.
Corr flip?
I have written extensively about how FX correlations to commodities broke down post COVID, but the reality is that the correlation story is constantly in flux. Here’s a chart of the 26-week rolling correlation of changes in AUD and CAD (combined) vs. copper and oil. Because this is a 26-week metric, it masks the extremely high correlation in the past few months.

The commodity vs. currencies correlation cracked when the War in Iran started because risk aversion combined with higher commodity prices is not clearly beneficial to cyclical currencies. But now, as oil rallies are not consistently accompanied by risk aversion, CAD and AUD can benefit from higher commodity prices.
You can see it in my next chart, if you put on your glasses. AUD, CAD, copper, and crude are all moving as a giant blob again. I think the main explanation for this is that equities are not particularly hard hit by Iran headlines these days, even when oil spikes, and therefore the risky / cyclical currencies are able to benefit from the export boost potential of rising commodity prices. Furthermore, the moves in commodities have been broad-based as ags and precious have done pretty well in recent months, too, and broad-based commodity rallies are more supportive for Australia and Canada than idiosyncratic, geopolitics-driven rippers in oil.

While my job is to have a strong view on the USD at least most of the time, I really do not have a dollar view right now. The ECB is hiking into a potential winter energy crisis, but nobody cares. AUDUSD is crowded just as dividend season ends and copper turns, but who’s going to short AUD? NZD looks like a bad currency to own as rate hikes there are overpriced. EM carry is okay but do you want to own it into the worst two-week period of the year for risky assets? Hard to find clear bullish non-USD stories other than the JPY.
On the other side of the ledger, the Big Random U.S. Policy Wheel spins every morning and sometimes lands on tariffs, or war, or trillion-dollar economic rebates, or government calls for Fed rate cuts into full employment, or whatever. And Scott Bessent is increasingly eager to participate. As Jared Dillian pointed out today in the Dirtnap: The U.S. government is probably not far from enacting some new measure to cap bond yields as prior measures fail. It’s very hard to get excited about long dollars, especially as midterms will bring more policy confusion and fiscal drag looms.
USDJPY shorts remain in control as the busted 155.00 level has become monster resistance. Anyone that missed the selloff in USDJPY so far is camped up there somewhere hoping to sell 154.30/70 ahead of the massive support that broke and is now resistance. My 08SEP view that USDJPY is set for a 152/155.50 range remains and yen vol still looks overpriced to me. Next week’s BOJ is going to be a humdinger as there is plenty of room for disappointment if the market overestimates how much the Japanese actually care about what Scott Bessent thinks.
Calendar
The BOJ is the biggie next week, with the FOMC pretty important too.

Final Thoughts
Since I was talking about copper today; the reversal yesterday on the potential tariff walkback sets up an interesting reversal out of a narrowing pincer wedge type of formation. If you have some other reasons to be bearish copper, it’s a nice setup from a risk/reward point of view because you can simply stop out if it makes a new high (above $700 on HGZ6) and if you’re right, you catch three or four ATRs.

Have a mysterious couple of weeks. I will see you at the very end of September!