
A quick rundown of the current state of TINA, the USD, and US exceptionalism. Plus more.
There is a subreddit called r/lies.
The top results of all time are
funny in a particular way that
appeals to me but maybe
not everyone.

A quick rundown of the current state of TINA, the USD, and US exceptionalism. Plus more.
There is a subreddit called r/lies.
The top results of all time are
funny in a particular way that
appeals to me but maybe
not everyone.
20JUN USDCHF
0.8850 digital put @ 20%
spot ref. 0.9275
May 23, 2023
EURUSD is following rate differentials pretty much tick for tick. US yields have recovered more than half the drop after Silicon Valley Bank went under and we are right back in the US Exceptionalism regime. This is a huge surprise to almost everyone as most (including me) thought TINA was dead. But she was just napping.
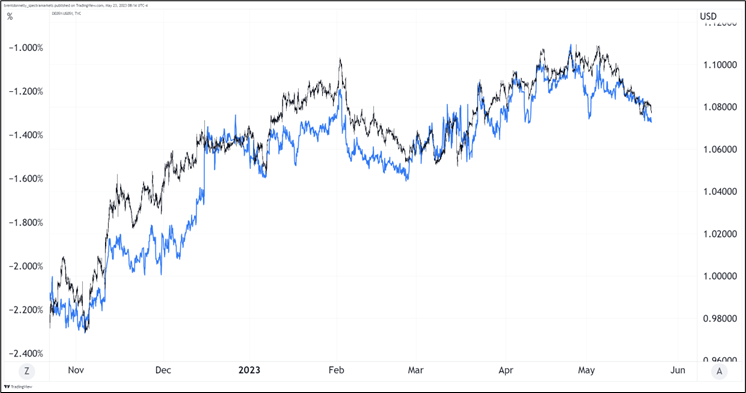
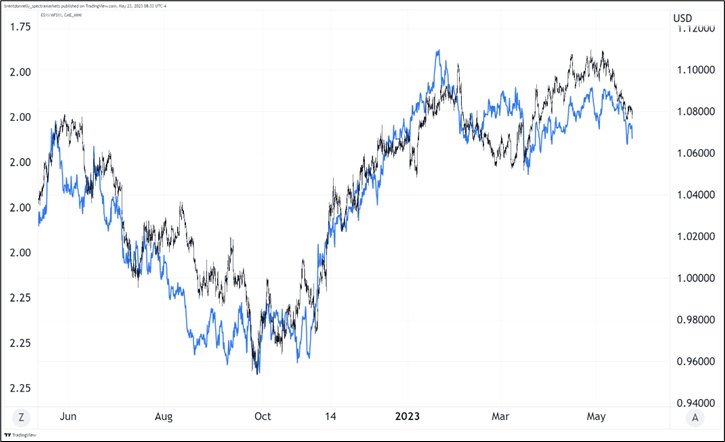
The reversal in US rates has been large and somewhat surprising. As has the rebound in US equities vs. the rest of the world. Interestingly, while EURUSD has followed rate differentials tick for tick, it’s following the US Exceptionalism Index perfectly, too. Here is the SPX/EAFE ratio (inverted) against EURUSD. The blue line going down means SPX is outperforming the rest of the world. As SPX outperforms, the USD outperforms.
Maximum hope for global economic outperformance coincided with peak China reopening excitement in late January. We have exited what was briefly a textbook middle-of-the-dollar-smile regime where the rest of the world was doing well and US was softening, and we’re now back on the right-hand side of the smile where USA outperforms while Germany and China look sus.
Until this illusion of a bad forward outlook turns into something real, markets are torn between a strong need to position for what looks like an inevitable economic calamity, and the grinding daily P&L leakage as the clock ticks and the theta bleeds. Hopefully we will know it when we see it. The real transition to a weak economic regime will probably start with global labor market weakness. There is no meaningful labor market weakness in G10 right now. Once one labor market turns weak, they will all follow.
Industrial production around the world has hit a wall. Manufacturing PMIs are below 50 in most countries. Taiwan Industrial Production came out last night. Abysmal. Buy NASDAQ!¹
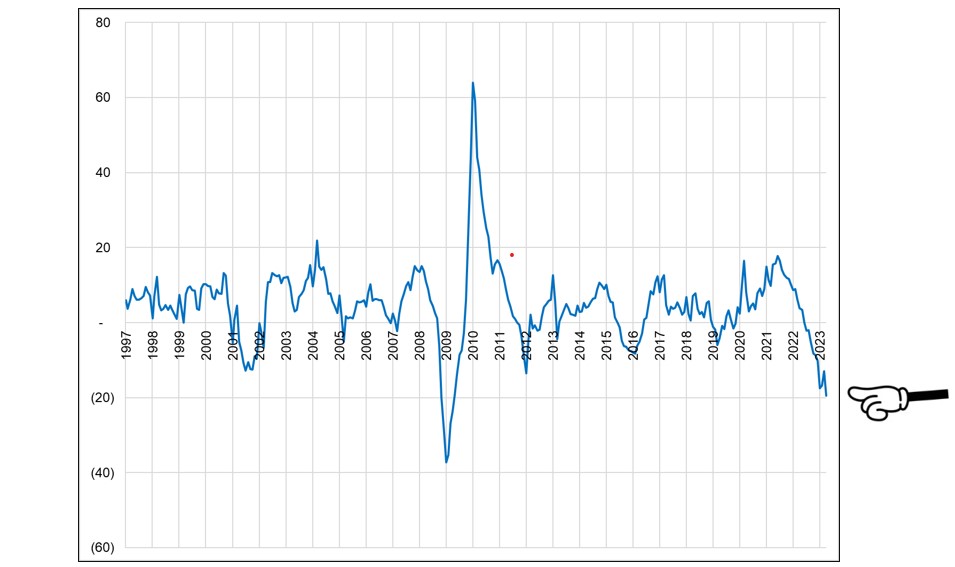
2-month average
Et voilà les PMIs en Amérique et Europe. Pas bon!
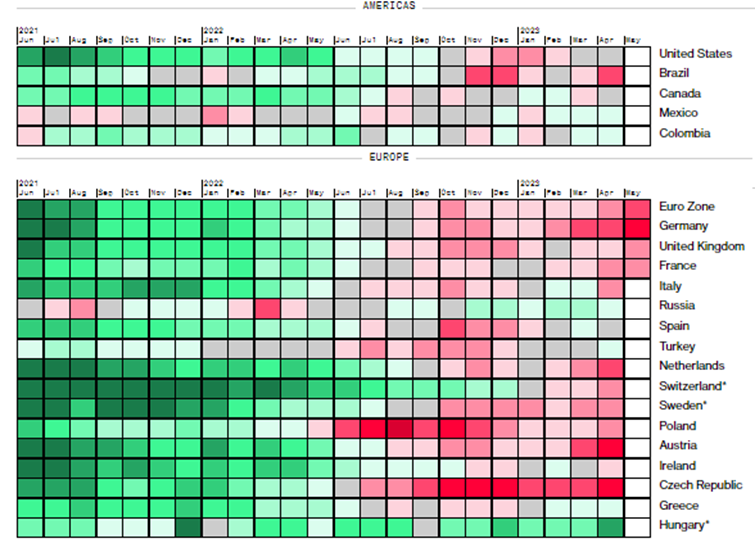
https://www.bloomberg.com/graphics/global-pmi-tracker/
—
¹ Sarcasm.
This raises the stakes for next week’s OPEC meeting.
“I keep advising them that they will be ouching — they did ouch in April,” Saudi Energy Minister Prince Abdulaziz bin Salman said at the Qatar Economic Forum in Doha on Tuesday. “I don’t have to show them my cards and I’m not a poker player. But I’d tell them: ‘Watch out’.”
As discussed yesterday, I think the risk/reward going into RBNZ received rates or short NZD is not good. That said, if the RBNZ does decide to focus on falling inflation and inflation expectations, that is a go with. That would be a framework change from hawkish to dovish and I think NZD will get flambeed on that outcome.
New piece from the Convexity Maven (Harley Bassman).
Surgeon General’s warning on social media and adolescent mental health. Better late than never.
Have a true day.
Hi. Welcome to this week’s report. The big story this week is the huge surge in interest to buy USDCNH topside. This is a big shift from the story throughout most of 2023 as China reopening was expected to reduce the gap between US and China yields, but instead China reopening has been a dud while US exceptionalism was dormant, but not dead. Here is the 5-year rate differential and USDCNH:
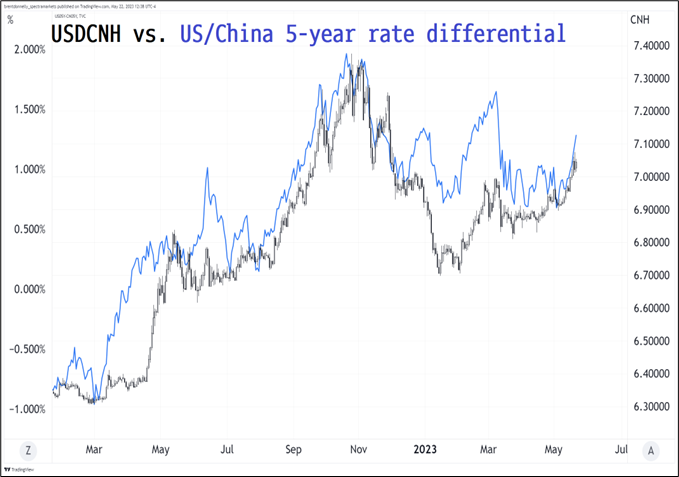
Is long USDCNH a problem? Not yet. The market was short USDCNH and owned USDCNH puts up until a few weeks ago. Now, the narrative has flipped, and the market is slowly getting onside. If this were a basketball game, we are late in the 2nd quarter. There is plenty of scope for positioning to increase and for spot USDCNH to revisit the 7.25/7.30 level where it peaked in November 2022 before the abrupt abandonment of the Chinese zero-COVID policy.
So, while I believe there is more upside, it is worth showing you the options volumes that have gone through. They are large! This next chart, prepared by Spectra options specialist and data science wizard Christoffer Larsson Klint, shows weekly CNH option volumes at the 2023 highs. Then again, if you follow USDCNH, you probably could have guessed that, because options interest in CNH has been moderate and spotty most of this year. The chart also shows that the initial wave of options demand in September 2022 was the start, not the end of the USDCNH trend. USDCNH rallied from 6.70 to 7.37 from August to November 2022. The peak in spot USDCNH was early November and followed about 10 weeks of ravenous topside appetite.
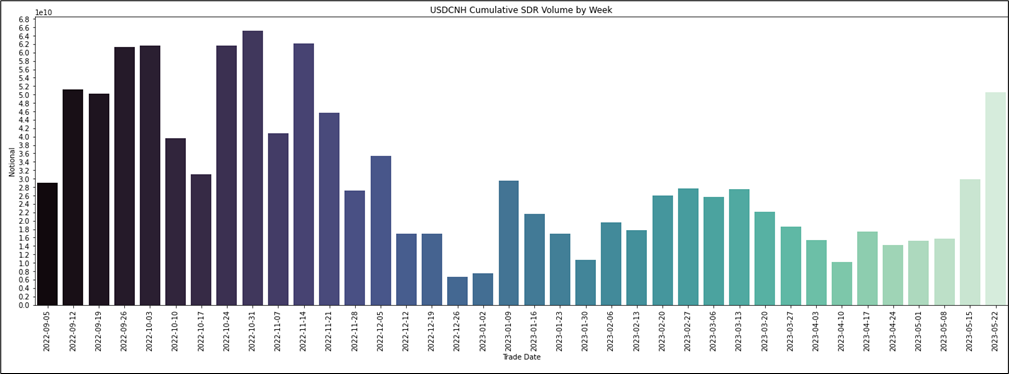
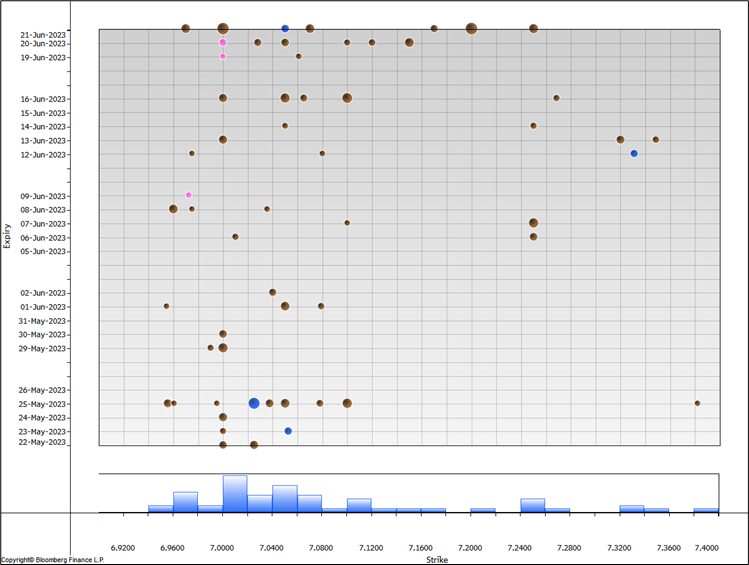
Drilling down to look at open strikes (see next page), you can see specs have been somewhat conservative with their targets. The modal strike is 7.0/7.02ish and there is barely anything above 7.10. There is a small secondary cluster of strikes at 7.2500 (concentrated around June 7), so you can write that down on your notepad as a level of interest.
The initial setup, where the market was short USDCNH, plus the conservative targets (and RKO popularity) in options markets, and my subjective assessment of customer frenzy level all suggest it’s too early to worry about USDCNH long positioning. If you’re bullish, stay long and think about taking profit 7.20/7.25. Options are much easier to manage than cash because PBoC intervention/smoothing risk is always lurking and 1-month vols are still low.
—
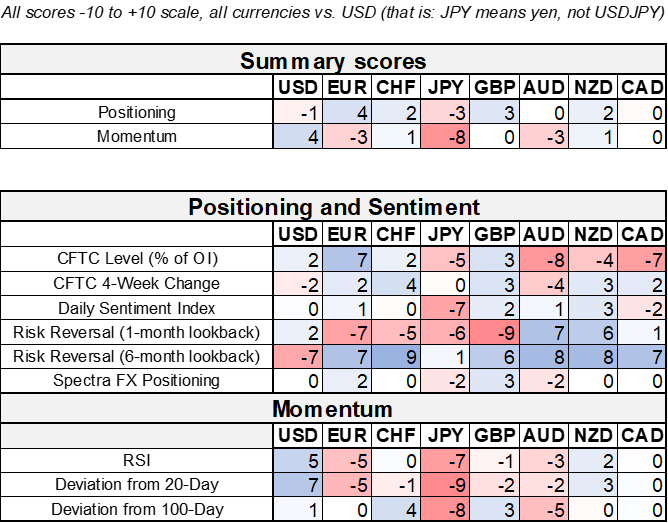
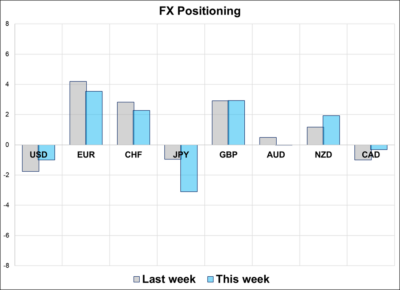
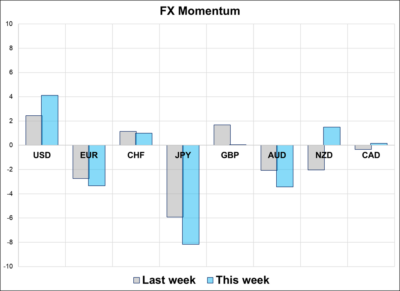
That’s this week’s report. Thank you for reading.
(This screenshot harder to understand in black and white)
HT Adam D


This piece is mostly for people who are interested in backtesting

