
Bonds and EUR
Larger version of the graphic at bottom of am/FX

Bonds and EUR
Larger version of the graphic at bottom of am/FX
Short EURCHF @ 0.9400
Stop loss 0.9517
Short EURJPY @ 184.80
Stop loss 186.37
09SEP USDCNH call spread
6.7300/6.7400 for 42 CNH pips
Risking 42 to make 58 off 6.7430 spot
10SEP CHFJPY put spread
199/196 for ~37bps off 200.50 spot
The move higher in bond yields continues, and it is becoming increasingly hard to figure out at what point we should become scared. Japanese yields have been going up in a straight line and have made a new 10-year high ninety-nine times since the first one printed on September 23, 2023.
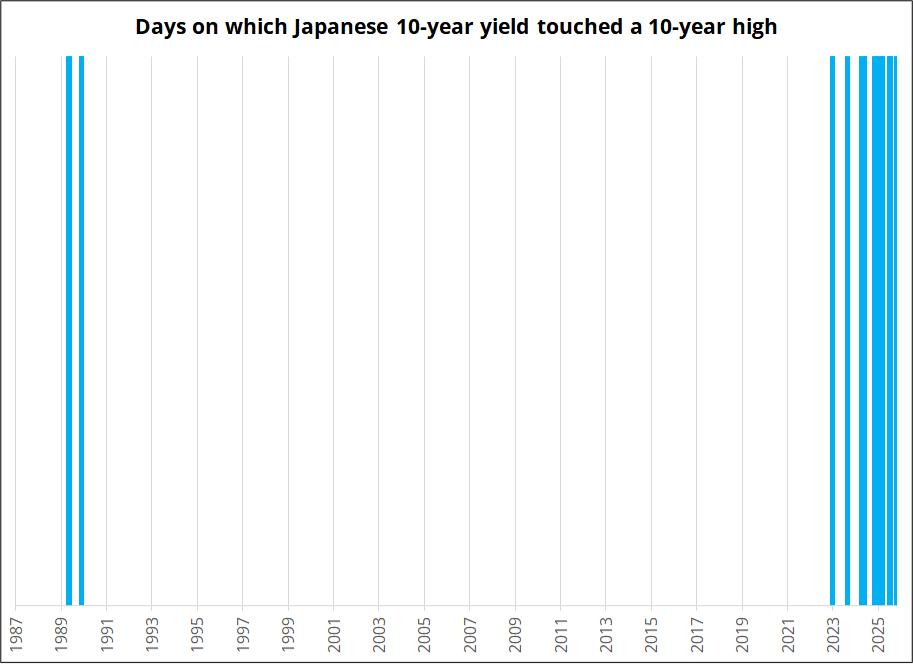
It might seem a bit counterintuitive that something would go thirty years without hitting a 10-year high, but that’s what happened! A 10-year high is a rolling lookback condition, not something that must occur once every 10 years. On any day, the test is: Is today’s JGB yield ≥ highest yield observed at any point during the past 10 years?
If yields are in a persistent downtrend, that condition can fail for decades. Japan is an extreme example as yields went down, down, down for thirty years. Anyway, my conundrum is that higher yields will almost certainly matter at some point, but if they are today making their 99th 10-year high of the past three years, is today the exact day to start worrying?
Equities have been in a monster uptrend along with yields as the story has been normalization, not tightening financial conditions. But it doesn’t take a ton of imagination to think that we are now, perhaps, starting to tighten the vise a bit too much. The economy is not booming. Maybe there is a point at which it cannot handle ever-higher yields.
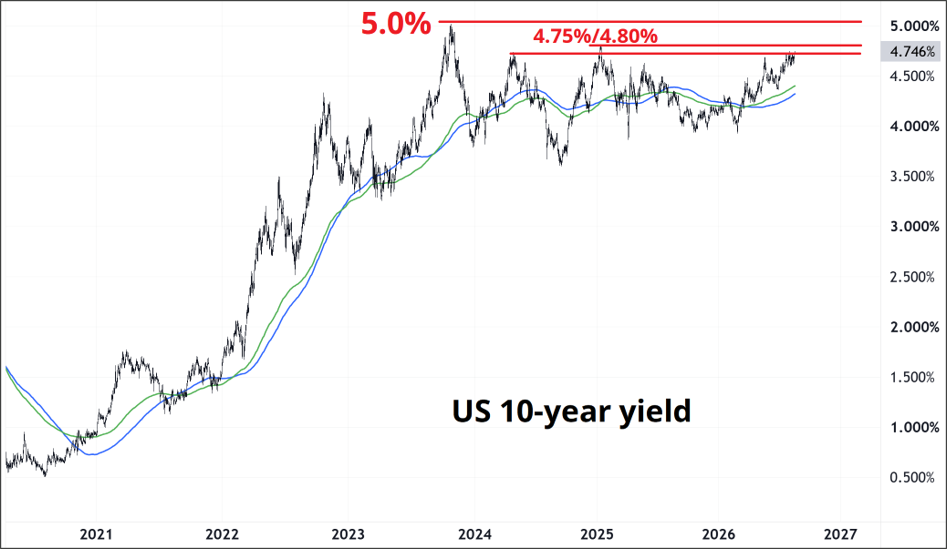
If we’re talking about the U.S. economy, that 10-year yield is more pertinent.
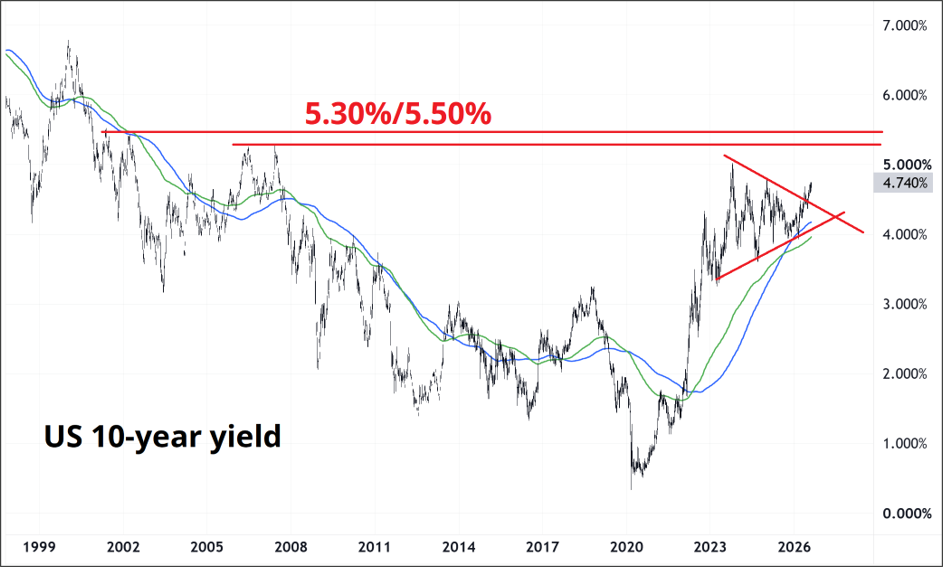
Maybe worrisome? The breakout from a three-year triangle formation is potentially a warning of a sharp move higher, but if you look at that same chart without all the red lines drawn on it, you could also conclude that we are at the top of the range and it’s time to buy bonds. I present the same chart twice like this simply to show how easy it is to interpret the current set up two different ways.
An interesting side effect of the move in yields is that French bond spreads are starting to widen out a bit vs. Germany. That spread tends to move in tandem with EURCHF and EURUSD, though the relationship is anything but tick-for-tick. Here are EURUSD and EURCHF vs. Germany/France 10-year spread, looking back to the start of COVID.
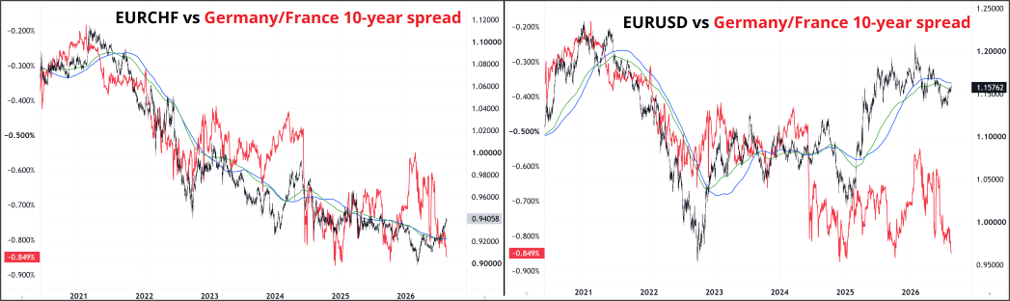
You can see the fit comes and goes, but most of the divergences can be explained. For example, in 2025, the USD sold off on the Liberation Day policy shock and mega pension fund USD hedging/selling. The market went from limit long USD to limit short in a month. That’s why EURUSD decoupled so hard from the spread. I cannot explain why EURCHF decoupled so much from the spread at the start of 2026, however.
In the olden days, EURJPY would also be correlated to sovereign spreads in Europe, but the Japanese fiscal story broke that relationship years ago. Still, with USDJPY near 160 and spreads widening, short EURJPY is not a bad idea here. You get a wonderful entry point, a bearish EUR trade, and an MOF/Bessent kicker.
Bessent’s lack of market credibility has, by this time, become a fairly mainstream view—mainstream enough that he is certainly aware of the rising tide of worries around his ability to manage the deficit, U.S. 10-year yields, the price of oil, the Strait of Hormuz, tariff inflation, EURJPY, or USDJPY. He has a great interest in all of those and has made many predictions about them, but the predictions are not coming true. Given he is aware of the bad press, and 10-year yields are making new highs, and USDJPY is rubbing up against 160… If his original reason for joining the MOF was contagion fears (weak JPY and weak JGBs leading to weak U.S. bond markets): He is probably on the phone with Japan today, or at least thinking about what to do next.
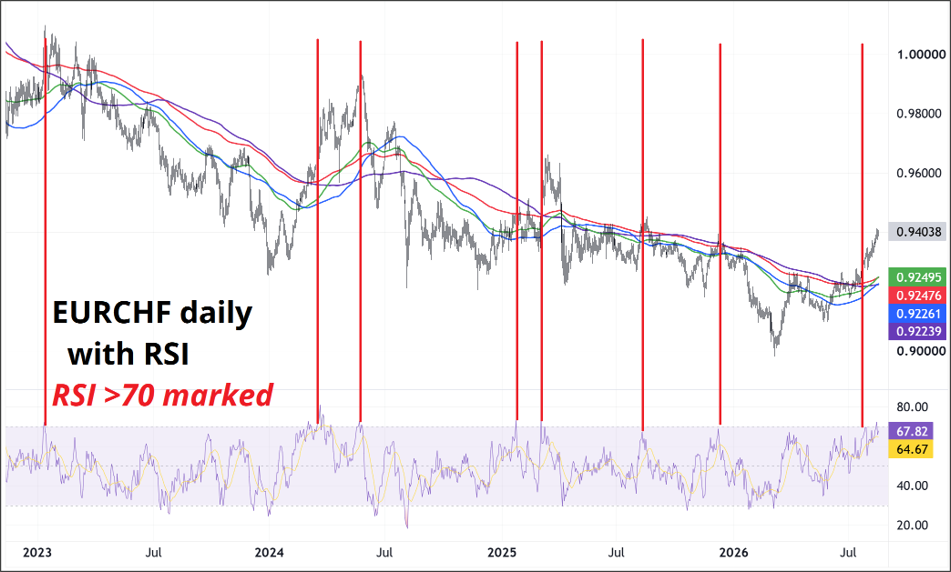
If we are entering a more worrisome phase of rising bond yields, I like both short EURCHF and EURJPY from here. EURCHF is at a major resistance point that has held since Liberation Day and EURJPY is moving right back to the last high during the intervention. The EURCHF chart is here. Note, too, how each time the RSI gets above 70, or below 30, it marks a nice reversal point. This is a feature of mean reverting currency pairs like EURCHF: They don’t need to get to mega extremes in RSI before they turn. Their tendency is to lose steam at the first indication of overbought or oversold.
I also feel that the market is underappreciating the energy squeeze in Europe and how it might create new and more severe risks as we head into winter. It’s probably a tad early for that theme, but the entry points are good for short euro and the carry is not prohibitive.
Here is the EURJPY chart:
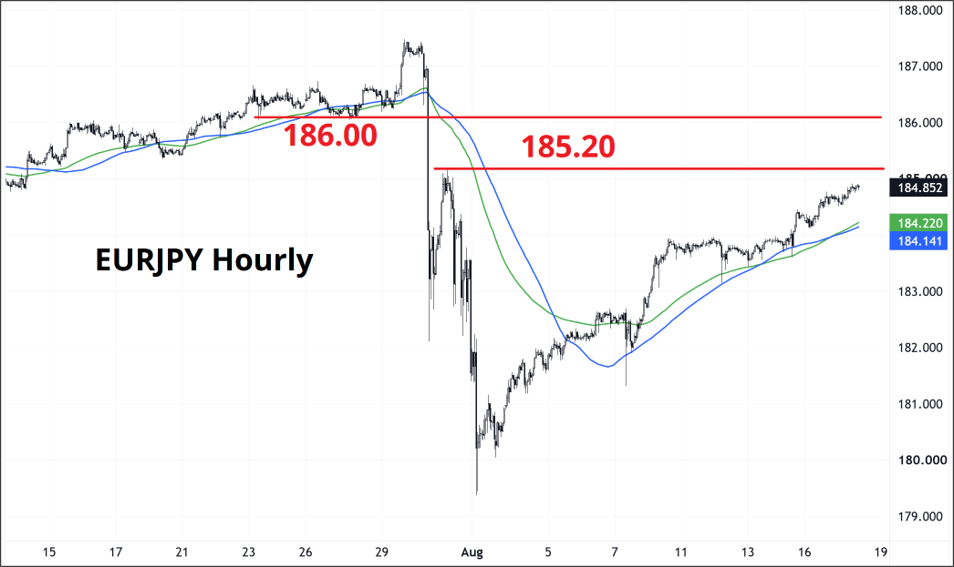
That looks to me like a clear and major resistance zone at 185.20/186.00.
To summarize all this:
The trades I like (see sidebar as always) are:
Short EURCHF here (0.9400) with a stop at 0.9517
Short EURJPY here (184.80) with a stop at 186.37
While vol is low, I prefer the spot trades here because you have to assume the base case over the next two weeks is that everything goes nowhere. That will make options hard to bear, vs. paying a bit of negative carry.
This Jiji article suggests the possibility of a Japanese FinMin shakeup. I planned to write about that today, but I will keep it short because Nippon News Network reported a few hours later, citing an unnamed source, that Prime Minister Takaichi is unlikely to replace the Chief Cabinet Secretary, the Minister for Defense, the Minister for Foreign Affairs, or the Minister for Finance in the upcoming Cabinet reshuffle. That shuffle, likely to take place in mid-September, would be market moving if:
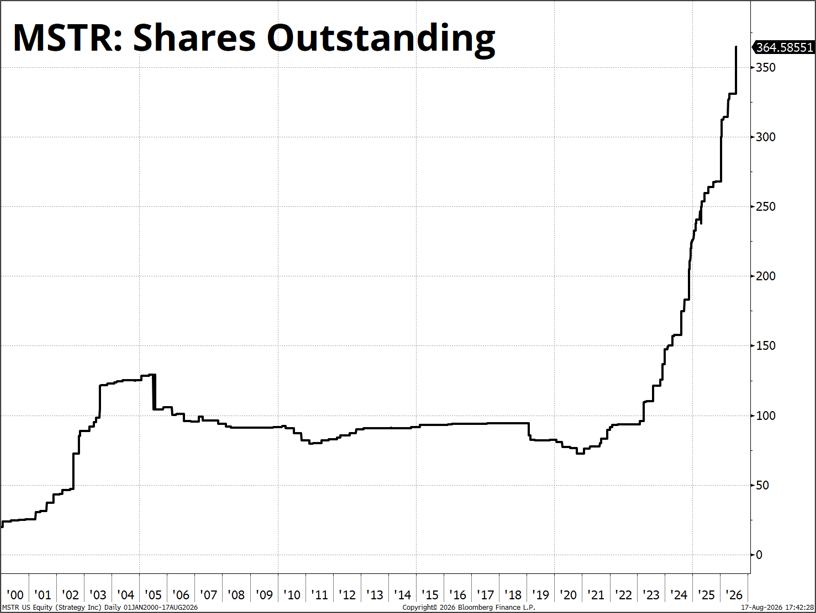
An amazing chart. This is how you get mNAV to 1.0!
Absolutely legendary work here (for video game and/or baseball fans only):
Largest swings are Chicago, Boston, NYC: Cheaper in JAN/FEB and most expensive in SEP/OCT.
New York goes up in December; most cities go down.


This piece is mostly for people who are interested in backtesting

