
The best time to be short EURNOK is when nobody cares about it.
Short EURNOK
Subscriber-only
BD
by Brent Donnelly
Current Views
26APR 11.10/10.90 EURNOK
put spread ~34bps
11.31 spot
Short EURNOK @ 11.31
Stop 11.5610
Take profit 10.9150
21JUN USDJPY
123 digital put @ 20%
spot 131.30
20JUN USDCHF
0.8850 digital put @ 20%
spot 0.9275
March 28, 2023
Short EURNOK
The only good time to sell EURNOK is when nobody cares about it. I think this could be one of those times. EURNOK has been grinding higher in slow motion, and the Sharpe of long EURNOK recently rose above 4.0. This is somewhat rare and is a decent reverse indicator. It has happened seven times since 2014 and all seven times EURNOK was lower 20 days later. The average drop is 3.8%. Here is the chart.
EURNOK daily with blue lines showing each time the 3-month Sharpe >4
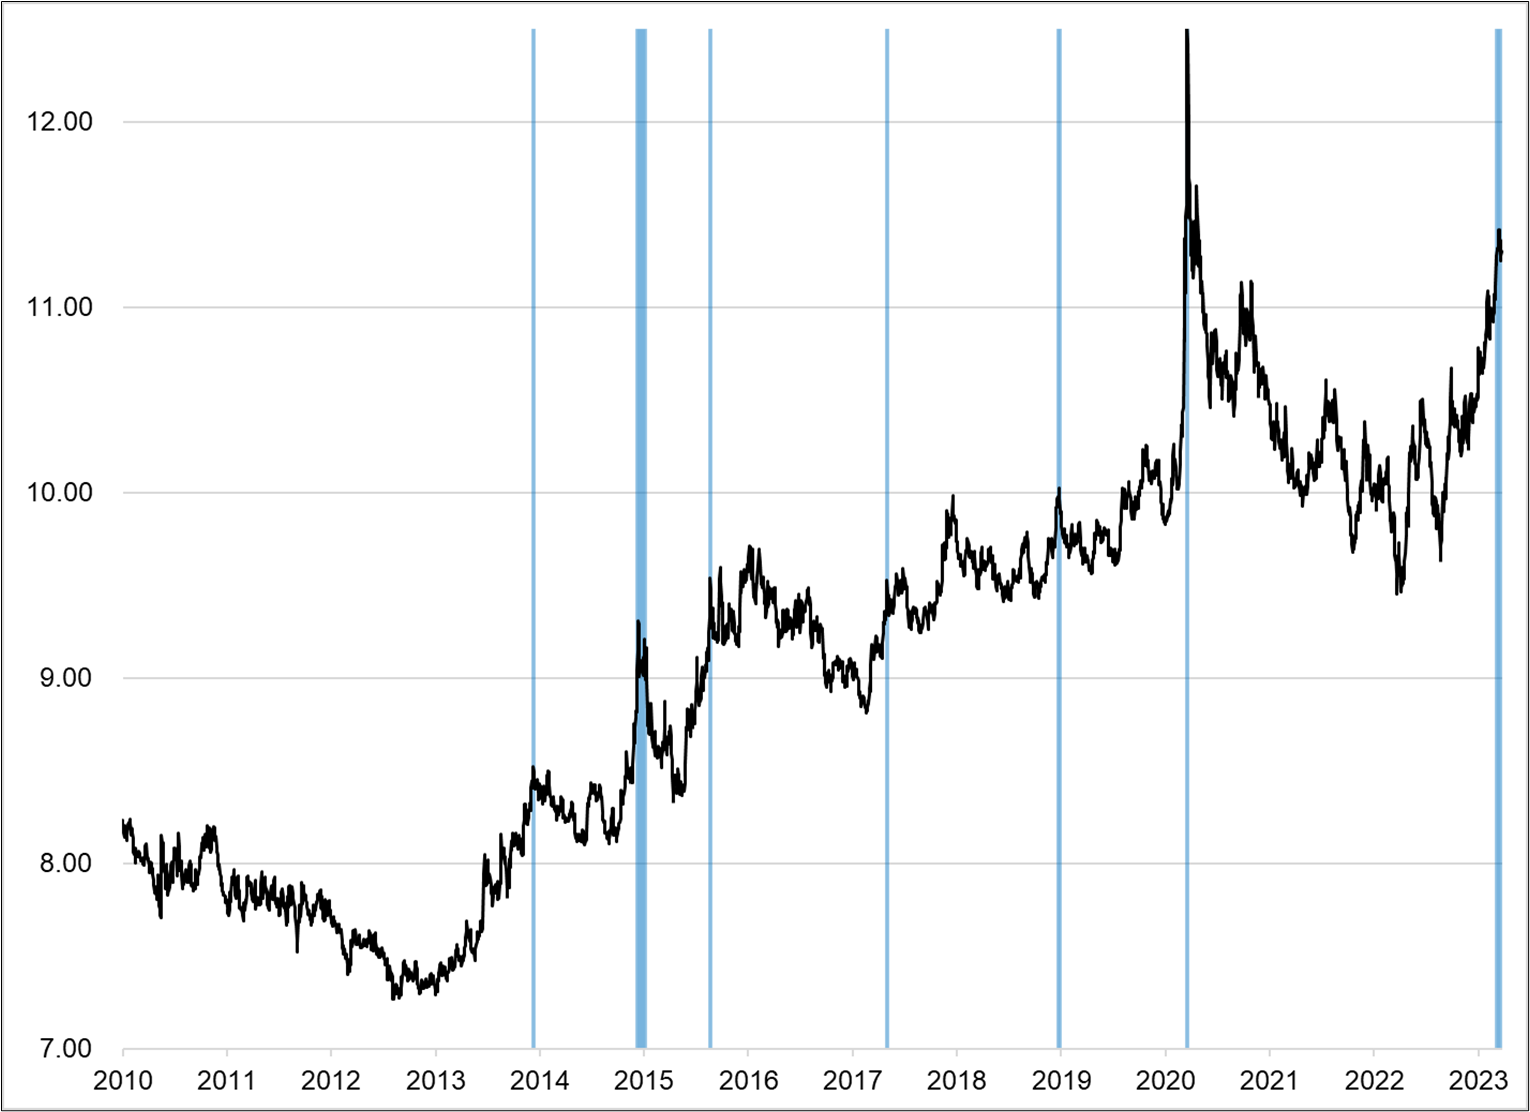
For simplicity, Sharpe ignores risk-free rate
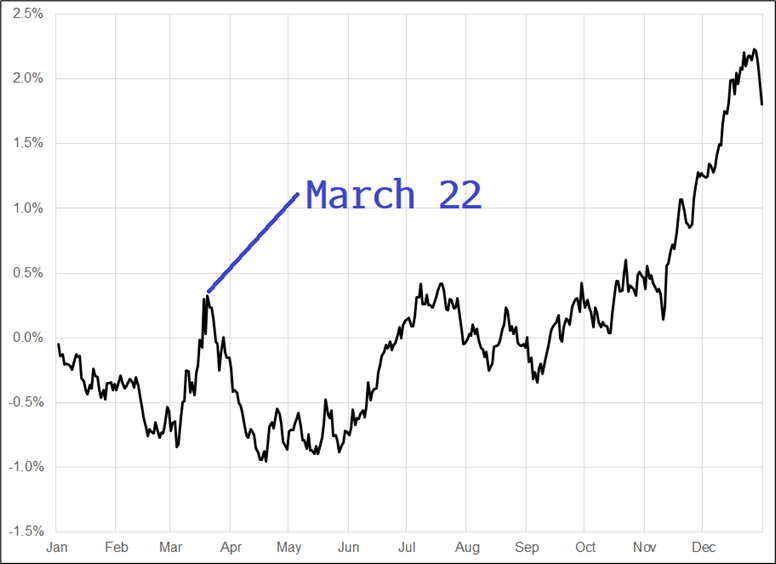
The seasonals also look good. The high tends to be ~March 22 as you can see here.
EURNOK average cumulative seasonality since 2000
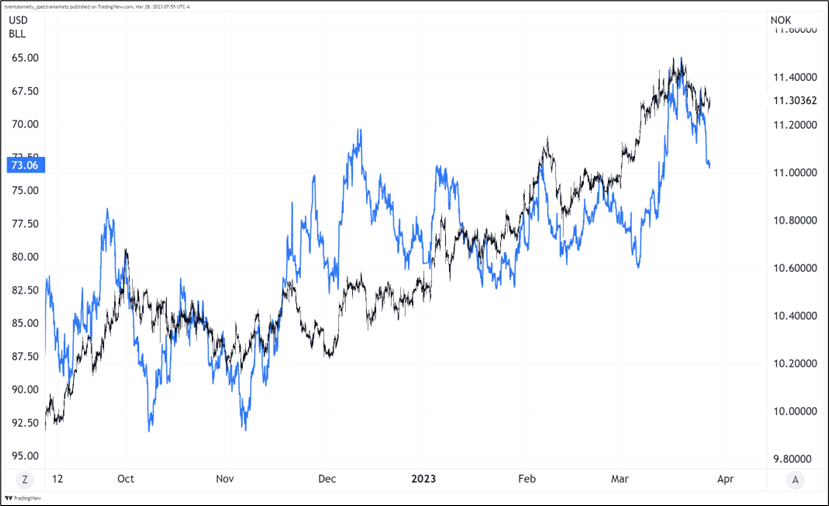
And while oil has not been the be-all-end-all for NOK because Norwegian oil revenues go to the wealth fund, there is still some correlation. The broader Norwegian economy still does better when oil is high than it does when oil is low. Here is the current overlay of EURNOK and crude oil.
EURNOK vs. crude oil, inverted (hourly back to September 2022)
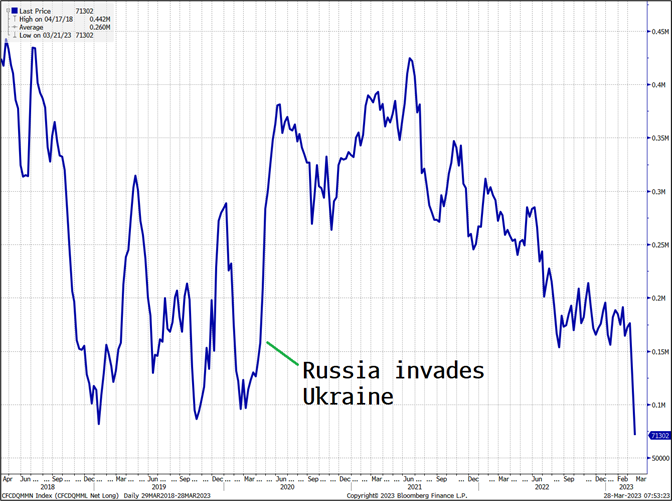
And this crude oil rally off the $65 lows looks much more sustainable to me than past rallies because the market has finally capitulated on its year-long view that the Russia invasion of Ukraine is bullish. Here is the chart of money manager positioning in NYMEX crude. Full capitulation.
NYMEX WTI crude, money manager net longs
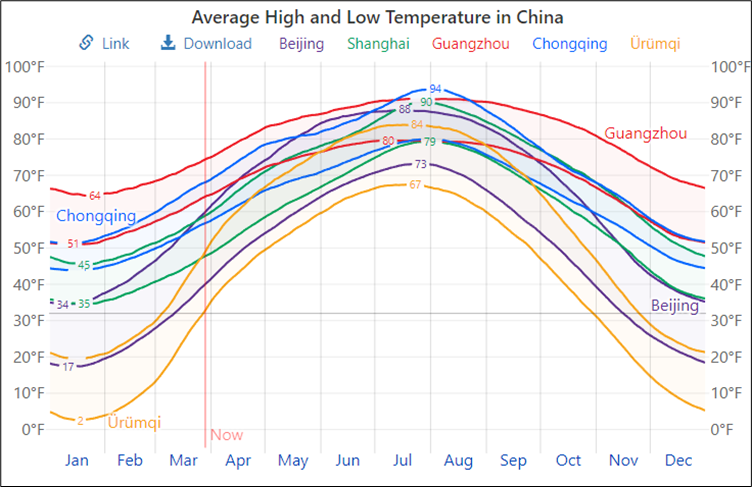
Furthermore, you had a big run up in the China reopening trade as the market tried to front run it, and now specs have mostly capitulated on that, too. Q2 and Q3 are likely to be the window where China reopening is real. Chinese travel should pick up as the weather improves (see chart below) and outbound flights resume.
Keep in mind that outbound flights from China are still only running at 15-20% of pre-COVID levels even as online searches are closer to 80% of 2019. There isn’t even a direct flight from Beijing to Heathrow right now. Slowly, staffing and flights will return to normal. That will be the reopening people have been waiting for.
Anyway, many signs point to lower EURNOK and the entry point is nice. You can do spot with a stop loss at 11.5610 or you can buy an option. I like the option because 1-month vol is mid-range and everything I’m looking at suggests this is a one month trade. The seasonality suggests a bottom mid-April and my “Sell EURNOK when Sharpe is high” backtest is optimal around 1-month out. Optimal strategy, I think is to do half spot, half option but they are similar strategies. Here’s the exact view:
50% Buy 1-month 11.10/10.90 EURNOK put spread for ~34bps off 11.31 spot. EURNOK options are not megaliquid so this is ballpark. Check your option guru for accurate pricing.
50% Sell EURNOK here (11.31) with a stop at 11.5610 and take profit at 10.9150.
There is an S&P beta to EURNOK and to be completely honest, I have absolutely no view in SPX. It has been oscillating around 4000 for so long that I feel disoriented. You can only argue ERP and valuation stuff for so long before it feels stale. Short-term you have Retail Sales tonight and FX Purchases data 03/31 at 4 a.m. NY.
USDJPY
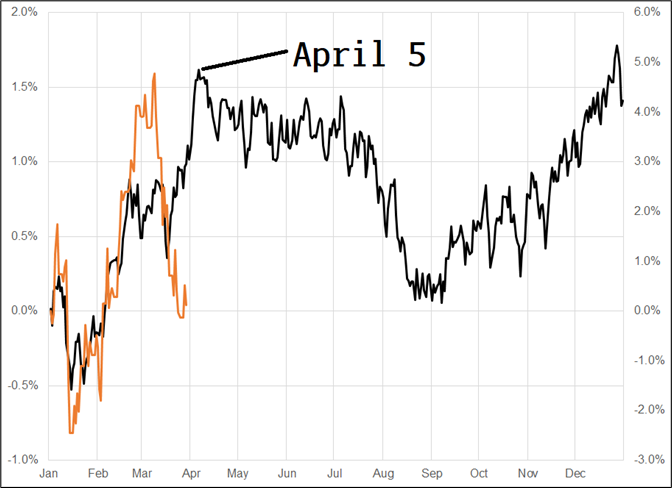
USDJPY followed the seasonality perfectly this year, right up until the last two weeks or so. This is encouraging for the short USDJPY trade as it shows the Japanese year-end seasonal flows are more than offset by the big drop in US yields so far.
When bullish seasonality expires April 5, that should make it easier for USDJPY to go down. Note of course that 04/05APR are the big ISM releases so there is trapdoor potential for the pair if the data is severely impacted by banking stresses over the past few weeks as business managers predict tighter lending will hurt their biz.
USDJPY average seasonality (L y-axis) vs. actual performance this year (R y-axis)
Final Thoughts
Nice article on bias and baseball umpires. https://betterletter.substack.com/p/the-umpire-strikes-back
And a stimulating podcast with three of my favorite big minds. One of those “I understand about 35% of this, but that’s OK” kinda things. https://tim.blog/2023/03/23/david-deutsch-naval-ravikant/ HT SB
Enjoy your day.
good luck ⇅ be nimble
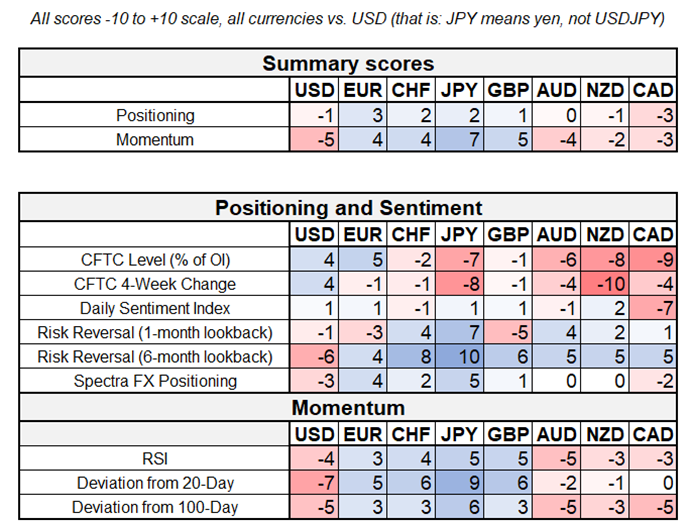
The Spectra FX Positioning and Momentum Report
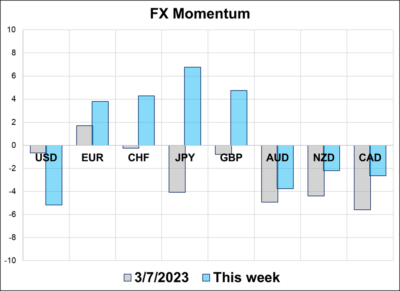
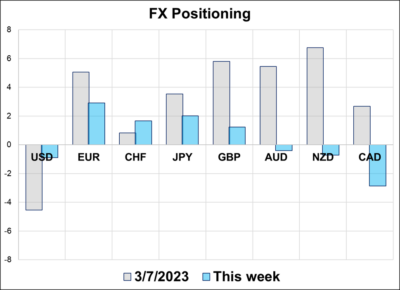
It’s been a while since we had up-to-date CFTC data but they have fixed their technical issues and we can now present a clearer view of positioning. While dollar sentiment has turned meaningfully bearish in recent weeks, positioning has failed to keep up as speculators have been more concerned with specific issues like exploding rate markets, crumbling bank equities, and still-sticky inflation. Global macro traders have not had a chance to put on short USD vs. G10, even though most believe that is the path of least resistance.
G10 FX Positioning and Momentum
Five Observations
1. JPY positioning remains bullish but moderate. At Spectra, we have seen meaningful volumes of downside USDJPY (for example, 3-month 125 digitals, etc.) but interest has been moderate relative to the level of sentiment. That is, while people believe in the trade, they are not fully invested in it. Meanwhile, the CME continues to run a short JPY position as carry considerations there outweigh what looks like a change in trend. There is no denying that the carry and the skew in options make USDJPY downside challenging. That said, there is no free lunch and when USDJPY starts zooming lower, it often outperforms what is priced in by the options market.
2. Long EURUSD is the other trade that has picked up steam in recent weeks, but again the level of involvement is moderate at best. Traders are simply not that focused on G10 FX right now and this has kept participation down. The biggest pushback against long EUR is that a full-on banking crisis will deliver a liquidity shock and that will push us to the USD-bullish side of the USD smile. The market is eagerly watching all credit and deposit indicators from here to see if the USD-negative view of a less-good USA with Europe and China doing OK prevails… Or if this ends up as something more dangerous.
3. The Economist did its best to put a bottom in the US regional bank story on March 18. This is the fifth straight bearish-leaning Economist cover (counting only covers that reference an asset market), following bearish covers on inflation, Europe, Crypto and US housing. The previous four covers saw nearly instant rallies in the associated asset class with TLT, EWG, bitcoin and XHB all skyrocketing immediately after the cover’s release. KRE (the US regional bank ETF) was trading 43.87 when the cover came out and currently trades around that same level.

Also… Does it seem odd to you that there is no question mark on that headline?
4. Fed cuts priced in the market continue to reflect not the modal outcome, but the distribution of probabilities where you might get a hike of 25bps but you could also get a cut of 50-100bps if things get markedly worse on the credit side. At our London dinner last week, half the attendees thought the next move from the Fed would be a hike while half thought it would be a cut. That’s a rare situation. Normally we are debating how many cuts or how many hikes, not which policy change direction comes next!
5. The market is tired and has derisked following the epic blowout in US rates. There is a ton of ammo to jump on any clear narrative that emerges as we are currenlty in a regime where there is barely a narrative at all. Crickets for now, but that never lasts long.
That’s this week’s report. Thank you for reading.
https://twitter.com/Dalle2Pictures/status/1553712964590600193
Painting of Post Malone, by Vermeer, Dutch Golden Age
Remember Post Malone’s epic Nirvana tribute…
…in the darkest depths of COVID?
Click here to subscribe to am/FX
More recent posts



Rabbit Holes
CAD and Rabbit Hole #18
This piece is mostly for people who are interested in backtesting
Subscriber-only
France, stocks, USDCAD
This could be a consolidation week as crosswinds now blow in FX and equities