I think the EV of short USD through PPI and Retail Sales is high.
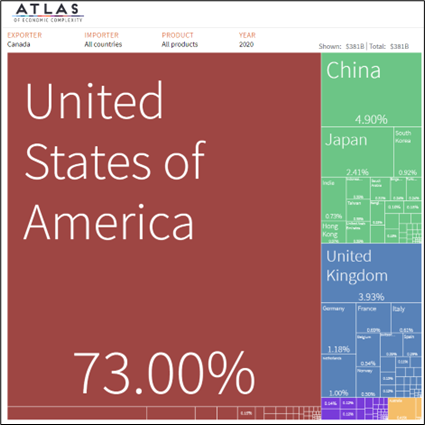
Canada’s exports, by destination
The Atlas of Economic Complexity
is a useful resource.
Fun to play around with, too.

I think the EV of short USD through PPI and Retail Sales is high.
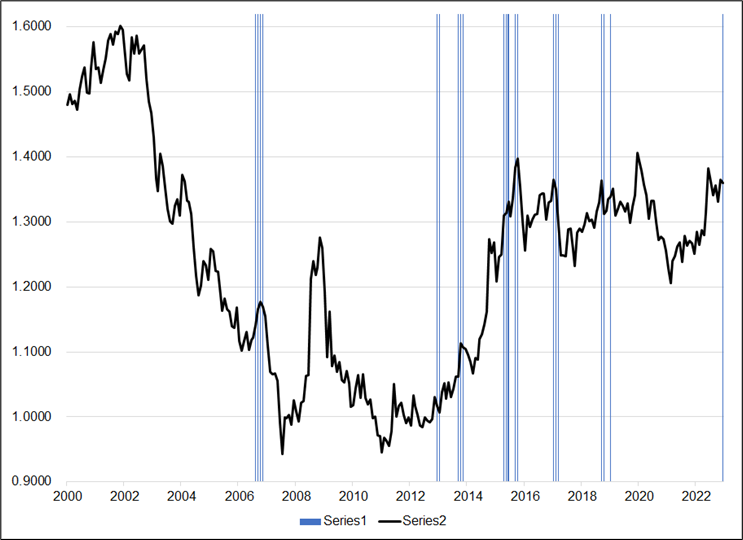
Canada’s exports, by destination
The Atlas of Economic Complexity
is a useful resource.
Fun to play around with, too.
20JUN USDCHF
0.8850 digital put @ 20%
spot ref. 0.9275
21JUN USDJPY
123 digital put @ 20%
spot ref. 131.30
April 12, 2023
Decent reaction in FX to a small miss but I think it makes sense as the market wants to take the USD down. This is logical with PPI tomorrow and Retail Sales Friday. I would suspect both those figures will be weak. PPI because goods and shipping prices are collapsing and the other PPIs around the world have already come in weak (China, Norway, etc.). Here’s China PPI vs. US PPI.
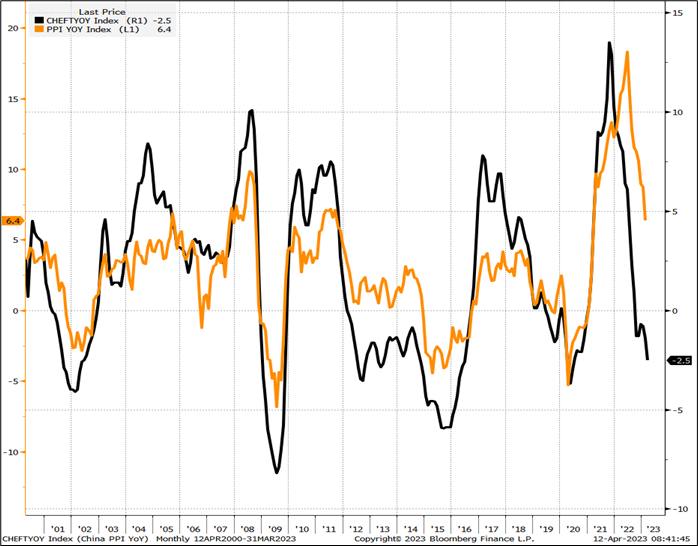
It’s logical that global PPIs will track somewhat because many of the inputs are the same. Global PPIs are more correlated than global CPIs. Also note in the last two years, the US CPI miss has been in the same direction as the PPI miss 10 times, and it has been the opposite way 4 times¹. Betting on a weak PPI looks like high EV to me.
Friday, the Retail Sales data for March look set for a weak lean on giveback after JAN/FEB strength as most of the private credit card data showed weakness.
The data continues to point to a disinflationary slowdown in the USA, despite the strong NFP release last week. Deceleration is happening but we don’t yet know if it’s a hard stop or just a slowdown. I think it’s a good plan to stay short USD through Friday, then reassess the situation after Retail Sales.
—
¹ The remaining 10 months, one or the other was: as expected.
There is a striking divergence between USDJPY and USDCHF these days as the market has positioned for USDJPY weakness but hasn’t been involved in USDCHF.
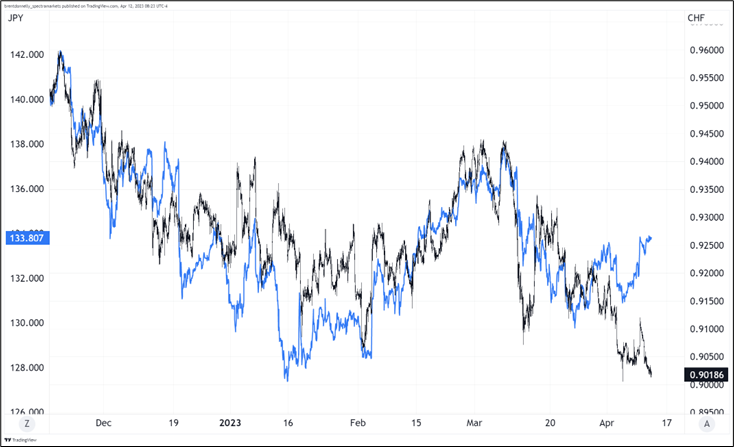
Sure, CHFJPY is a thing, but I think this is more the result of excessive positioning in USDJPY and we have probably cleaned out the weakest USDJPY shorts for now. Again, USDJPY holds the range high 134.00.
Goolsbee’s speech was a good read yesterday. He was dovish and suggested that tighter lending is the equivalent of somewhere between one and three 25bp rate hikes. To me, May looks overpriced at 69% as Goolsbee’s arguments are solid and he might be able to sway the committee. Here are a few key paragraphs from the speech.
Even financial stress that doesn’t spiral into a crisis can still lead to a pullback in credit and have a material impact on the real economy. The research is full of studies showing this across countries and across time. In U.S. history, think of the fallout from the savings and loan restructuring in the 1980s and 1990s. It didn’t spiral into a systemic crisis, but it made the 1990–91 recession worse and significantly slowed gross domestic product (GDP) growth in the subsequent recovery…
… Today we do not face a common problem found in many earlier times of financial stress: Our financial stability goals and our monetary policy goals do not conflict. Often, moments of financial stress happen when the macroeconomy is struggling. The kinds of actions that financial institutions need to take—or that the Fed or other regulators require them to take—like tightening lending standards or conserving and raising capital may strengthen the banking sector, but also reduce the availability of credit when the economy cannot afford to get slowed down.
At present, we do not face this dilemma. Actions that strengthen the banking sector’s financial position and reduce the likelihood of additional financial problems currently make the job of monetary policy easier—they tighten credit and help bring inflation down.
I suppose there is justification for a final, token hike in May. But it’s also possible Goolsbee has a bit of clout.
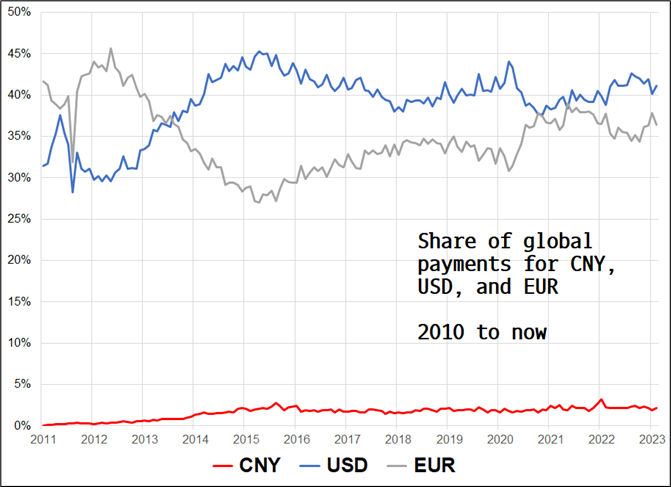
“Dedollarization” update:
Have a milky day.
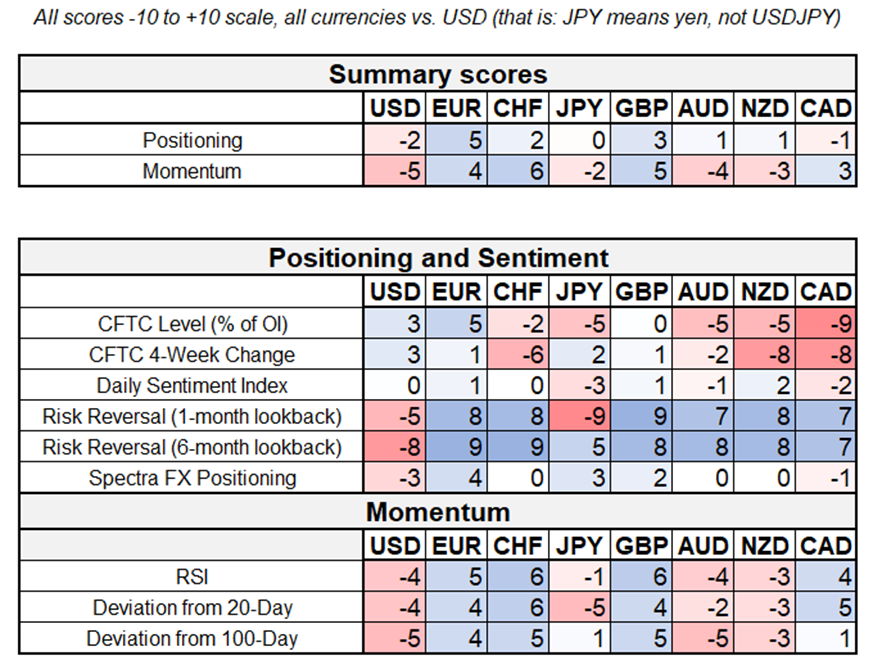
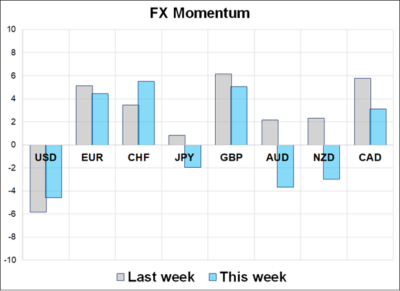
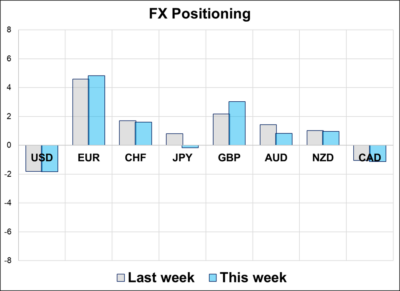
Sluggish US data hasn’t been bad enough to put a meaningful dent in the USD. Nonfarm payrolls reversed the USD downside momentum and a brief USD+++ freak out on Easter Monday forced some of the weakest USD shorts to cut cash. Overall, not much has changed this week as positioning remains medium long EUR and small short USD.
1. What is the CFTC seeing that nobody else sees? The futures positioning there shows CTAs adding to already large CAD shorts as they simultaneously trade max short equities. Kind of odd given there is absolutely no momentum in either USDCAD or stocks.
Extreme readings in CAD positioning on the CFTC have been ambiguous signals. There was one incredible run where the CTAs were mega long USDCAD for years and caught the trend (2013-2016), but the rest of the instances were the worst possible times to be long USDCAD (2007, 2016, 2017, 2019). Here is the chart.
2. Long EURUSD remains the favored USD short. Current positioning level +5 is about as high as we have seen in any currency this year as the market flea hops from narrative to narrative. Levels of positioning not yet scary.
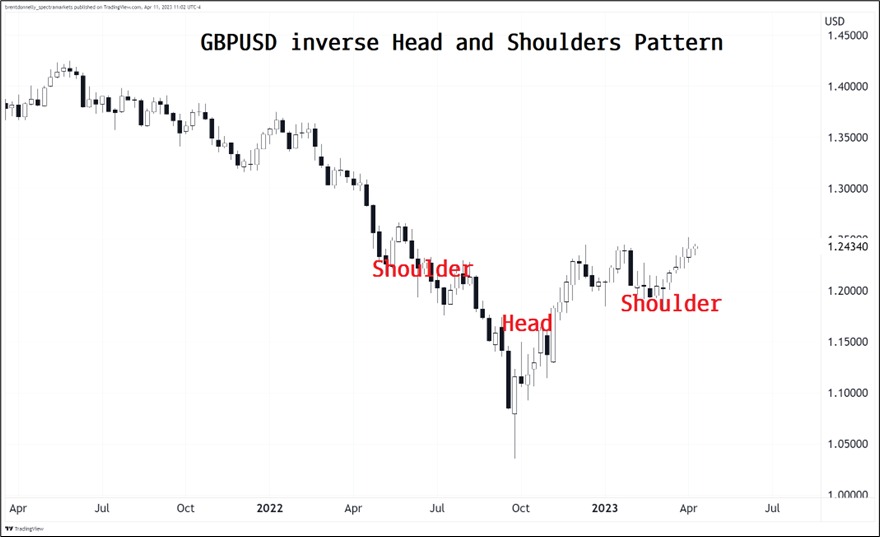
3. GBP positioning is more bullish. GBP price action has been the main determinant of positioning for ages and now as we climb through some old highs, the market is taking notice. Cable is tracing out a wonky inverse Head and Shoulders pattern, but the neckline is arbitrary and there is no clear breakout until Betty eclipses 1.2650/60. No narrative is good news for Cable.
That’s this week’s report. Thank you for reading.


A sort of almost unbelievably large move in Brazil. Plus: Short CADJPY.

NZD has a bunch of bullish kickers: Election, seasonality, and inflation