Yields can’t stay in this tiny range forever.
Do you know what country
just passed the 40 million
mark in population?

Yields can’t stay in this tiny range forever.

Do you know what country
just passed the 40 million
mark in population?
June 27, 2023
There was a typo in the first line of am/FX yesterday, but hopefully the message was clear: Seasonality points to lower yields in July but I’ve abandoned my lower yields view despite the seasonality because housing, rents, and spending still look well-supported and I’m no longer convinced this drawn-out range trade in yields will resolve to the downside. Here is the chart:
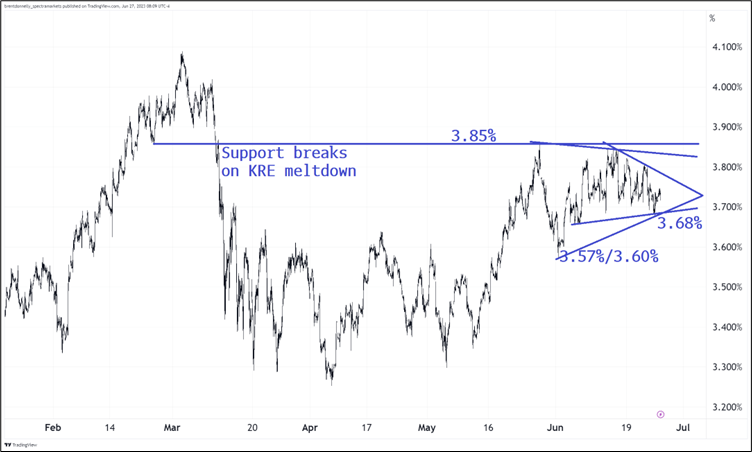
We have not had a daily close outside 3.60%/3.85% since mid-May and if you zoom out a bit, you can see just how narrow this consolidation has been:
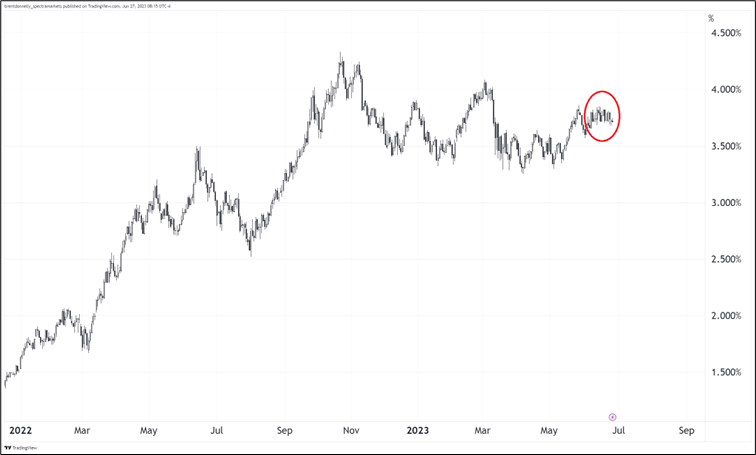
Proximate catalysts for a break include today’s Consumer Confidence (probably won’t matter, but I would lean toward a strong number, maybe 106, or so, given the state of the stock market and real estate). Core PCE and Initial Claims later in the week are more likely to move the needle.
The definitive break higher in yields comes on a close above 3.86% in US 10s. With the BOJ refusing to participate in global normalization, a rise in yields could quickly bring 150 USDJPY and MOF intervention back into the conversation.
The fate of short-term USD direction will be decided by the direction of the break of 3.60/3.85.
If you think yields are going to take out the topside, it’s worth owning 1-month 148.50 calls in USDJPY because that level will be extremely tradeable as intervention fear will rise and price action will get mega sloppy as 150 nears. Just like last time up there in October 2022. 1-month 148.50s are the 10-delta and that does not seem all that far away to me.
One small mystery in the market was the question of why gold ripped when M2 ripped higher, but hasn’t collapsed on the drop in M2. I think I have come upon the answer: Year-over-year is so badly distorted by base effects that it has completely lost its meaning in this case. When something skyrockets at a never-before-seen rate, it’s going to come back down at a never-before-seen rate. So, while the YoY M2 chart looks scary, the 3-year change chart looks like something that was massively distorted higher by unprecedented MMT-style money injections and is now reverting to the mean.
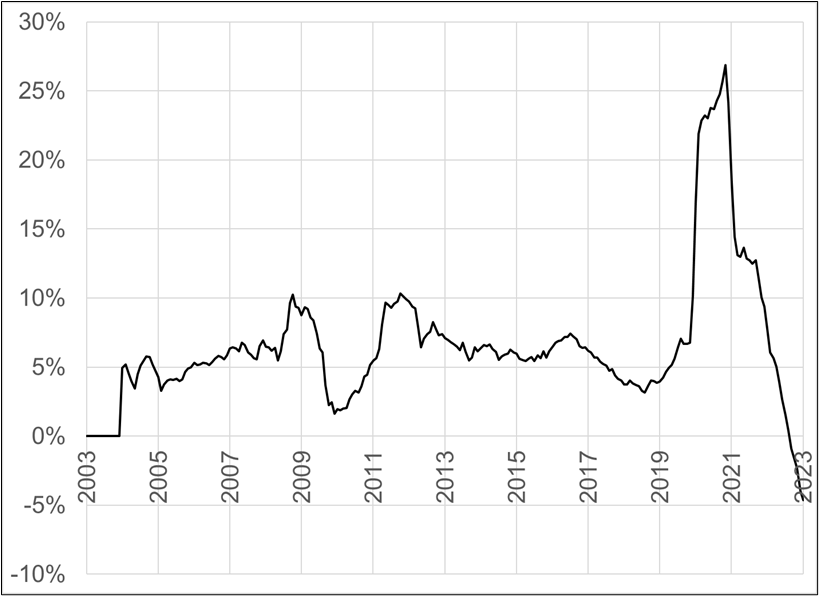
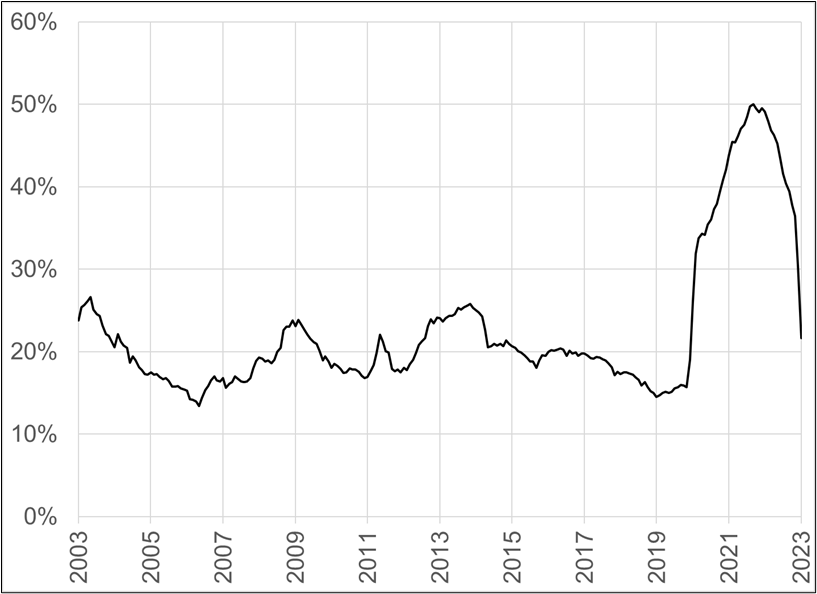
There’s also the simple fact that gold and M2 aren’t that correlated, of course.
Anyway, M2 isn’t that scary, it’s just back to trend.
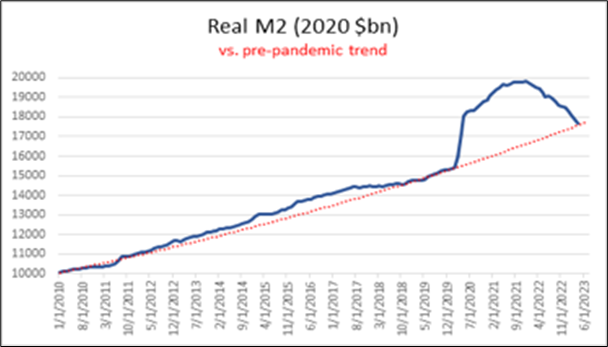
https://twitter.com/briangobosox/status/1673489269279563777?s=46&t=Z-boW5UHRWKGTmYteOnSkA
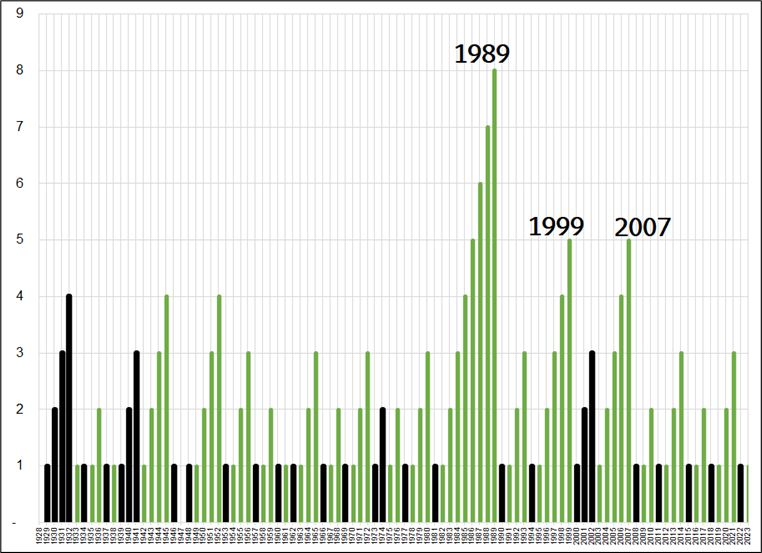
Someone asked me to make this, so I did.
You have probably gleaned that I’m a little light on FX views here as I wait for the break in yields, one way or the other. I continue to believe EURSEK has a date with 12, barring some epic policy announcement from the Riksbank. The China narrative has gone quiet, and carry remains king. GBP positioning is extreme long (see positioning report, next page) but I don’t see a catalyst right here right now that makes me want to take the other side. Short GBP is definitely on my radar, though.
NYT (gated): Your Brain Has Tricked You Into Thinking Everything is Worse.
This is not finance-related, though it tangentially relates to speculators’ unrelenting negativity bias–and negativity bias in the media at large. It’s interesting and short. Free version on Bloomberg: {NSN RWK4UATP3SHS <GO>}
Make sure you scroll to the end (after this week’s Positioning Report) to see an absolutely insane chart of population growth in the USA vs. Canada.
Have a tragically hip kinda day.
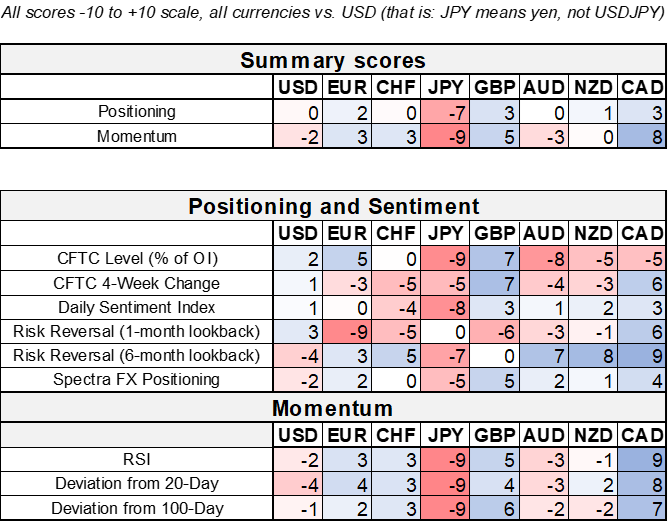
Hi. Welcome to this week’s report. The big central bank meetings have come and gone and the China narrative has come and gone and come again and gone again. And here we are. Carry is king, the dollar is mixed, and the half-life of most themes remains measured in days, not weeks. The full data grid appears after the observations, as usual.
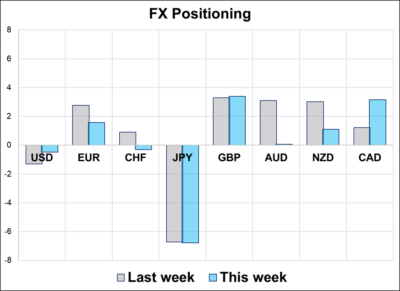
1. The most interesting development in FX positioning this week is the huge jump in CFTC GBP longs. Here is a chart of weekly changes.
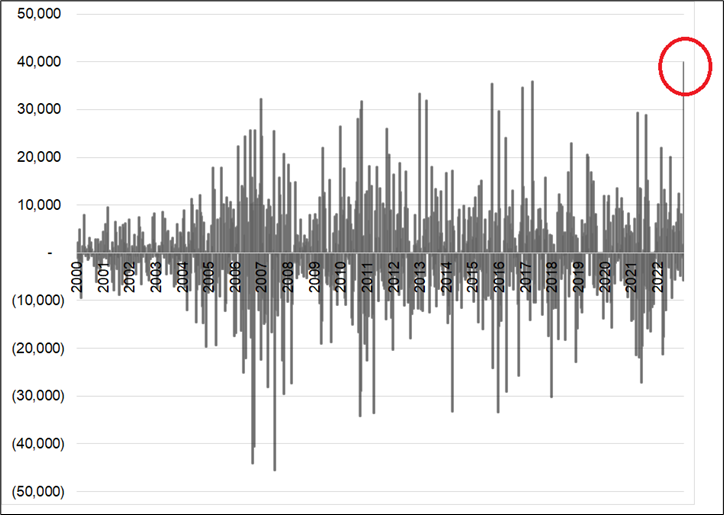
This is the largest 1-week change ever in GBP positioning and brings overall positioning into the 95th percentile at +46,608 contracts. As a general rule, CFTC positioning is directional and trend following, but GBP at these levels of positioning is a rare exception. Here is how GBPUSD performs when GBPUSD longs are >35,000 contracts.
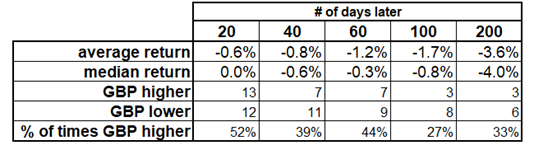
Performance measured from the Friday close, when CFTC data is actionable
2. The other standout on the grid is the positioning in USDJPY. Long USD, short JPY as another BOJ meeting comes and goes without any action from Ueda-san. As carry is hot across the board (MXN, BRL, etc.) the market cannot resist the lure of JPY as a funder. The MOF has taken a few soft jabs at USDJPY on the break of 140/142, and with cross/JPY ripping and USDJPY decoupling somewhat from flattish US yields, the intervention warning system is probably almost, but not quite at yellow. A retest of the 150 area will almost certainly bring intervention again, but that’s 650 points from here and in the interim, this is an interesting place to own gamma as the moves tend to get sloppy in both directions as the intervention zones near.
USDJPY positioning tends to be directional and trend following until an exogenous event like a giant yield move or a policy change or FX intervention intercedes.
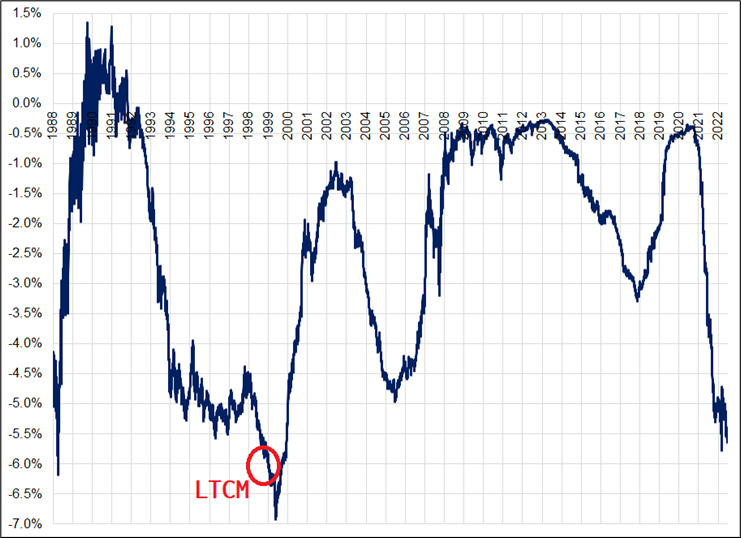
With spot USDJPY at 143.50, you can buy it 1-year forward at 135.50. That is historically spicy, as you can see here. Short USDJPY has rarely been more expensive. Long USDJPY has rarely been so delicious. The last time it was this delicious, Long-Term Capital Management was doing backflips but ended up landing in an empty swimming pool as MOF and Federal Reserve USDJPY selling intervention absolutely bludgeoned it from 148 to 112 in two months. I’m not suggesting this setup is similar; I’m just waxing nostalgic.
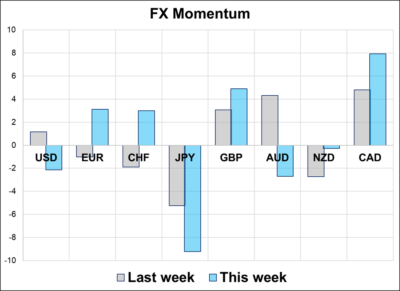
3. The market is capitulating on the bearish CAD story. As the Bank of Canada has unpaused their rate hike cycle and CAD shorts were plentiful as USDCAD neared the bottom of what was a 1.32/1.37 range… There has been significant CAD to buy vs. USD, JPY and EUR. CAD momentum is strong and this is forcing CTA’s to cut some of their long-held short CAD view, too. The evergreen bearish fantasy of a Canadian housing collapse is delayed for yet another quarter or two but I’m sure the market it will try it again at some point as the feedback loop seems to be that hikes will continue until housing breaks. It looked like we were there a few times, but clearly we are not. The dismal performance by crude oil has lost its edge.
—
That’s this week’s report. Thank you for reading.
https://www.statcan.gc.ca/o1/en/plus/3861-40-million-strong-canada-reaches-new-population-milestone

This piece is mostly for people who are interested in backtesting