A three-handed view
From Twitter:
“my roommate purchased a smartphone-sized slab of obsidian and has been holding it instead of her phone to reduce screentime.”

A three-handed view
From Twitter:
“my roommate purchased a smartphone-sized slab of obsidian and has been holding it instead of her phone to reduce screentime.”
Short EURJPY @ 184.80
Stop loss 186.37
09SEP USDCNH call spread
6.7300/6.7400 for 42 CNH pips
Risking 42 to make 58 off 6.7430 spot
10SEP CHFJPY put spread
199/196 for ~37bps off 200.50 spot
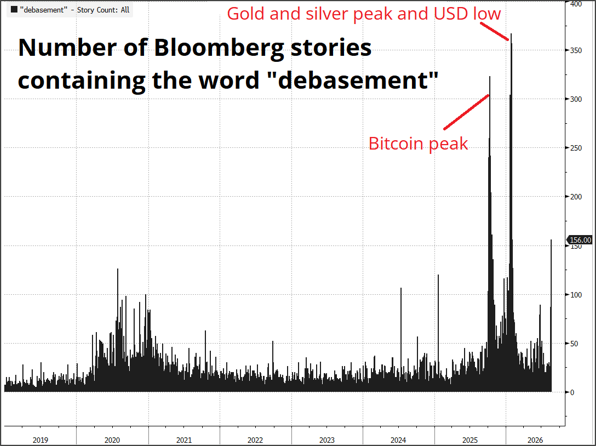
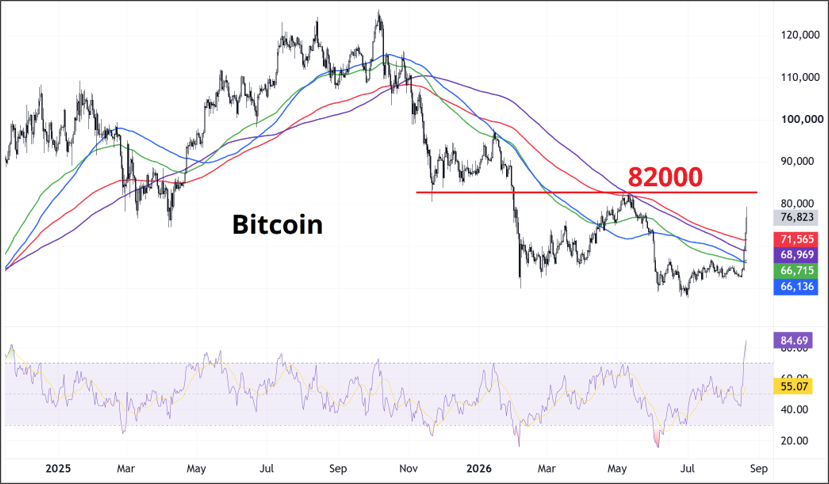
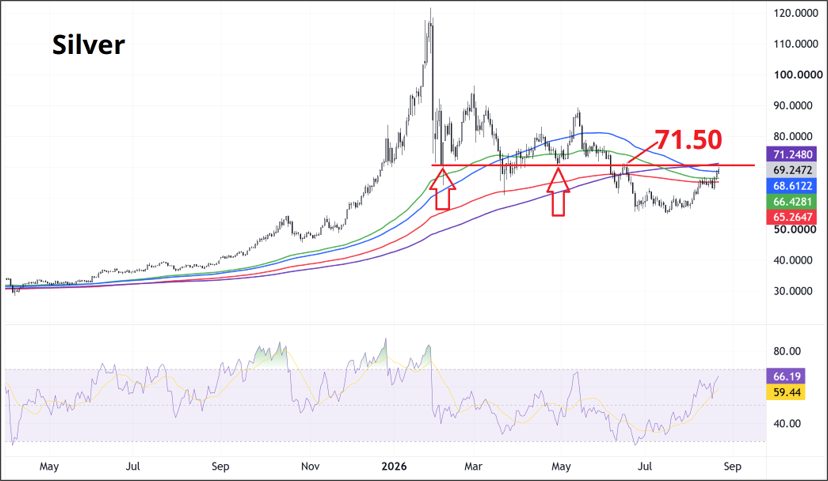
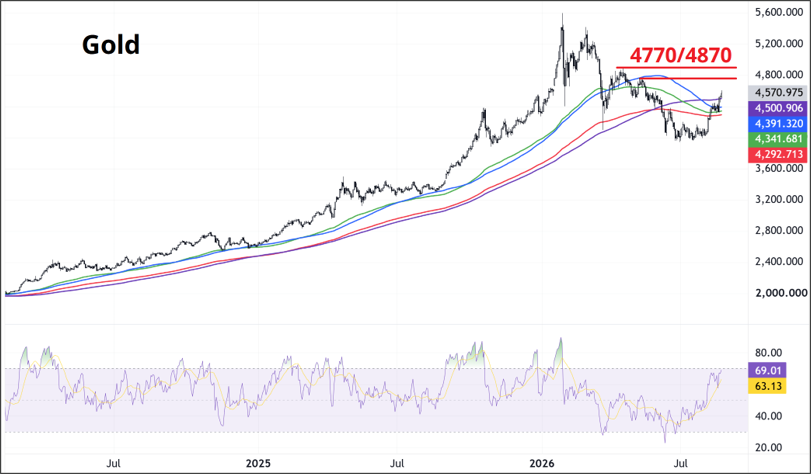
The market was asleep and has now woken up. The debasement trade peaked between October 2025 (bitcoin) and January 2026 (silver, gold, and USD) as the market went into a full bubble, twice, in a panic over the end of the USD. That story ended with a bang as silver and bitcoin lost half their value in a few months and were both left for dead.
Now, a potentially unforced error by the U.S. Treasury has jolted confidence and triggered the raging return of the debasement trade. The vol-of-vol in bitcoin is off the charts and gold and silver are lurching higher after months of bottom building.
While my first reaction to the Bessent announcement was that it’s a big deal and so I bought bitcoin and sold USDCHF… I am having second thoughts at this point. Instead of committing to a single view, I am going to lay out the scenarios and keep an open mind. The period into and after Labor Day tends to be one where hedge funds and real money come back from holiday and pile in to a shortlist of the sexiest themes. Will “the return of the debasement trade” be one of them?
Scenario 1: The market is correct to latch onto this move by Bessent as a moment where the government blinked and revealed a preference to cap yields. This scenario does not require a ton of explanation because you can simply extrapolate from the recent moves. USD down, EM stronger, gold up, silver up, crypto higher.
In this scenario, fixed income shorts pay tons of negative carry and get no love as every major probe lower in bonds is volleyed back by government headlines. 10-year yields are right at the top of the range that has dominated since 2023, and it is not crazy to think that Bessent’s nudge buys a bit of time for bonds to find a bottom. Slower AI capex growth and coming fiscal drag combine with low population and job growth and rising mortgage rates keep the Fed on hold and yields roll over organically.
Scenario 2: The boring scenario: the announcement is irrelevant. Bessent sharply criticized Yellen for precisely this type of active treasury management in 2024, saying she was simply trying to bolster the economy ahead of the 2024 election. In a choice that must be a troll of sorts, the end date for the new operation is the day after midterms. The point here, in scenario 2, is that the US Treasury signaling it will backstop the long end is not really news, and it is hardly surprising. And the amounts are tiny. So if the signal is just policy continuation, and the flow is de minimis: What are we getting so excited about?
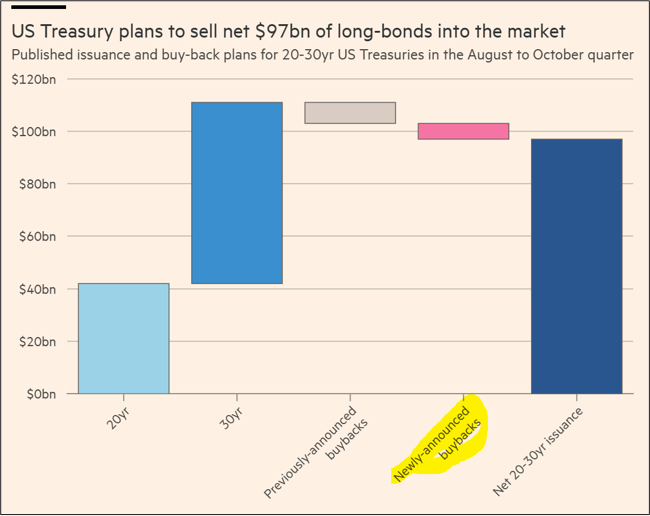
Graphic is from the FT via Pierre N.
In this scenario, we quickly move on from this week’s cacophony, and the USD and U.S. bonds go back to listening to macro and economic signals, not structural policy bias. Financial repression and fiscal dominance are nothing new and they are always lurking in the background as excuses to be short USD and long gold and long bitcoin. But much like the way AI capex issuance is bearish bonds—but barely tradable on any time horizon—the structural debasement / fiscal dominance themes are great for buy-and-holders and podcasters and bloggers, but much more difficult for anyone with a time horizon under three years.
Long story short on scenario 2: Bessent’s actions reinforce structural themes, but those themes are not new and there is no proximate catalyst to trigger the next leg of the debasement trade. The bitcoin shorts have been obliterated, the gold longs are fully loaded again, and we already knew the U.S. Treasury gets itchy every time yields make a new high. Trade the cyclical stories and keep the structural story in the back of your mind.
Scenario 3: Bessent has made an important tactical error and opened a can of worms by attempting to draw a line in the sand. Sure, bonds were selling off, but Bessent has poked the bears here by claiming that yields are out of equilibrium and big government knows best. He has created a situation where some cohort of traders are buying ahead of an implicit backstop while others are skeptical and waiting for any sign of weakness to pile on. If U.S. 10-year yields take out 4.75% (pre-Bessent high) and scoot towards 5.02% (the 2023 high), the administration will need to three-bet the market’s raise.
Either way, bond market volatility picks up and term premium expands as rising uncertainty over Treasury and Fed policy spooks investors. The Fed is saying one thing “let market signals reign!” while the Treasury is saying the opposite “market signals are not to be trusted and are currently out of equilibrium”. This lack of policy coherence, along with random policy shocks from war and tariffs, could lead to higher yields. First do no harm, they say. Maybe Bessent would have been better off leaving things alone.
Scenario 3 will see some unhinged days like we witnessed in 2022/2023. Days where yields make new highs and bond market vol is high and stocks swoon and financial conditions tighten. And this could all be happening in the context of an economic soft patch as fiscal drag begins and AI Capex growth peaks. Not ideal.
My best guess is that the three scenario probabilities are something like: 20% 50% 30%. That is, I think there is a very strong chance that these epic moves in the USD and gold and bitcoin will cool substantially from here and if you were long bitcoin at 64500, you are better off taking profit at 77k, not doubling down. Not to mention the fact that part of the rally in crypto was driven by statements from a White House that will completely lose interest in HYPE, BTC, and CLARITY in a day or two. We have seen this “Government Pumps the Coins” movie a few times. I find it extremely hard to believe that the president truly cares (for example) whether HYPE is onboarded in the United States, or the CME and NYSE prevail. Words and actions are not correlated.
I realize that laying out three scenarios is less fun than presenting one strong view. But I don’t have a strong view right now. All three scenarios seem reasonable to me. The market loves a structural USD bear and debasement story, and has attacked it with rabid fervor here again, but structural stories are only really tradable when the cyclical story aligns. Fed on hold and eventually cutting rates, a Q4 soft patch, and debasement fever is probably a pretty reasonable outlook. But at these prices, I would rather wait and see for a bit.
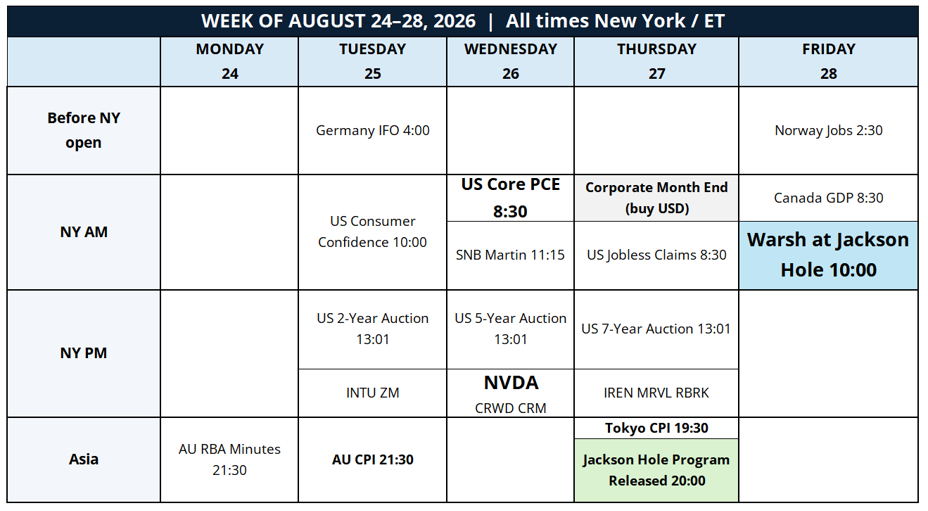
The calendar remains a tad thin next week, and it feels to me like the market has spent a decent amount of mental and real capital on this week’s news. That leads me to believe that we will get a quiet week next week as Core PCE is unlikely to surprise and Fed policy has lost a bit of relevance as it’s really movements in 10s and 30s that matter right now. Note the Jackson Hole program is expected at 20:00 on Thursday night. Sometimes there are clues in there as to whether or not the speeches will be relevant to markets.
https://www.economist.com/culture/2026/07/30/how-to-spot-ai-writing
From Twitter:
“roommate purchased a smartphone-sized slab of obsidian and has been holding it instead of her phone to reduce screentime.”
Obsidian is an extrusive igneous rock, though it is specifically a natural volcanic glass.

This piece is mostly for people who are interested in backtesting