
There are two ways to frame Fed policy
highlights
Economics vs. Credibility
Current Views
09SEP USDCNH call spread
6.7300/6.7400 for 33 CNH pips
Risking 33 to make 67 off 6.7430 spot
10SEP CHFJPY put spread
199/196 for ~37bps off 200.50 spot
MP debate heating up
The U.S. monetary policy debate is hotting up (as they say in the U.K.), and as usual everyone is cherry-picking the data that suits their view. For example, yesterday, the hills were alive with the music of 3-month annualized CPI and how it’s now fallen to 1.6%. The problem with 3-month annualized anything is that three months is not a worthy sample size for any data series, really.
One particularly useful feature of YoY figures vs. 3-month is that they wash out residual seasonality. Otherwise, you would think inflation is exploding every year in Q1 and then collapsing thereafter. Second, a single quirk in a single month sends the figure skyrocketing or collapsing. An idiosyncratic move in airfares, lodging, or used cars swings the whole thing. The CPI health insurance component, imputed from insurer retained earnings, then multiplied by four in a 3m annualized figure tells you nothing about current price pressure.
Peek at the chart here and it’s easy to see the places when doves will be reaching for 3-month annualized to support their view and when the hawks will be whipping it out to support theirs. 3-month annualized can help you catch inflection points, but it’s mostly noise in a trend (like, now).
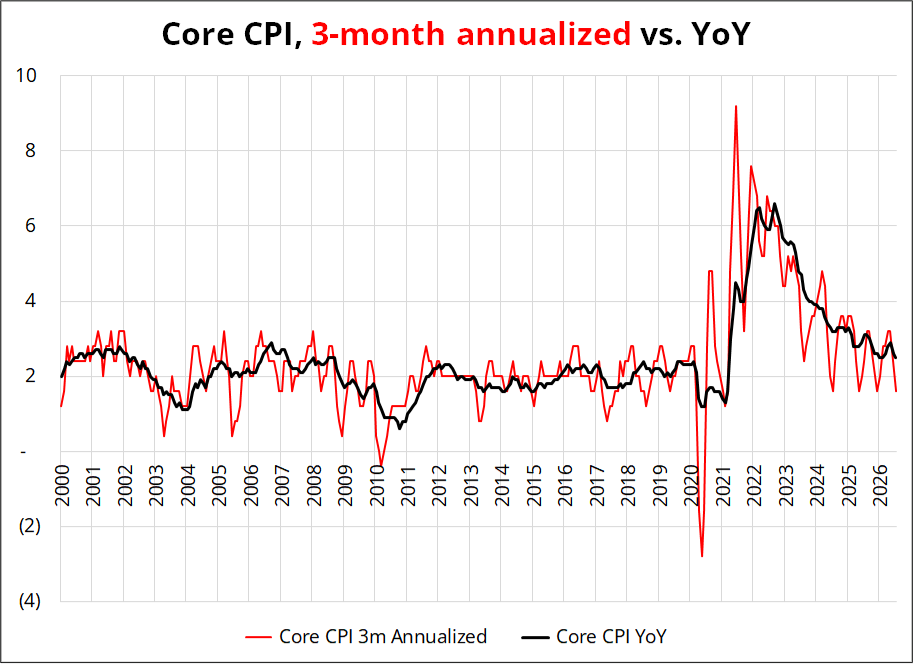
The debate over monetary policy is hotter right now than normal, perhaps because it’s pretty easy to argue for hikes, or on hold, or even cuts, depending on your priors and your framework. If you look at rate of change of inflation (second derivative) you are probably dovish, because inflation is falling. If you look at levels, you are probably hawkish because inflation has been above target for years and remains above target.
If you look at the sum of all the information out there, you are probably more in the “on hold” camp because if a rate hike is that much of a line ball call, and we are talking about up or down 25bps here or there, it’s irrelevant to the real economy and thus the whole discussion is a waste of brain cells. I am more in the third camp, as I believe the labor market is in balance, inflation is in balance and there isn’t much need for any change in monetary policy. First, do no harm.
The best hawkish Fed argument, in my view (and the one that made July FOMC a tough call) is that the Fed needs to hike to re-establish institutional credibility. The Powell Fed burned stacks and then cords of credibility as:
- they adopted a new inflation framework (FAIT) in 2020, just months before the regime it was designed for disappeared, then—whoops—quietly scrapped the framework’s defining feature in 2025.
- Senior Fed officials traded aggressively in their PAs in 2020 while making unprecedented emergency monetary policy decisions; the subsequent investigation found serious conflicts in appearance but exposed ethics rules so weak that the conduct was technically permissible.
- they continued to expand the balance sheet, even when inflation was above 7% in 2022.
- by their own admission: they failed to properly supervise Silvergate in 2023.
- They failed to deliver their stated 2% inflation objective for 64 months and counting.
- repeatedly emphasized a symmetric 2% inflation objective, but tolerated a prolonged and enormous upside miss in a way that would have been unimaginable for an equivalent downside miss. Wildly asymmetric.
So, the decision over whether to raise rates may have more of a strategic metagame aspect than an economic one. We all know 25bps up or down doesn’t matter for the real economy. But it might matter for future cred.
Beth Hammack, are you with me?
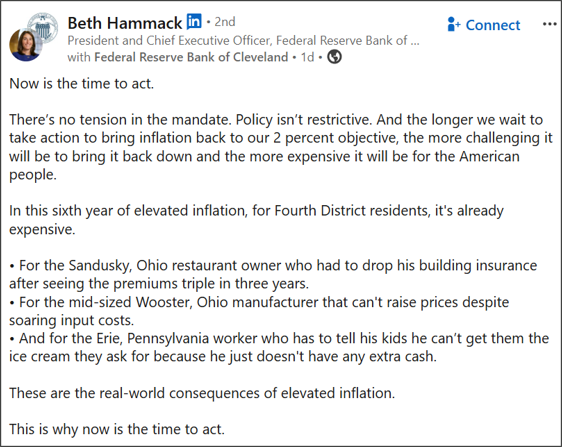
Cleveland Rocks, by The Presidents of the United States of America. Ohio!
Someone on Twitter said the Fed shouldn’t hike because “you can’t change the past” but I think this is exactly wrong. You can slowly reverse damage done in the past by changing your actions in the present and future.
The economic vs. strategic considerations around monetary policy are complicated right now. This is why I got the July FOMC meeting wrong—I thought the strategic/metagame of Fed credibility would outweigh the nerviness around more restrictive policy. The most recent run of data doesn’t clear things up much, though the doves are surely in control for a few weeks as the whiff of weaker data is in the air. U.S. fiscal policy will provide much less of a lift into 2027, and the rate of change of AI Capex is slowing, so in the end, the data will probably bail out the Fed, and they will end up hiking exactly zero times.
USDJPY
My view is that USDJPY rallies into 160.00/50 and fails. Whether that is because the MOF intervenes, GPIF draws a line in the sand, or the U.S. data is simply not strong enough to enable a bigger rally… I’m not sure. But I strongly doubt USDJPY will rip through 160.00/50 with ease. With nothing on the calendar, I continue to favor vol-selling or long carry strategies, and while I know this is kind of boring, it’s the only way to make money with zero catalysts and VIX below 15. Even selling spot USDJPY is tricky given the carry, because your base case has to be that everything goes nowhere until Labor Day.
New subscribers, don’t worry. I am not usually this negative about markets. If anything, I tend to be overly optimistic about how exciting things are about to be. But the current setup is one of neutral positioning, few catalysts, lotta people on vacation, and engagement levels super low. You can either go to the beach with everyone else, scratch out a few good opportunities here and there (short vol, long carry mostly + a few zippy tactical trades like SPCX and hopefully CRWV), or you can overtrade and try to make something out of nothing and drop 350bps in two weeks for no reason. I choose door number two.
With spot at 159.10, there is no strategy or structure that fits my USDJPY view. Selling a 160.00/160.50 call spread does, actually, suit my view, but you’re risking $230,000 to make $80,000 on that and it looks like negative EV to me. So, I will stick with the USDCNH and CHFJPY ideas for now, plus the CRWV long (stop below $100).
Final Thoughts
1. I am in a position of extreme intellectual flexibility right now, which is good. I’m open to pretty much any scenario post-Labor-Day. As new narratives develop, I will keep on top of them. Please let me know if you see any emerging narratives that might be suitable for early adoption.
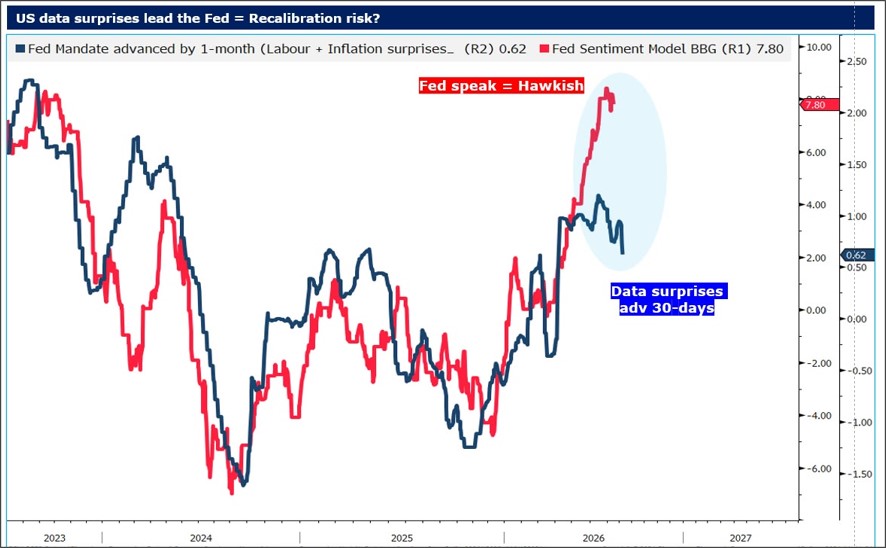
2. Below: a gorgeous and convincing chart from my penpal Mehul Daya at ANZ. Data dependent!
3. Some bad news: There was an explosion at the cheese factory. Da brie is everywhere.
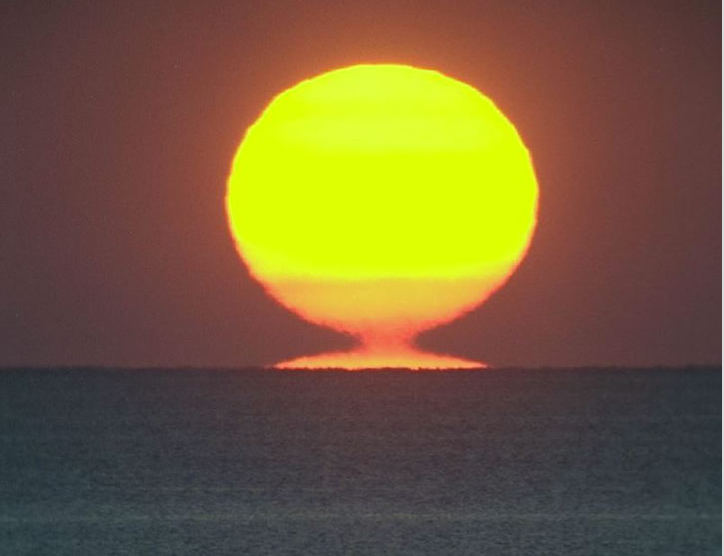
May your day have all the beauty of an Etruscan vase.
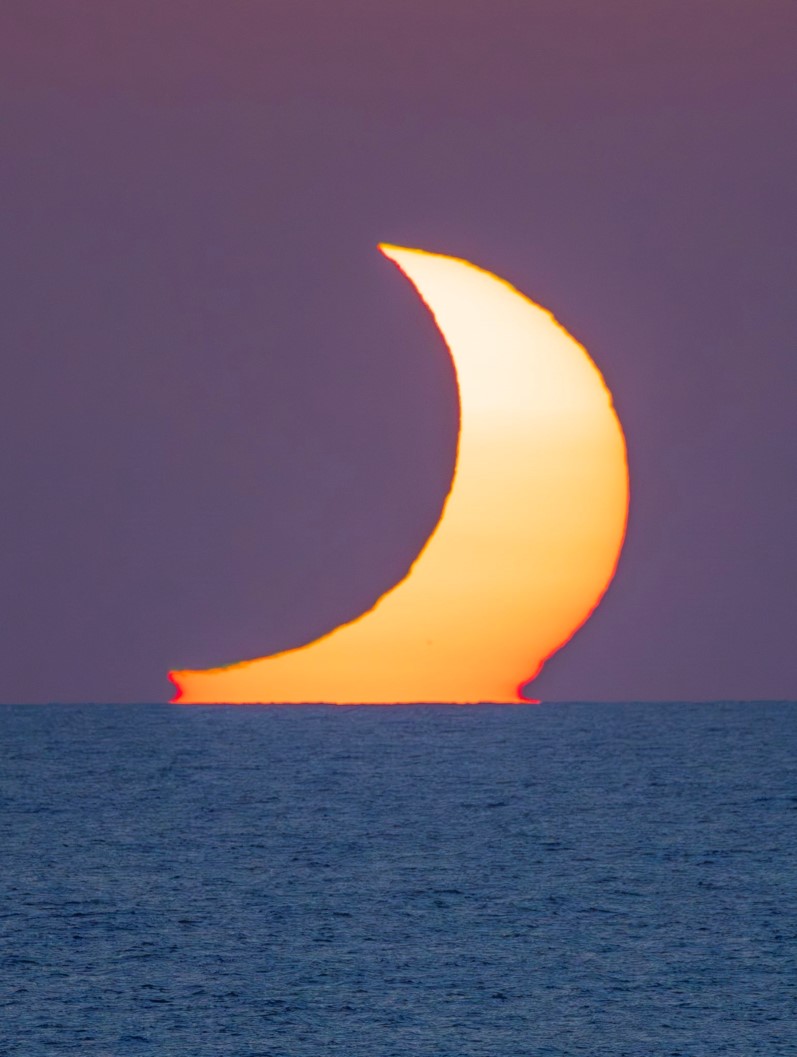
Eclipse at sunset over the Mediterranean Sea
The Sun can look like it’s melting into the ocean because its light is bent by layers of air at different temperatures just above the water. This mirage can stretch and distort the bottom of the Sun into strange shapes, including the “Etruscan vase” or “Omega Sun.” Example here.