Time to step back and take stock
NFL season starts tomorrow.
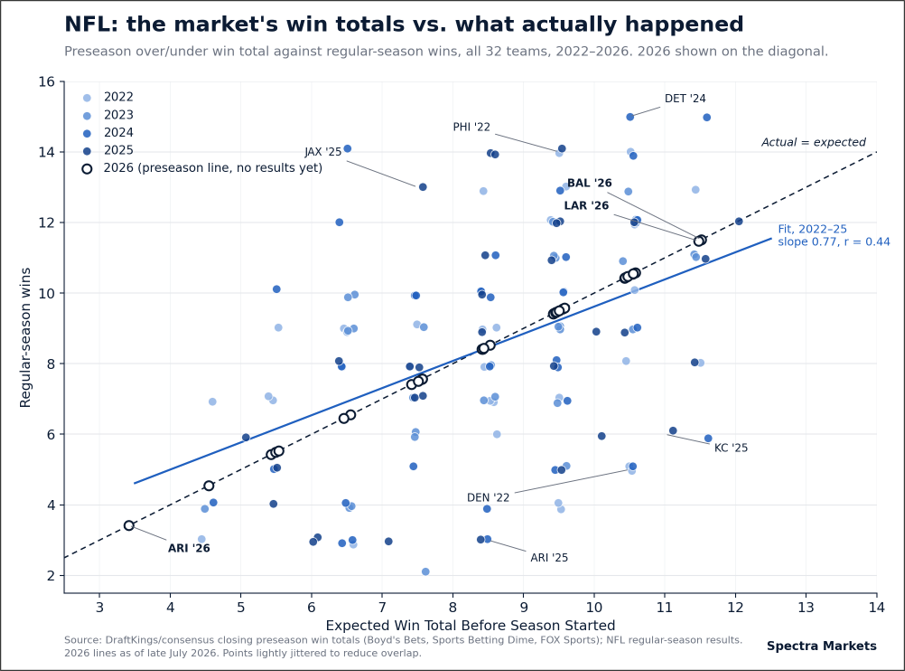
See bottom of page for a somewhat interesting NFL-related graphic!

Time to step back and take stock
NFL season starts tomorrow.
See bottom of page for a somewhat interesting NFL-related graphic!
Short EURJPY @ 184.80
Stop loss was 186.37
Now 183.11
Took profit today at 179.19
10SEP CHFJPY put spread
199/196 for ~37bps off 200.50 spot
Worth 151 bps if nothing insane happens this week.
30NOV Long 1.23/1.25 AUDNZD c/s
vs. short 1.18/1.19 p/s
Cost 2.5 bps off 1.2093
I wrote yesterday that I wanted to cover JPY longs below 177.00 in EURJPY and we got to the high 177s and are now in the midst of a spicy bounce. USDJPY traded on a 152 handle and now it’s 154.30. With Kyodo confirming the September BOJ hike is a done deal, the 155 break in USDJPY attracting a ton of follow through selling, and the GPIF + U.S. pressure story fairly well-known at this point, I am getting nervous about JPY longs in the short term.
The charts of EURJPY and cross JPY all show bullish divergence off oversold.
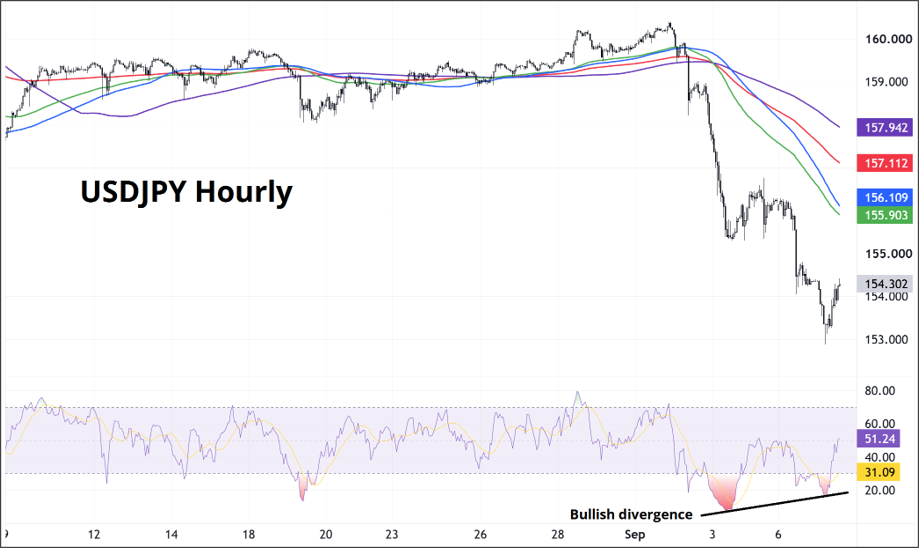
Note how the RSI went to 8 (!) on the first run down in USDJPY, while last night’s low in price did not come close to making a new low in the RSI.
I don’t think we need to skyrocket higher in USDJPY, but a reasonable view here would be that we enter a choppy consolidation 152.00/155.50. See the daily chart next. Note how we got super close to the old 152 double bottom and have now formed a doji-like daily candle at current levels.
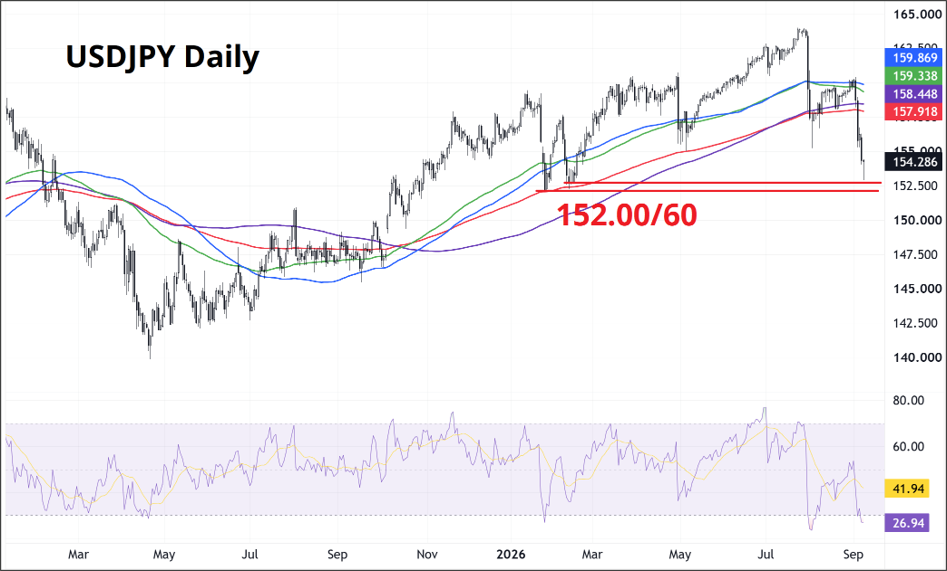
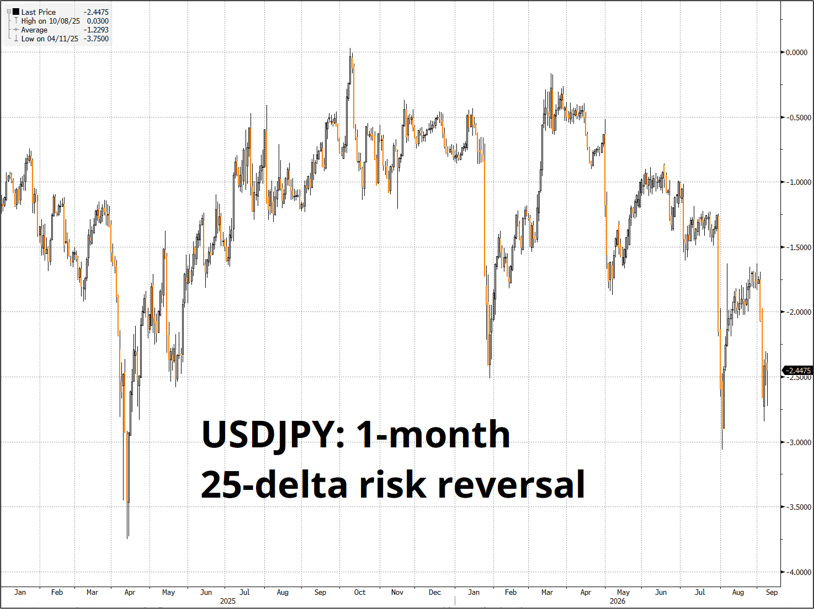
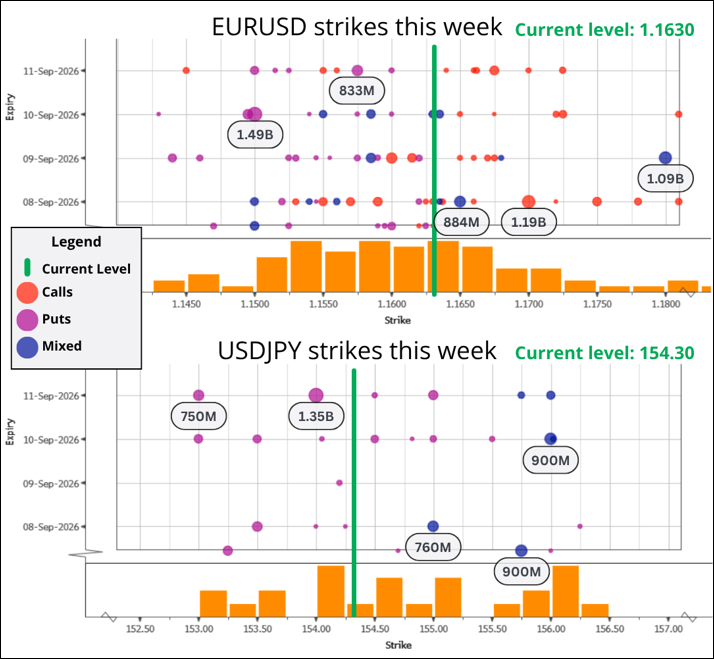
The news flow and order flow have been relentlessly bullish JPY for the past week, but now we are in a situation where vibes have completely shifted, the intervention skeptics and Japan fiscal doom loopers are in hiding, the BOJ is 125% priced for SEP+OCT, and options markets are aggressively bid for puts as you can see here:
Having said this yesterday: “I am essentially positioned for one last huge wave lower in USDJPY and then at 152 USDJPY and/or sub-177 EURJPY I will go to neutral as the policymakers will take their feet off the gas and let things chill for a bit.” I feel that the overnight lows of 152.89 and 177.86 are close enough and I am going to exit all JPY longs. I would love to buy the low tick, but that’s not always possible.
The CHFJPY put spread is so far through the bottom leg that it doesn’t need to be taken off, but I will cover the short EURJPY from 184.80 here (179.19) and be happy. Regular readers will know that my average risk/reward is 1.0-to-1.7 and these yen trades, which both paid more than 3.5-to-1 are juicy in that context and there is no shame in getting out. Sure, this could be a huge macro trade, but those rarely go in a straight line and (as discussed yesterday) there is a certain countercyclical aspect to the whole thing: The more USDJPY falls, the less policy needs to lean yen-positive.
I can always get back in again if I decide the water looks warm.
The yuan is having a strong year, one of its strongest YTDs on record. The CNH started trading offshore in July 2010, and 2017 was the only year that saw more appreciation than 2026 in the January to August period. This chart shows January to August in light blue, and the rest of the year in navy.
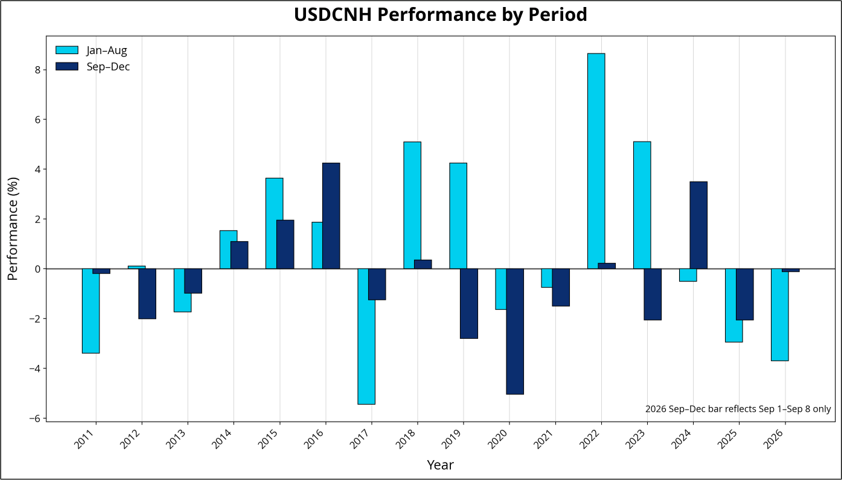
There is no call to action here; I was just surprised. If you look at the 9-month rolling performance of USDCNH and the scatter of JAN-AUG vs. SEP-DEC, there is no strong reason to think USDCNH should reverse. The base case is probably that it zigzags and mostly goes nowhere for the rest of the year with most of the vol coming from the USD (i.e., CFETS basket), not a strong PBoC bias towards appreciation or depreciation.
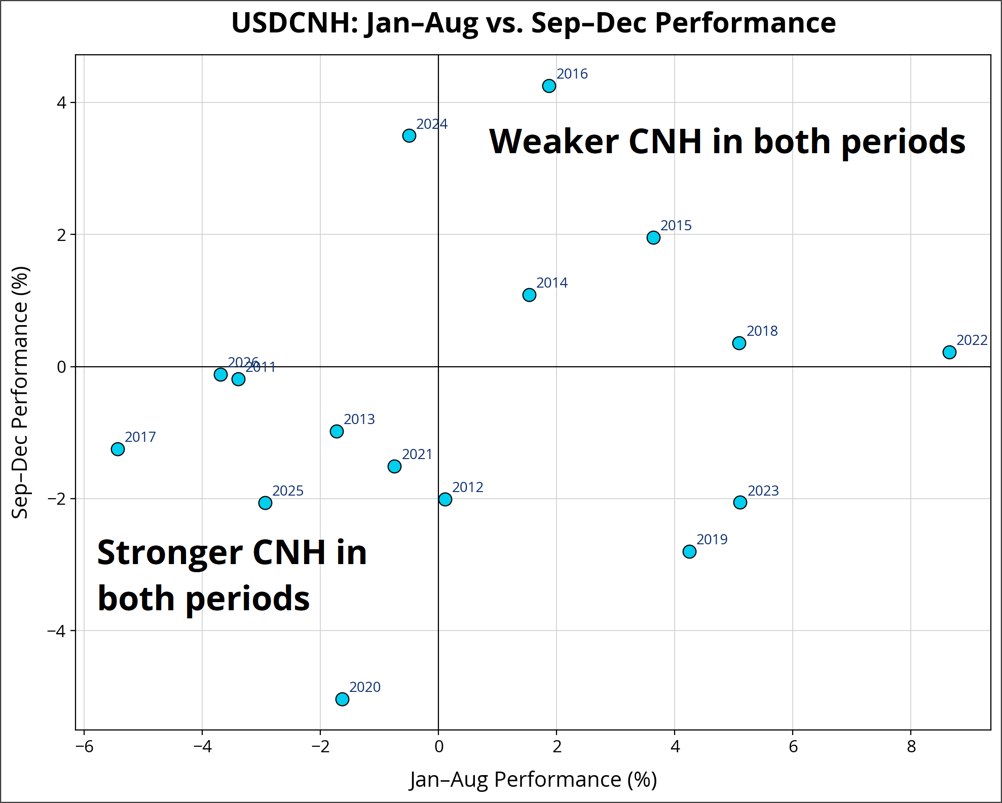
The scatter shows that of 16 years, only two show a meaningfully different direction of change for USDCNH in the two periods (2019 and 2023).
And the 9-month rolling change in USDCNH shows you that it’s not particularly overcooked compared to where things went in 2017 and 2021.
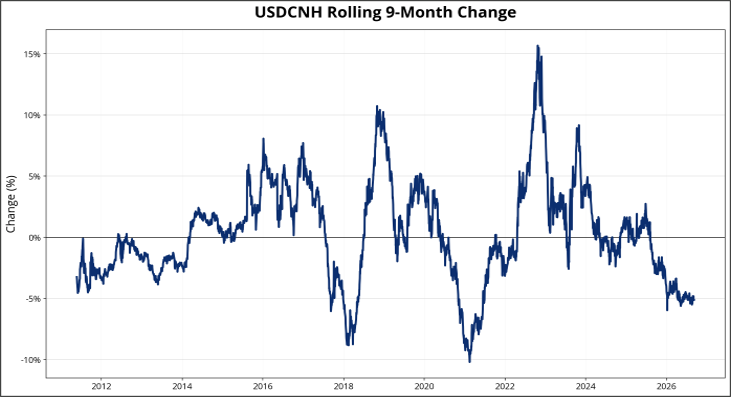
I tried the “CNH goes nowhere and it’s a low-yielder / great funder” trade twice in recent months, but lurking USD weakness has kept the trade from making money. CNH continues to appreciate vs. the USD in extreme slow motion, even though the RMB peaked against the basket on July 24. Nothing to do in CNH right now.
Have a hard-tackling day.
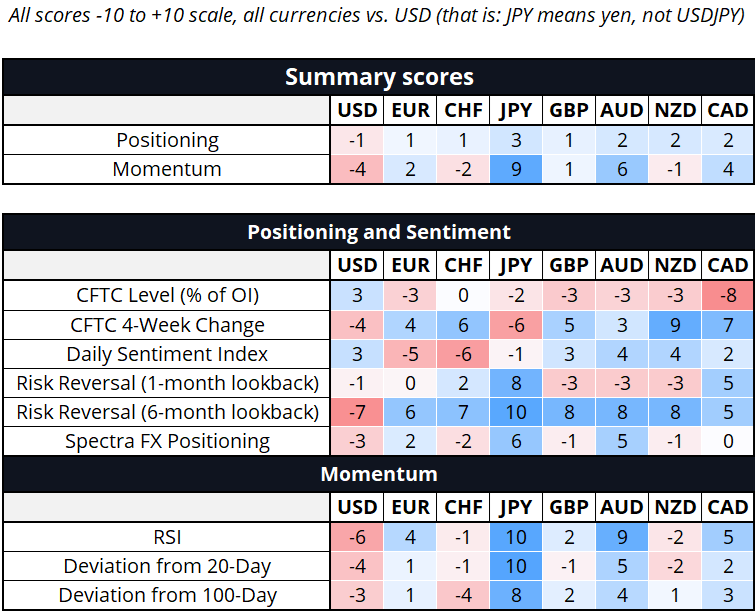
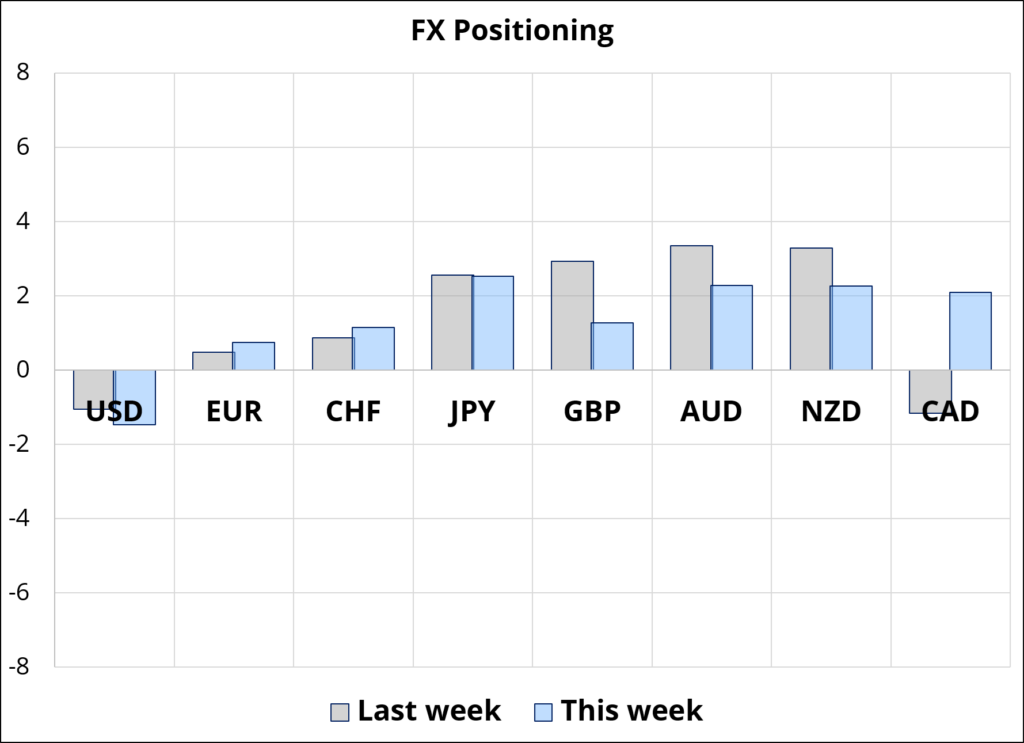
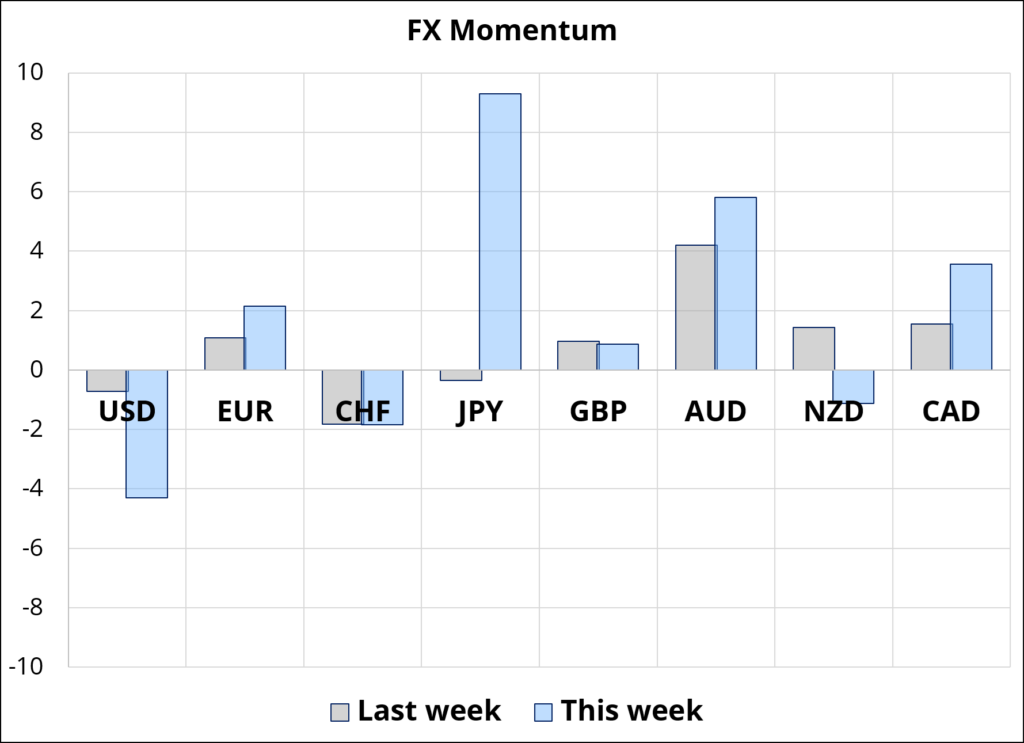
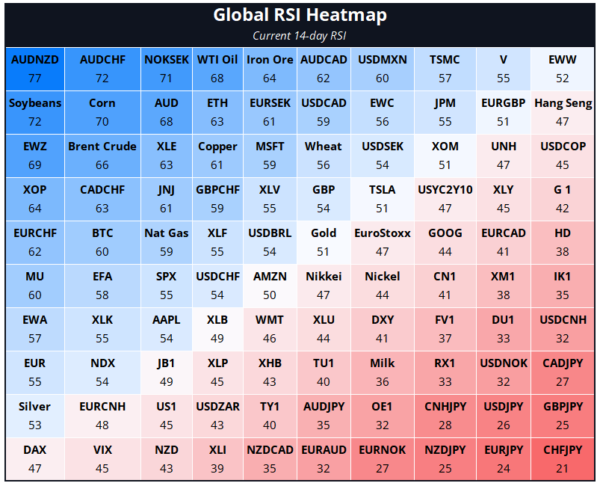
Hi. Welcome to this week’s report. (To read about how I use and trade this report, see here.) As you might expect, the upward momentum in the JPY has triggered a feeding frenzy of sorts as the long-awaited GPIF move is starting to happen and nobody wants to miss a possible repricing of a currency that has been undervalued for ages. The fiscal story has been forgotten as a single variable explanation for the JPY as policy preferences move away from more stimulus and towards a more stable yen and JGB market. While our franchise shows strong bullish flows in JPY and AUD, the overall data still points to a slow return to USD shorts. Check out the cross/JPY RSIs on the RSI heatmap—CHFJPY particularly is getting close to the short-term danger zone. Then again, when there is a big policy-induced move in FX, RSIs are bound to go to an extreme.
Don’t show this to Faltas