
Midterms DID mattter!
Highlights
NQ, Fed, and bullish gold
My bullish gold view today is more about micro action, not macro fundamentals, but I think the macro could catch up to the bullish micro at some point and the risk management is easy
Midterms DID mattter!
Hello. It’s Friday. Thanks for signing up. I’m Brent Donnelly.
Here’s what you need to know about markets and macro this week
Today’s feature image goes out to all the kids who wrote out various words and titles and names in the Iron Maiden font on loose-leaf paper in their duotangs as the teacher droned on about The Merchant of Venice or X+Y=Z or whatever. Also: I called a note: Run to the Hills in 2024 and that was the low, fyi.
The last two Friday Speedruns were called “A Crisis of Faith” and “Wobbling” and I guess now we have finally cracked. The important question now is whether we are near the end of a correction, or the start of a bear market. The 200-day moving averages are gone and so this is a good time to keep an open mind. Pavlov’s Dogs buy every dip and if you have an unlimited time horizon and no stop loss: Sure. But if you are a trader or an investor with risk management considerations, it’s worth considering how a procyclical momentum driven market can turn to a countercyclical wipeout.
The macro story this week was the election. The bluenami took even the most ambitious Democrats by surprise as the maps all looked something like this:
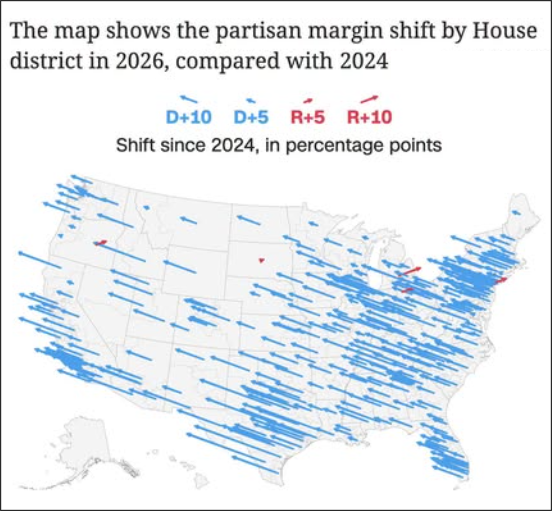
Or this:
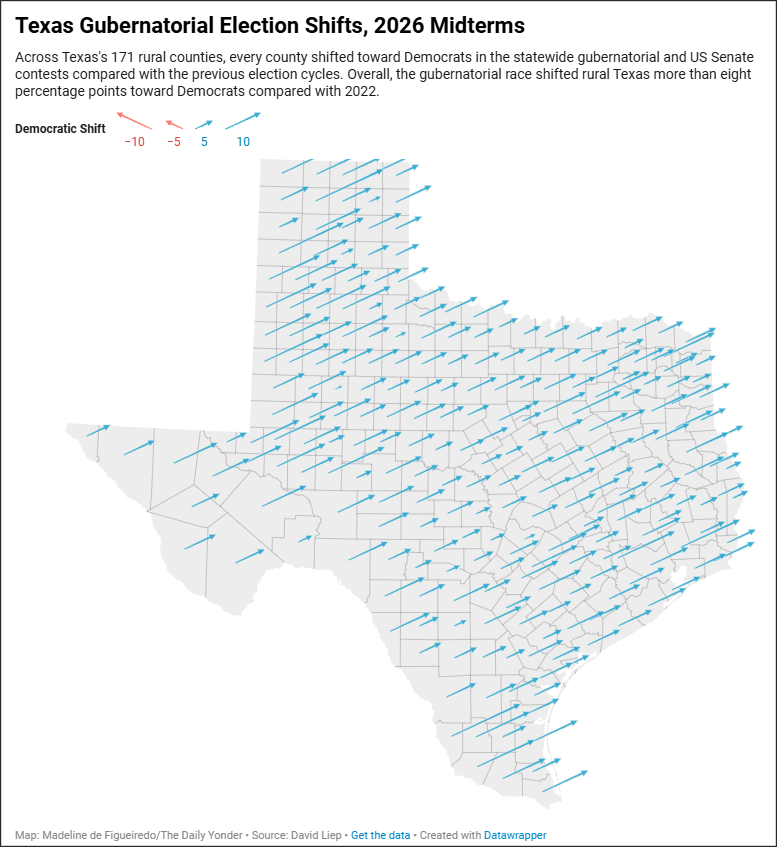
Because of this:
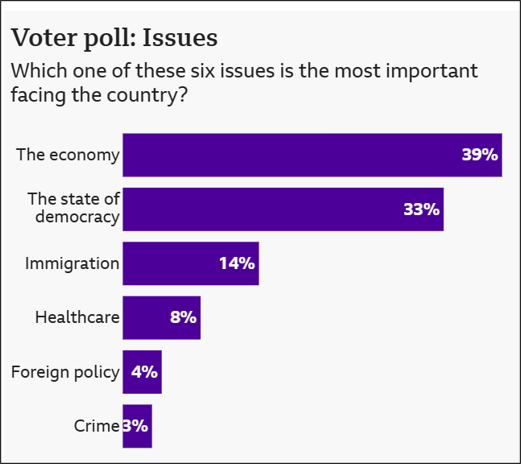
There was a strange moment in markets on Wednesday as JD Vance tweeted the contents of that purple graph as some sort of revelation and the market somehow interpreted that as: Trump will come to the realization that people don’t like his war and will stop that war because wow people don’t like it?!
Weird. Anyway, that was a big oil down, stocks up day, and then the market decided Thursday that, wait, we were already worried about data centers and now maybe we should be even more worried! And we should sell all the techno-utopia trades because Elon Musk has lost his magic.
Friday the pendulum swung back a bit as Texas governor-elect Hinojosa said that all currently permitted data centers will be allowed to finish construction. That statement essentially covers all of 2027 and much of 2028. Markets are most inefficient when attempting to factor in new and confusing information.
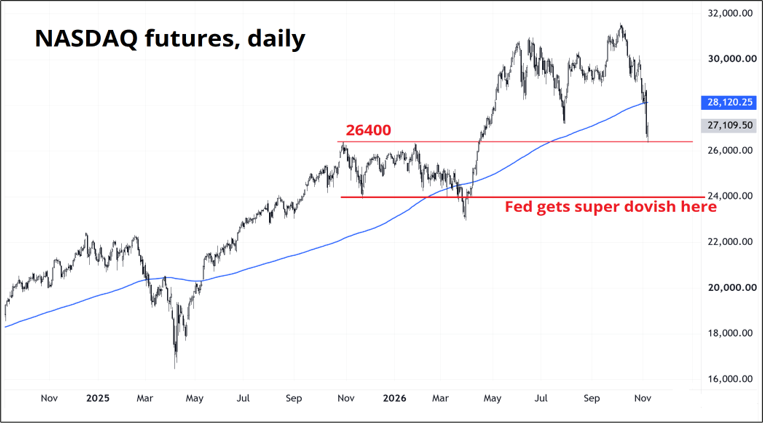
With tech indices now 12%/14% off the highs, the reflexive dovishness will come pretty soon from the Fed. We are not there yet, but if you look at various speeds and magnitudes of NASDAQ drops needed to turn the Fed dovish in recent decades, 20% in three months is a good heuristic.
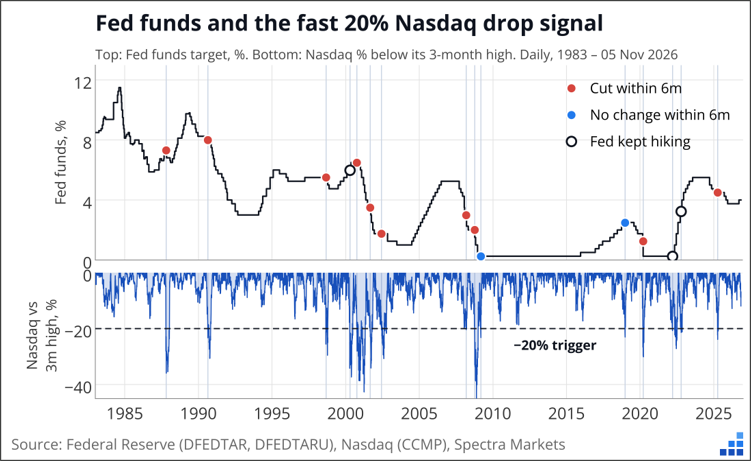
It is a bit regime-dependent, of course. That condition was met in 2022, for example, but the Fed kept hiking anyway because they had long lost control of inflation after misjudging the impact of U.S. MMT. The current regime is nothing like 2022 and so I think the heuristic applies.
We saw the 20% rule play out at the end of 2018 when a hawkish Fed plus uncertainty over midterms and a new Fed Chair combined to push stocks lower and the dollar higher. The mix didn’t crack until the Fed turned dovish in early ‘19. More on that in the stocks section.
Other than the tech melt and the hedge fund exits, winddowns, and stop outs that have ensued, we did get another solid U.S. jobs report. We are in a phase here where U.S. data feels particularly backward-looking and so I don’t expect there to be a huge impact from today’s jobs report, or next week’s CPI data. The stock market and oil have both dropped a fair bit now and that takes some pressure off a Fed that really, really, really doesn’t want to hike.
If NASDAQ futures get to 24000, which is 20% off the high and about 3000 points below current levels, the Fed will turn substantially more dovish and a December hike will either be off the table, or it will be the last before a series of cuts in 2027. In the meantime, the big level to watch is 26,400. That’s the old double top (old resistance now support) and yesterday’s low.
My guess is that the folks at Anthropic are wringing their hands right now, trying to decide whether or not to postpone an IPO that was supposed to be over $2T and was set to land 16/18NOV. Now, it’s maybe $1.2T or $1.3T and could arrive this month, or maybe next year. It will take some intestinal fortitude for the underwriters and executives to stay the course, and to me it’s a 50/50 call right now whether they greenlight or postpone.
Polymarket odds suggest only a 70% chance of an Anthropic IPO in 2026, down from 95% a few weeks ago.
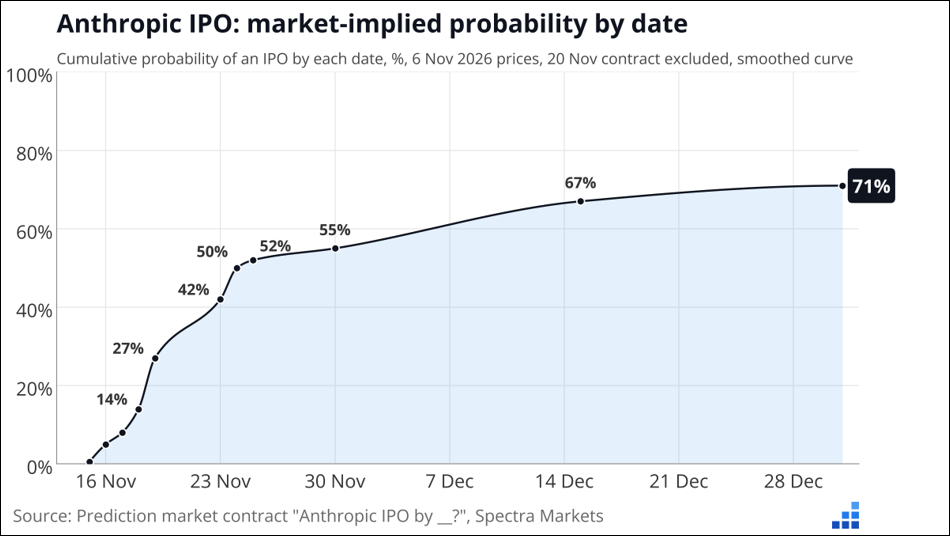
If they postpone, the market kneejerk will be to sell off on tightness-of-funding angst—that could easily be the ultimate low in NQ because the supply overhang lifts and the postponement itself is a contrarian sentiment indicator. The ANT perp is trading near its life-to-date lows, around 1.45T on mega volumes (see chart).
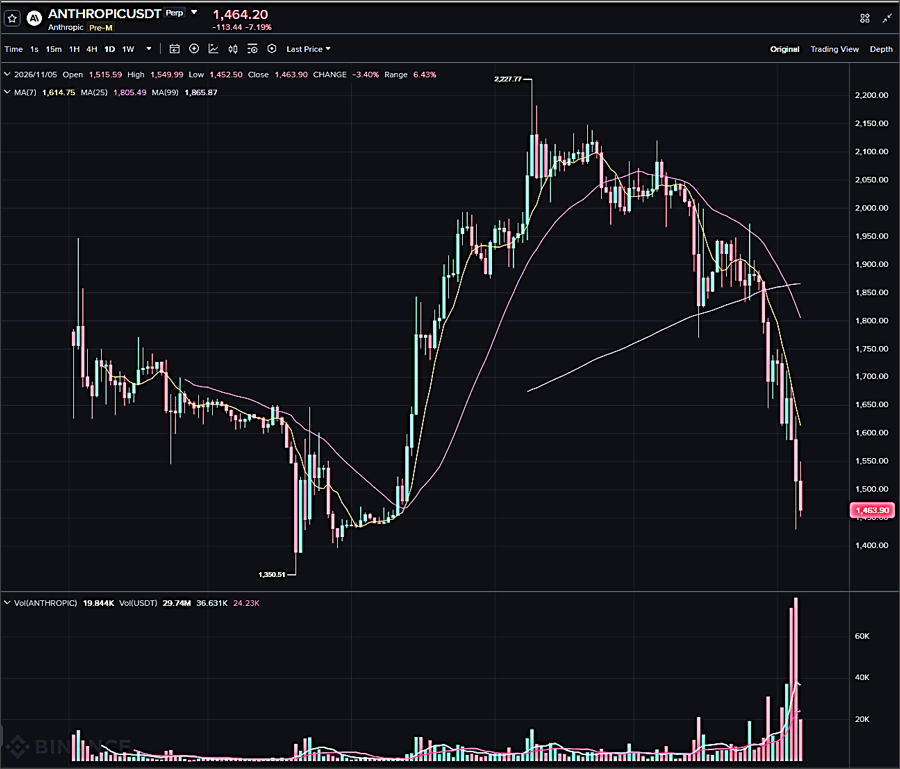
Note that ANT perp on Binance trades 200B below the one on Hyperliquid because the settlement terms are different if ANT never does an IPO. On Hyperliquid, you get the average trading price of the prior six months while on Binance you get who knows what. It’s not clearly defined, as far as I can see. Hence the discount on Binance.
Here is what we did this week:
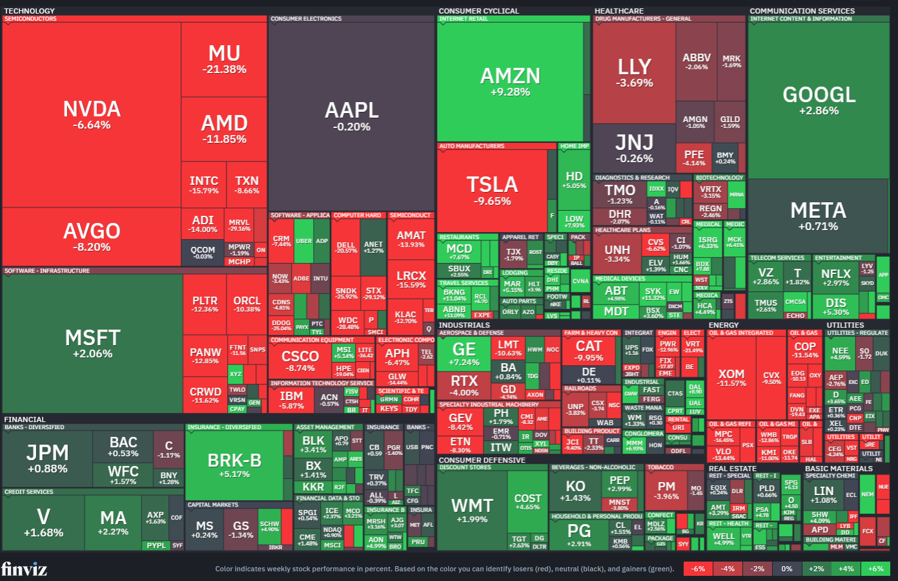
This heatmap belies the feeling of terror in the street as momentum favorites and long/short factors blow up while the S&P 500 remains just 5% below its all-time high. Leveraged beta is a really bad investment strategy as it’s often poorly risk managed and thus non-ergodic.
Anyhoo, the median stock in the S&P 500 was up 0.8% this week
The average stock was down 0.7%
Numbers are fun
I have been discussing how monetary policy in times of war is difficult because hawks and doves can both sound smart, even as they have no clue. There is a binary variable (U.S. aggression) that is not forecastable, and your monetary policy decisions are at its mercy. You can make a lot of smart comments about second-round effects and all that, but you might be repeating the ECB mistakes of 2008 and 2011 by hiking into a supply shock right before a demand shock—or you might repeat the mistakes of the 1970s and 1980s and let inflationary psychology take hold after a failed early 2020s MMT experiment.
The RBA meeting was a good example as the vote was not unanimous. Some members wanted to hike, others thought it rude. AUD suffered this week, especially against the crosses, because it is a risky currency and the RBA failed to deliver a hawkish message. Like every other central bank in the world, they are sans compass.
The Fed is still priced for 75% in December. If NQ trades 24000, that will go to zero. Otherwise, it will crawl back towards 100%. Bit by bit.
FX is very hard right now and nobody is happy. The issue is that what most perceived to be a USD-negative event (re-rating of AI Capex growth pre- and post-election) has been anything but. EURUSD tried hard to go up yesterday, and it looked reasonable to me to go short USDCHF or USDJPY and yet the USD took a flurry of punches and snapped back like one of those rubber punching clown doll things.
Dynamic rebalancing from real money is part of it. Real money needs to buy USD as equities fall. But this mechanical USD buying does not always have to prevail. This time it has. The hard part about trading the USD on U.S. equity weakness, using a model similar to 2000 which was: (money in = USD UP | money out = USD DOWN) is that there is a timescale mismatch.
The market always buys some amount of USD when stocks get clobbered because the rush for liquidity and mechanical rebalancing trigger demand for dollars. But bigger picture, less demand for U.S. assets and slower U.S. GDP growth on slower AI Capex growth due to financing constraints are all reasons to sell USD. The third factor would normally be positioning, but I don’t feel there is a large USD position out there, either way. So, what you have is a short-term bull trade vs. a macro bear trade and clearly the USD bulls are in control right now.
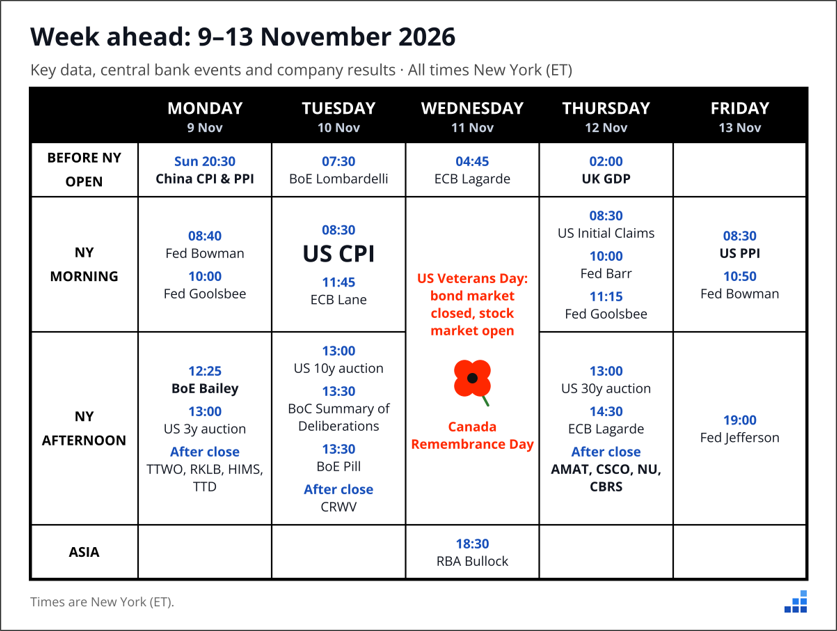
Here’s next week’s calendar:
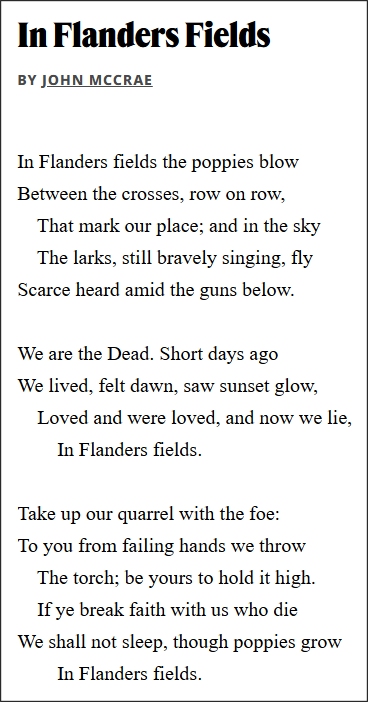
And here’s a poem about poppies for Remembrance Day. This poem is well-known in Canada (it was on the ten-dollar bill!), but many outside Canada don’t seem to know it. So, behold its beauty.
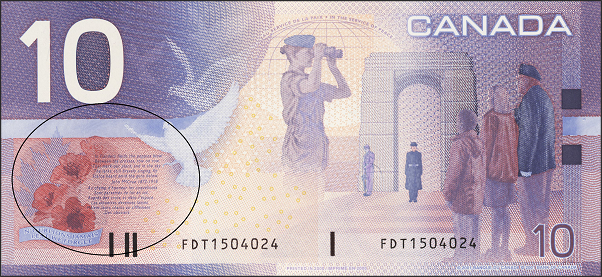
Don’t print and spend this! That’s counterfeiting.
One of the most influential essays ever written about war:
Hiroshima by John Hersey (1946)
This is a 2- to 2.5-hour read. More like a very short book than a magazine article. The entire edition of the New Yorker Magazine was dedicated to this single work. It blew my mind and it’s even more impressive when you understand that articles like this were not a thing in 1946.
Context: https://www.nationalww2museum.org/war/articles/john-herseys-hiroshima-1946
HEY! If you’ve read Trade Outside the Box – please click here to leave a quick review. Thanks! And if you have not… Buy it here:
TRADE OUTSIDE THE BOX: Advanced Thinking for Professional Traders.
Here’s the one-pager.
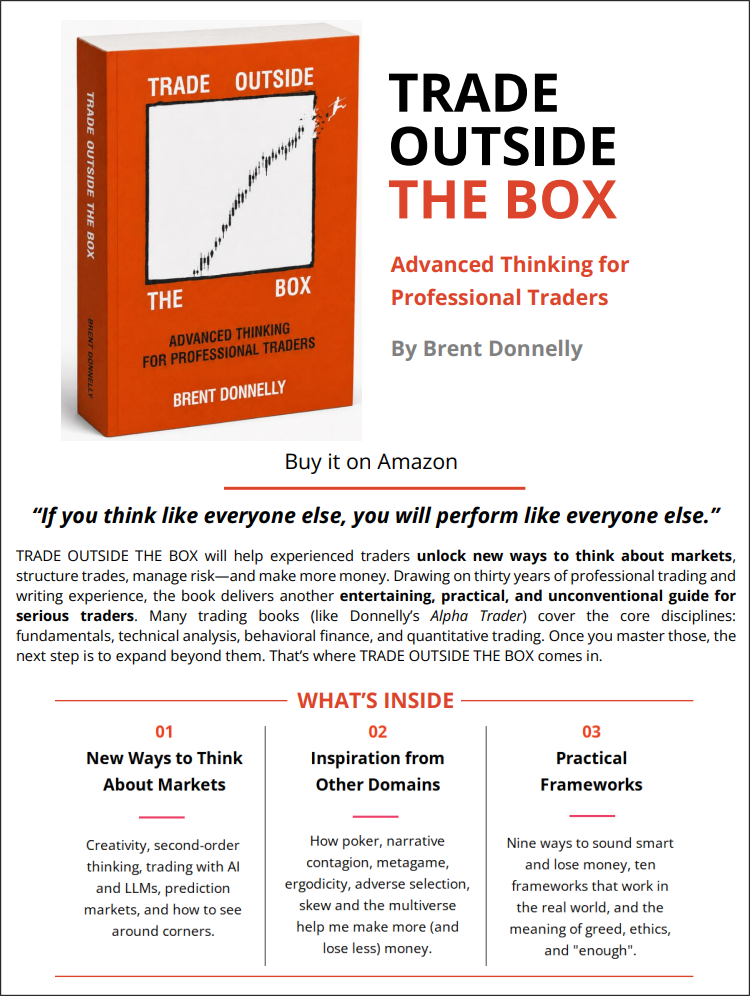
The book is written for experienced traders. If you are new to the game, I would suggest you start with Alpha Trader. If you have been trading or investing for more than five years, this book is for you (and you don’t need to have read Alpha Trader to enjoy it).
Bitcoin is back to 75k, and ETH is back to its happy place around 2200. 42% of all daily closes since 2021 have been within 20% of 2200. Fun.
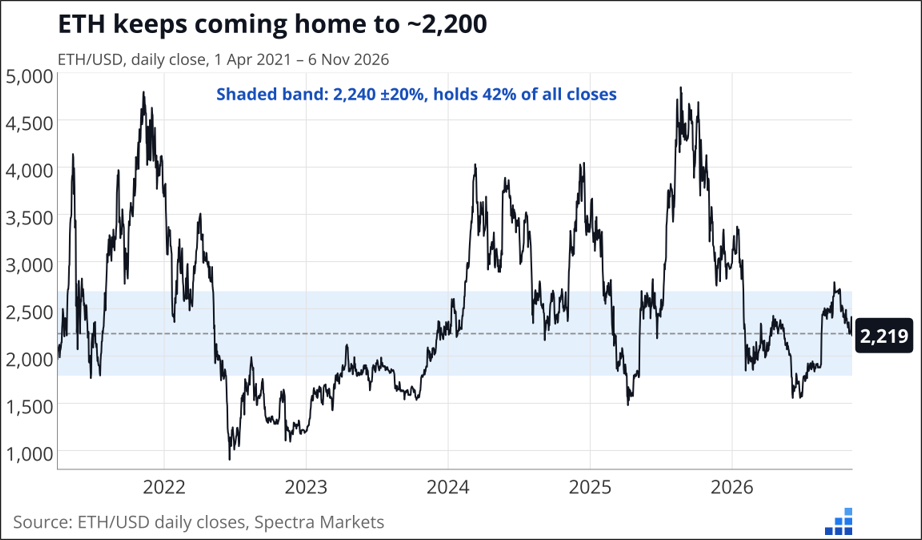
You could argue this price action is kind of impressive given L2s won at ETH’s expense, smart contracts found their use case in the most boring killer app of all time (USD stablecoins), narratives like “ETH is ultrasound money” or “If BTC is gold, ETH is oil” whiffed, memecoins moved to Solana, metaverse and GameFi died, and overall interest in Ethereum has rarely been lower.
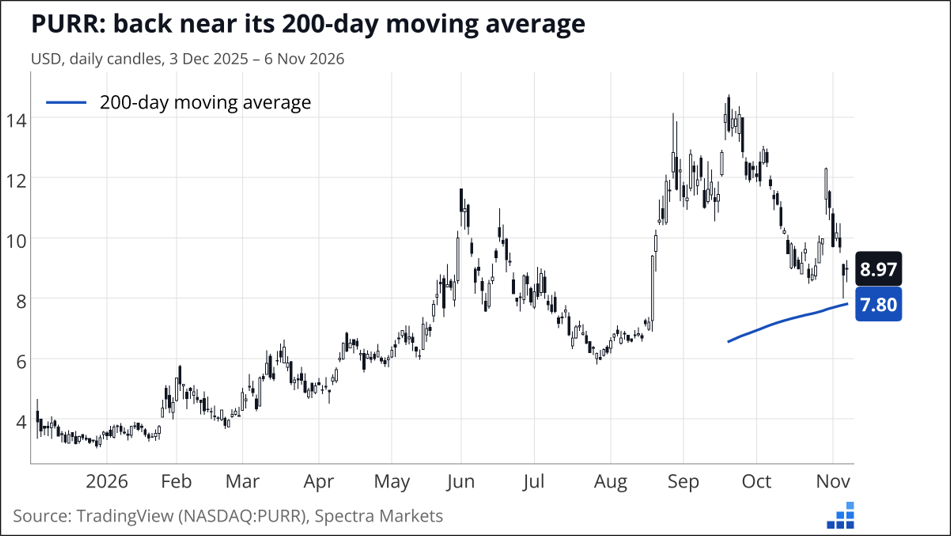
PURR has now been trading long enough to have a 200-day moving average! Here’s the chart. I wonder how much of a moat there is in perps. Feels like—not much? But maybe.
Copper finally broke down in slow motion as the AI Capex buildout slowdown story logically means less demand for the metal. The 20NOV CPER puts I mentioned last week were solid as CPER dropped about 4% this week. The trade has played out and I am no longer bearish copper as I think we are getting into the later innings of this panic and copper was just a laggard. Time for some new ideas.
Oil is back below $100 as the pre-election jitters about massive escalation once midterms are over and Trump has nothing to lose have turned to hopes for a Hegseth firing as JD Vance wonders aloud whether his choice to support a broadly unpopular war was worth the cost. I suspect many will turn against the president like that now as the game theory changes. In the meantime, there is a lot of weekend risk!
I suspect, even before JD Vance tweeted it, Donald Trump was aware that his war is deeply unpopular. I suppose the question is whether he is the type of politician to concede defeat, or double down on an unpopular policy. I do not mean that sarcastically.
Despite his past behavior, you can make a reasonable argument either way here:
1) Trump is angry and annoyed now, so he is more likely to double down, not back down. He clearly knew eight months ago that he had campaigned on no more wars and then launched one anyway. He has obviously known for months that the war is incredibly unpopular, even with MAGA. To say midterms are a wakeup call requires some imagination—the fact that the war is unpopular is not a news flash!
… Or 2) The President is tired and humbled and does not have the energy to fight as those who supported him now turn their backs on him, one by one.
The reason I mention all this is because the setup here is quite different from two weeks ago. Ten trading days ago, oil was 17% higher, Saudi evacuations were spooking the market, everyone was holding their breath, and the possibility of a U.S. climbdown felt minuscule. Now, the market’s exhaling and there is some hope that the U.S. can find a way to save face and move on. So, if the administration goes on a massive offensive now in the Middle East, or even escalates at all, the market impact will be meaningful. Something to think about going into the overnight sessions and the next few weekends. Extra gap risk if you’re long or short oil into the weekend between now and Thanksgiving.
I say the risk is binary because good news is not fully priced either. After eight months of fog, we might get some clarity in the next few weeks. Maybe Trump is bored of war and tired and ready to move on. Maybe Iran will see regime change in the United States and decide they don’t need to keep pressing their luck. Hard to say!
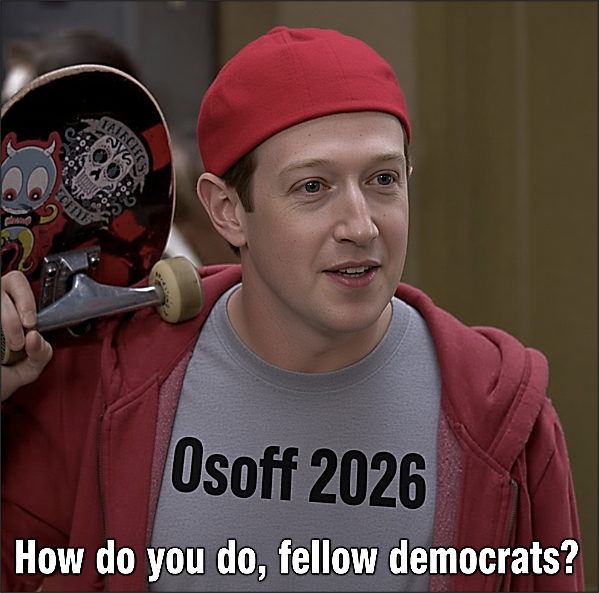
And finally: Republicans turning against Trump one by one is likely, but the tech titans slowly deciding they are, um, actually, left of center again after all is almost guaranteed. Every tech leader was left of center before Trump and they all turned hard right once he was elected because shareholder value must be maximized in whatever way necessary above all other considerations. If you’re an optimizer of shareholder value with no moral principles (as corporations are sort-of mostly legally obligated to be), optimal politicking now says it’s time for you to change your stripes again. Back to the left! It will be interesting to see who goes first.
The memes capture the zeitgeist, as always:
That’s it for this week.
Get rich or have fun trying.
*************
As long as you are loyal to your government, you have nothing to fear
*************
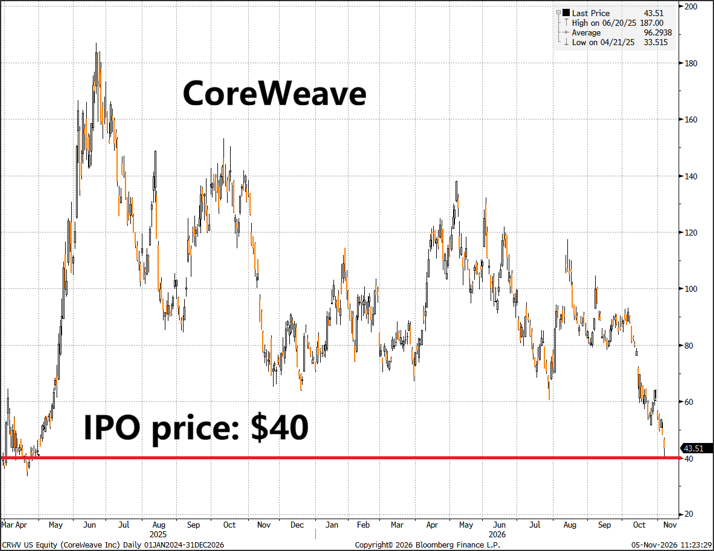
Full round trip in CRWV.
A person named Nic Carter (a crypto VC guy with a lot of followers, who I do not know) posted a tweet, like: CoreWeave is an IQ test and most of you have failed when CoreWeave was above $65. It’s a good lesson for younger market peeps: 1) Markets are not an IQ test; they are a rationality test. Many of the worst financial disasters were engineered by the smartest people in the room. Too smart is worse than not smart enough. 2) If you think you have everything figured out and the endgame is predetermined and your world-class intelligence makes you better than everyone else… Markets are here to humble you. Finance is probabilistic, not deterministic.
Anyway:
*************
*************
I think the third one of these is best. But all three earn five stars.
Run to the Hills, Iron Maiden 2019 – I saw them do this in 1982. They still going. Same lead singer. Unflippingreal.
Run to the Hills, Japan style HAGANE
Run to the Hills, acoustic / Swedish
*************
Thanks for reading the Friday Speedrun! Sign up for free to receive our global macro wrap-up every week.
My bullish gold view today is more about micro action, not macro fundamentals, but I think the macro could catch up to the bullish micro at some point and the risk management is easy
Maybe he knew the war was unpopular, even before midterms and Vance’s tweet?
The implications of midterms are marginal; a Dem sweep was 75% priced