Charts and thoughts
Happy 100th birthday to Route 66

Charts and thoughts
Happy 100th birthday to Route 66
Short EURJPY @ 184.80
Stop loss was 186.37
Now 183.11
Take profit under 177 or if USDJPY closes back above 156.00
10SEP CHFJPY put spread
199/196 for ~37bps off 200.50 spot
Worth 151 bps if nothing insane happens this week.
30NOV Long 1.23/1.25 AUDNZD c/s
vs. short 1.18/1.19 p/s
Cost 2.5 bps off 1.2093
Unlike my terrible long USDBRL idea last week, which is already stopped out, my CHFJPY and EURJPY bear views have been good. The CHFJPY put spread I put on above 200.00 has been a long and exciting series of hills and valleys ever since I published the view on July 10. You can read it here:
https://www.spectramarkets.com/amfx/seeking-to-encourage/
That was the day Katayama made her “seeking to encourage” comments and it became clear that GPIF was finally (maybe, probably?) going to join the fight against the weak yen. It appears as though GPIF is finally selling USDJPY at this point as the aggressive nature of USD selling from custodial banks raises eyebrows and the timing roughly makes sense as Katayama ordered it in July and there has been a great deal of smoke from Japan, week after week, as they hire domestic bond managers, watch the MOF intervene, see the BOJ turn to a September rate hike, and so on. Policy turns take time and this one is playing out slowly but surely in broad daylight.
Currency intervention rarely turns the tide on its own. It buys time for policy change, or changes in macro to take hold. Now, the policy changes are happening, even as the U.S. macroeconomic landscape remains unchanged as the soft landing and AI Capex stories motor on.
Importantly for the JPY bulls: The price action finally supports the narrative. It took incredible patience to stick with the JPY trade over the past two months as many pairs range traded, and there was a strong cohort of faders making money going against the MOF. Now, it feels different as real money sellers of USDJPY are getting on board and the charts are starting to crack.
155.00 was a huge level in USDJPY on multiple occasions, and it held up against ferocious selling each time. That includes the day the U.S. joined the MOF and sold a tiny slice of EURJPY in a show of oddly tentative solidarity. As discussed a few times in here, coordinated intervention has a long history of success, but that success does not feature v-shaped instaturnarounds in FX.
It features many long battles before the coordinated interveners finally win the war.
Before we look at the chart to hunt for take profit levels in USDJPY and EURJPY, I want to make one point that I believe is important for context. This Japanese policy shift looks somewhat like a reversal of Abenomics, but really, it is not. It’s feet coming off the gas, not feet stomping the brakes.
Abenomics was about using every tool necessary, especially the BOJ, the MOF, and GPIF, to massively depreciate the JPY after decades of deflationary currency strength. They were happy to send USDJPY from 75 to 125 in a straight line in a bold effort to shake off the stagnation worms and restore some kind of inflationary economic vitality. And they succeeded.
Now, does Japan want to send the yen to the moon and trigger a cascade of USDJPY selling down to 125.00 or 100.00? Absolutely not. Do they want a stronger yen and the disinflationary headwinds that could unleash? Not really. What they want is an end to persistent one-way JPY depreciation. They want a stable and perhaps slightly stronger yen. So, if you are playing a shift towards a stronger yen, and you believe policy is the primary driver, keep in mind that policy will be less yen-bullish below 150.00 and MUCH less yen-bullish below 145.00. If USDJPY goes to 145 in a straight line, the BOJ will turn dovish, the MOF will stop chirping, and GPIF will probably slow its domestic asset purchases. They are trying to land the Abenomics plane safely, not fly it back whence it came.
Given that is my view, I think the take profit targets should be reasonable, not creatively ambitious. Here’s the chart. 155 is a sextuple bottom and that includes two bottoms last week. Now that we are through that, we should absolutely not go back above the NFP high (156.82).
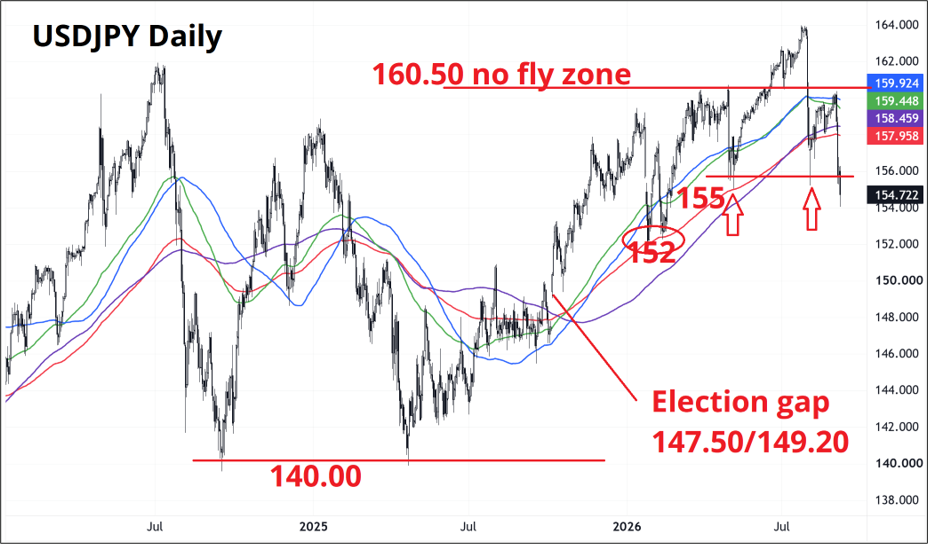
Here are the supports:
152.20/50 Early 2026 double bottom. Low ambition target.
150.00 Round number ahead of election gap. Smart, realistic target into BOJ.
149.20 Top of election gap after Takaichi win. Retested and held 10 days after the election.
147.50 Bottom of the election gap
142/143 July 2025 quintuple bottom. Ambitious target that I do not think will be reached for a very long time.
140.00 Massive double bottom in 2024/2025
With 155 broken, I think we can go to 152.20/50, but I would be nervous staying short down there. I will look to cover my short EURJPY on a daily close back above 155.00 in USDJPY or a touch of 152.20/50 below. Looking at the EURJPY chart itself, there is pretty much one huge downside level: 175.00/50. That is the old top in 2024 before EURJPY collapsed to 154.00 and it’s the opening level after Takaichi won the supermajority. You can see that in October 2025 there was a bunch of post-election price action around 175 and then EURJPY finally launched to 187. For good order, I will move my stop loss down to 183.11 to ensure the trade stays well in profit, and I will TP below 177.
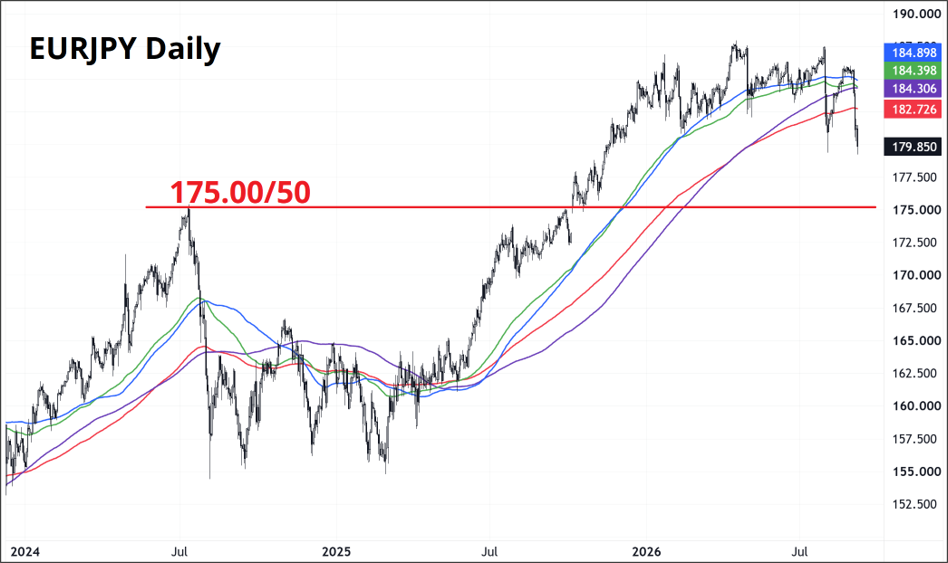
I am essentially positioned for one last huge wave lower in USDJPY and then at 152 USDJPY and/or sub-177 EURJPY I will go to neutral as the policymakers will take their feet off the gas and let things chill for a bit.
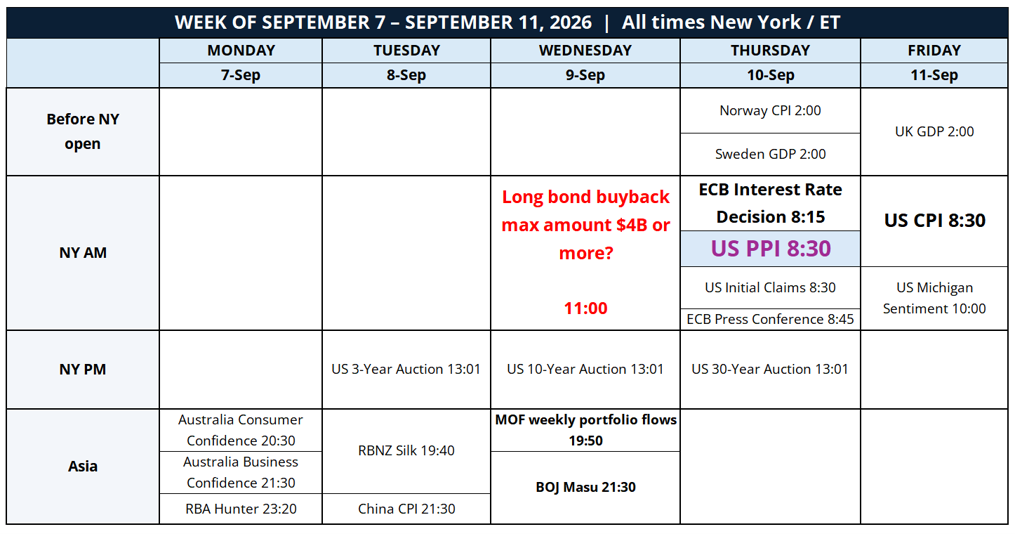
Some interesting and non-obvious stuff this week as we get:
I hope your week is clutch.
Route 66