

Can a bear market end without anyone ever experiencing any visceral fear? I doubt it.
am/FX: Still No Fear
Subscriber-only
BD
by Brent Donnelly
Current Views
Flat
September 19, 2022
Still No Fear
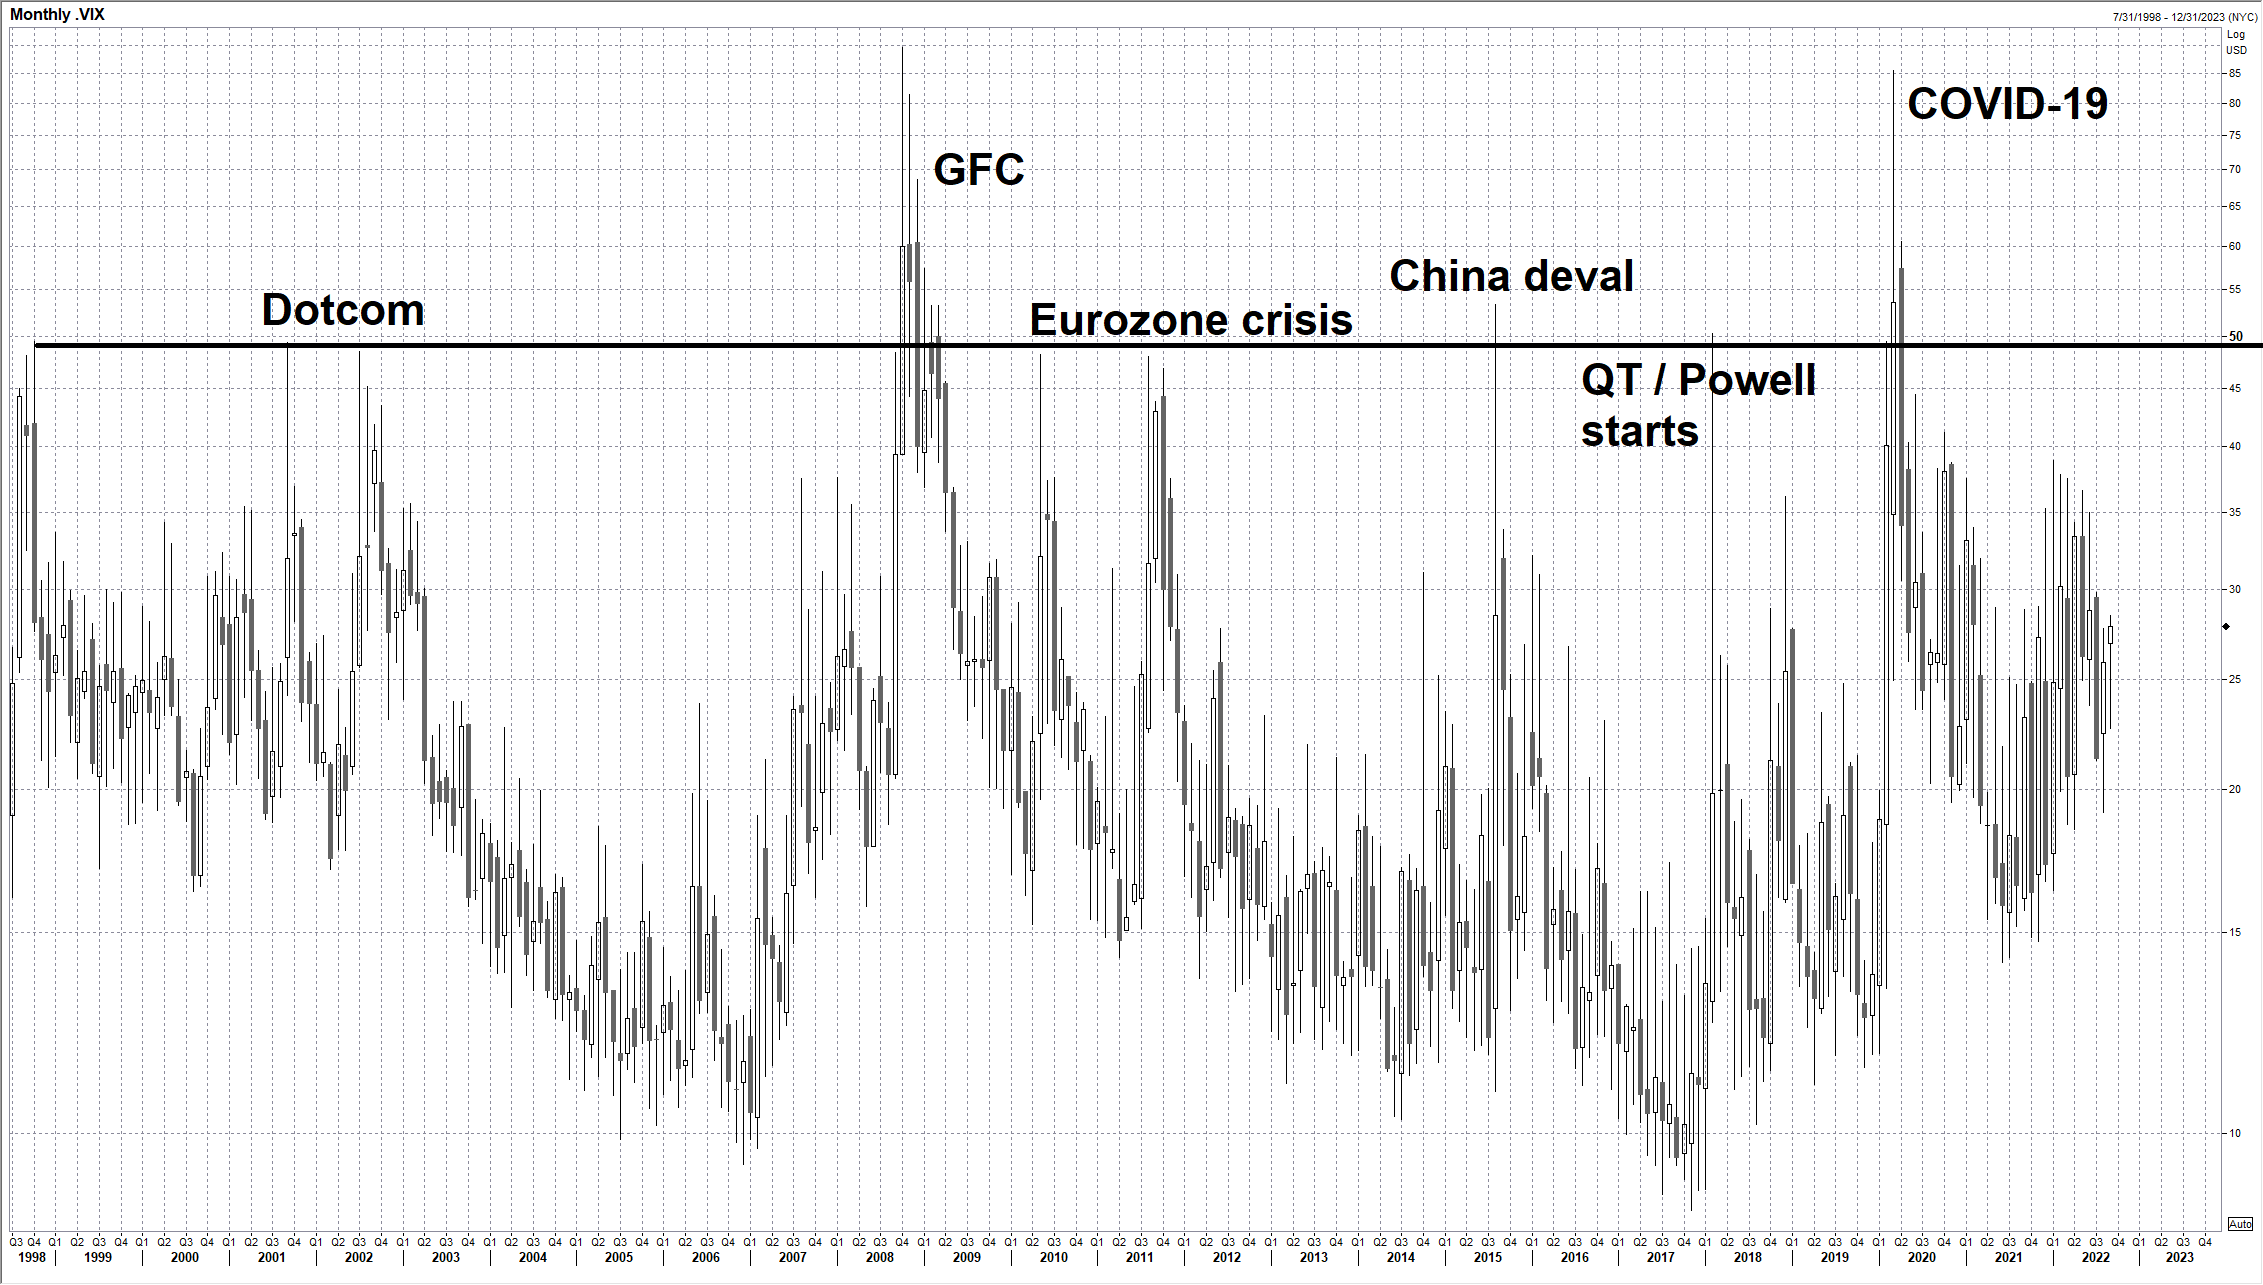
The most intriguing aspect of the 2022 bear market has been the steady erosion of equity and bond prices with almost no evidence of real fear or capitulation. The bearish sentiment always seems to get ahead of the price so every sell off has plenty of shorts on the bid. Things get oversold, shorts chase everything higher, and then we sell off again from lower highs.
Mixed in with this equity short base has been a Pavlovian buy-the-dip crowd made up of many traders and investors who have never traded a real bear market and who have been rewarded for the past 10+ years for buying every 8%-15% drop in stocks.
Here’s the multi-decade view of equity, bond market, and FX volatility.
VIX (equity volatility)
Back to 1998
MOVE (bond market volatility)
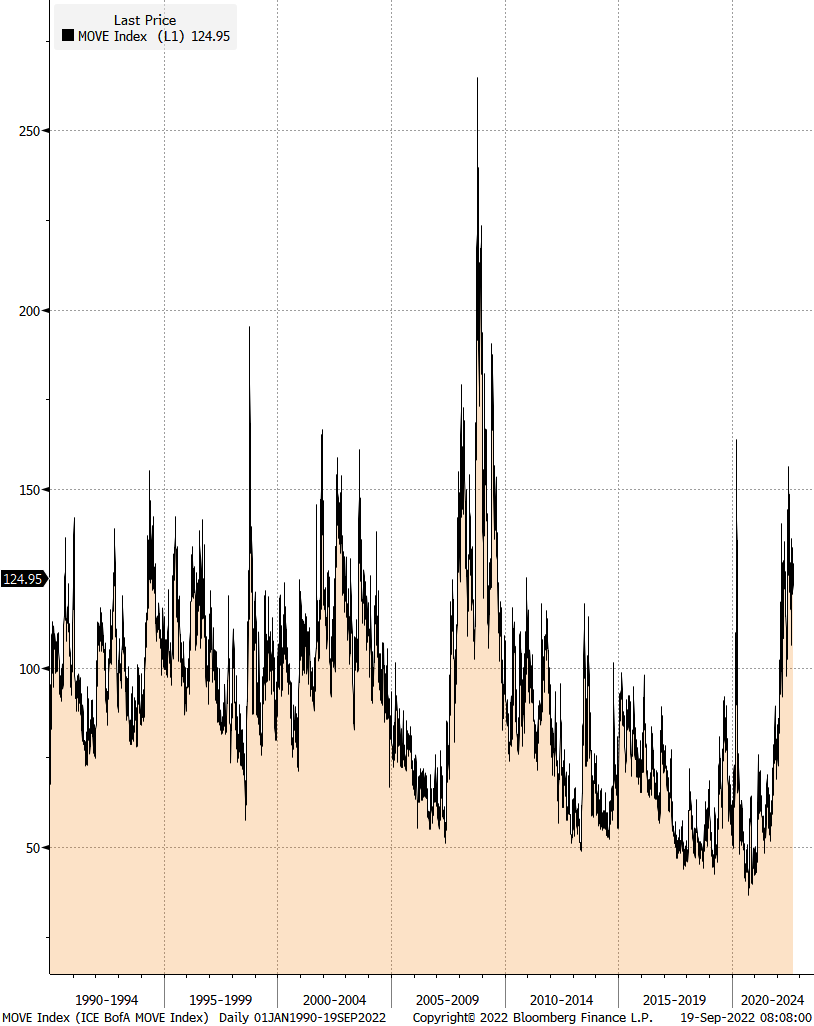
Back to 1990
CVIX (FX volatility)
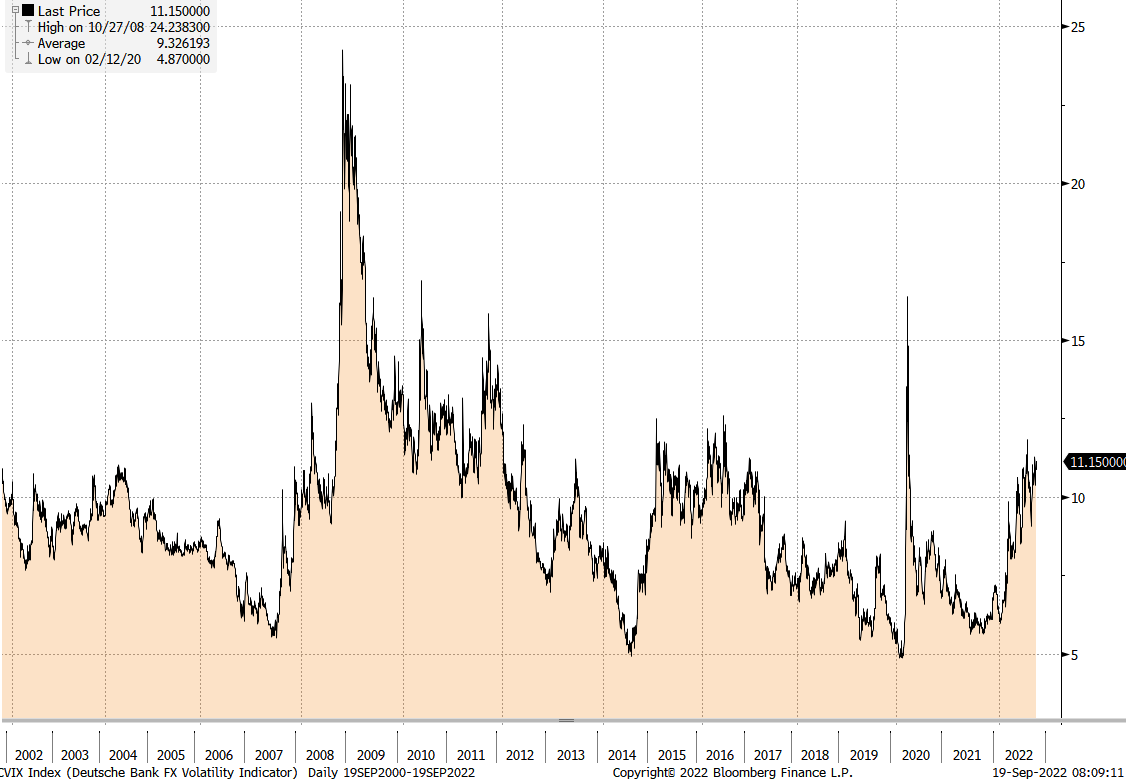
Back to 2001
You certainly would not know from any of these charts that we are in the midst of the biggest jump in both real and nominal rates since 2000. Here is the chart:
US 10-year nominal and real yields, 2000 to now
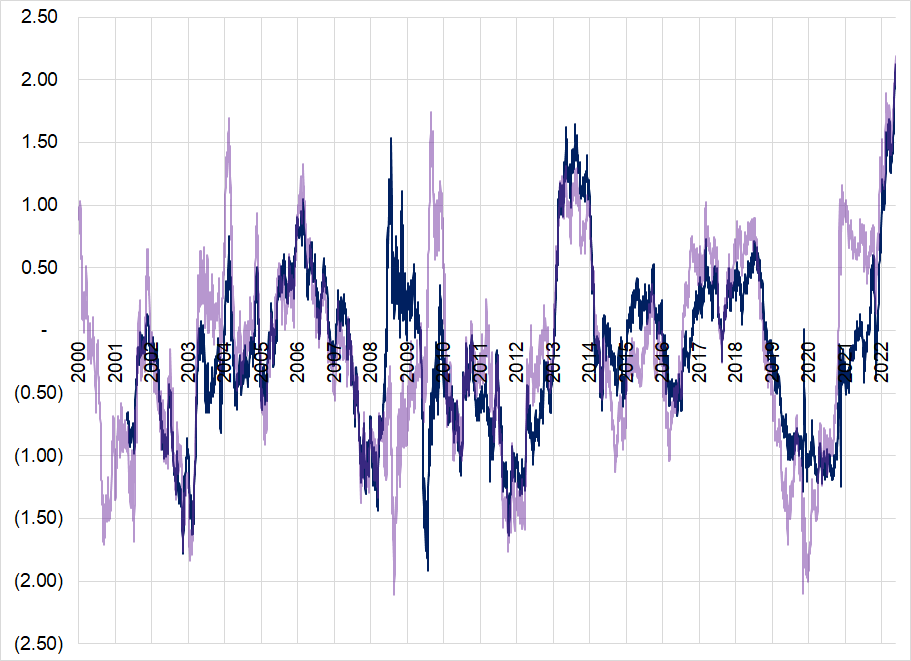
And this is 2-year drawdown in stocks:
2-year SPX drawdown (2-year high to current monthly low)
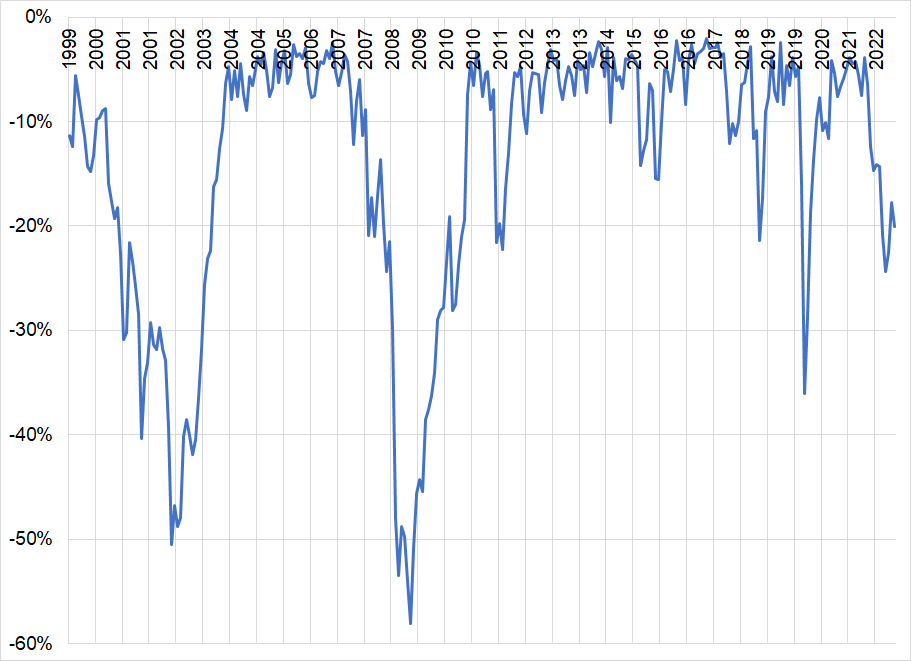
All this to highlight that there has been very little pain overall, especially in equities. And no real fear. The pain has been in the 60/40 bond/equity portfolios, crypto, and 2021 bubble stocks, but broad equity markets have mostly been spared so far. The overall market has weathered the dramatic rise in rates very well as it repriced the discount rate but kept the earnings side of valuation somewhat steady. The next few months will be a major test of this stability.
I think there are two ways you can look at this:
- Earnings are nominal, and stock prices are nominal, and this is why equities can do OK during some parts of the inflation cycle. Even if TINA is dead, there are no other great alternatives either.
- The market is very slow to price the new reality and is not fully grasping how much rates have moved. Similar to 2001 and 2007/2008, when stocks remained buoyant for ages before finally collapsing… Supportive money flows keep the bottom from falling out until complete panic finally sets in. Bonds are now a viable alternative to stocks for the first time in eons and earnings are about to shift down. The market is way too complacent still.
I lean much more towards #2 as it feels like too many people are still playing the sentiment and “buy the dip” game when the real story is skyrocketing interest rates. I don’t think this bear market is over until we see true capitulation (VIX over 40 type of thing)… The 2001 analog remains the most useful, I think, as 2021 is a retail bubble and malinvestment story like 2001, much more than a “too much leverage in the system” story like 2008.
Micro
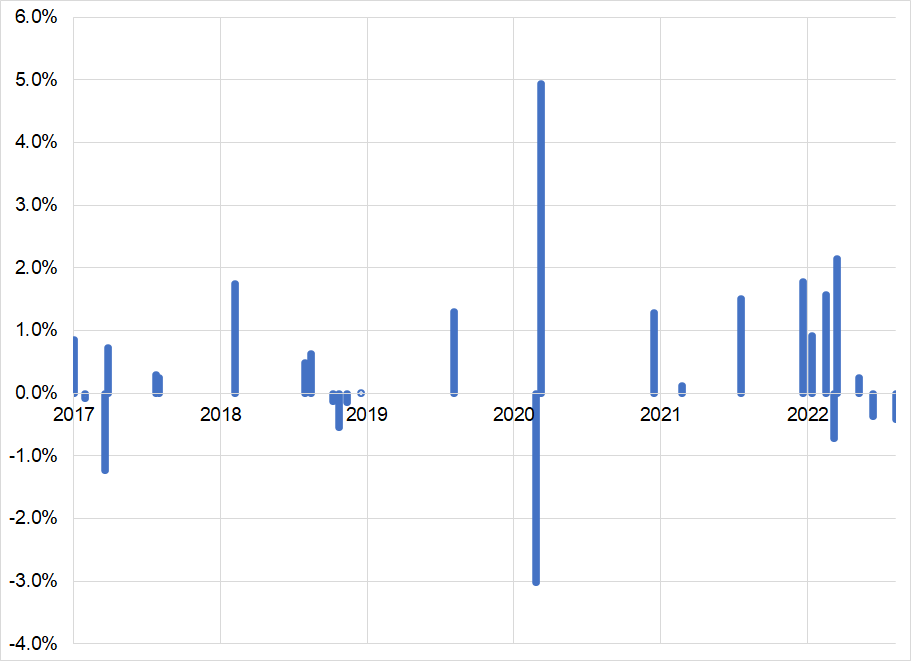
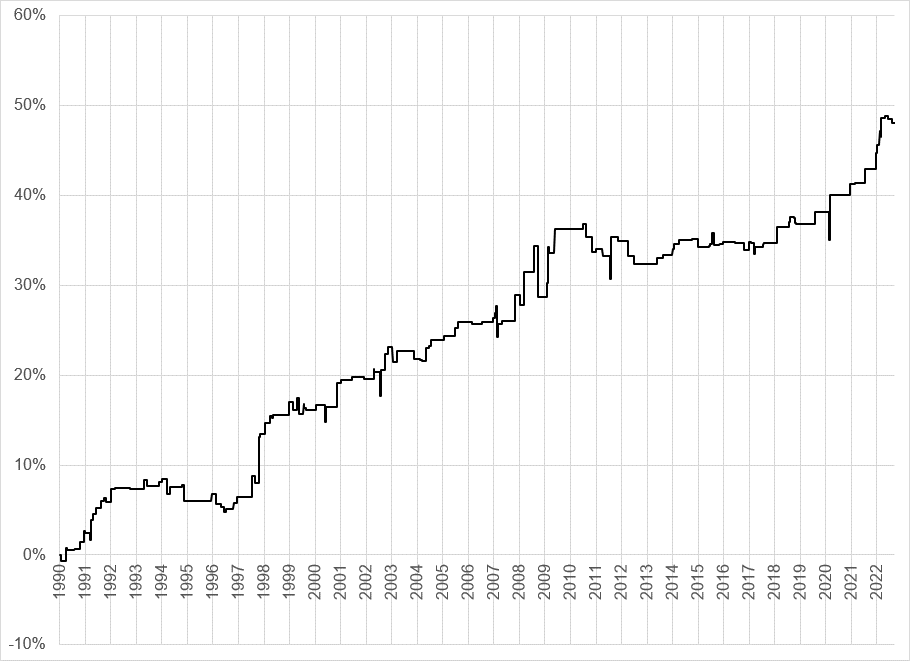
That said, bears need to be careful tomorrow, because if we close down today it will trigger a bullish one-day Turnaround Tuesday (TT) signal. Signal is: down Thursday, down Friday, down Monday, go long at close Monday and square up at close Tuesday. TT model performance has been middling of late but excellent in 2022. The first chart shows individual daily P&Ls of TT since 2017. 67% hit rate on longs. Average winner 1.2%, average loser 0.7%. The second chart (on the right) shows running P&L since 1990.
Individual daily performance of Turnaround Tuesdays since 2017
Cumulative performance of Turnaround Tuesdays since 1990
Final thoughts
USDCAD continues its long, slow march to 1.3500. Have a quietly heroic day.
good luck ⇅ be nimble
Good kitty.
https://twitter.com/Gabriele_Corno/status/1571115431787724800
Click here to subscribe to am/FX
More recent posts


Rabbit Holes
CAD and Rabbit Hole #18
This piece is mostly for people who are interested in backtesting