
The US continues to look exceptional.
Donald Duck’s middle name is Fauntleroy

The US continues to look exceptional.
Donald Duck’s middle name is Fauntleroy
Short EURUSD @ 1.1120
Stop loss 1.1226
Take profit 1.0966
I got the timing of the LDP election result wrong in Friday’s piece. The result should come out between 2 p.m. and 4 p.m. Tokyo time on the 27th, which is the middle of the night / early AM on the 27th for New York. I apologize for the error.
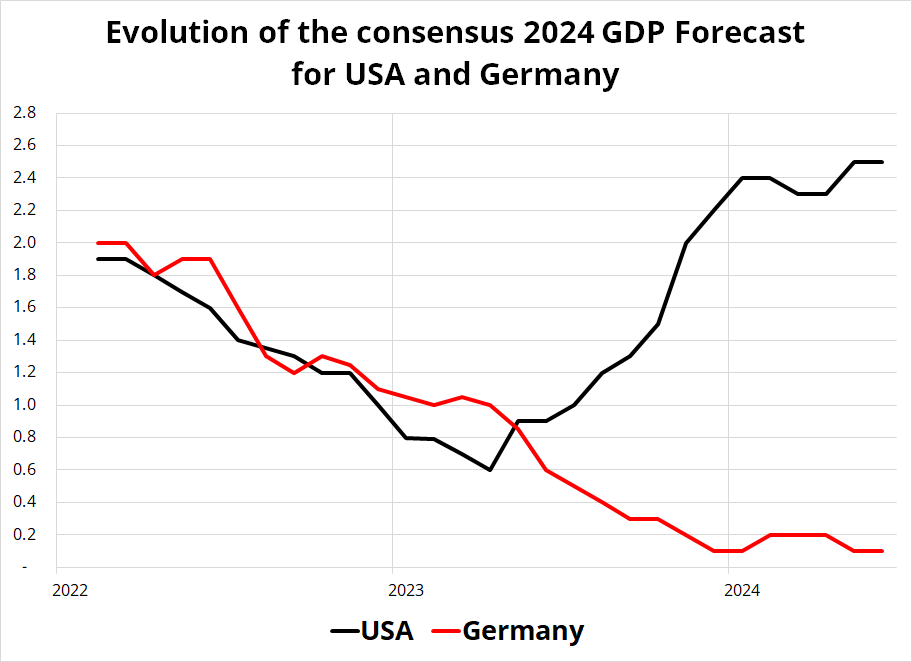
The German story has been one of below-trend GDP growth and rising unemployment. Of the six biggest companies by market cap in Europe, three are high-end consumer goods companies. LVMH, Hermes, and L’Oreal are three of the top six in there with Novo Nordisk, ASML, and SAP.
One of the big customers for those luxury products is China. As such, LVMH, Hermes and L’Oreal are all trading at YTD lows. Same deal with BMW and VW, the big German car brands. This is an interesting divergence as the DAX is still pinned to the all-time highs, riding the wave of global equity strength.
Overnight, the PMIs in Europe came in on the weak side and this supports one of my main views right now: The ECB is likely to cut in October. Odds have gone from 25% to 42% overnight, and I think they will continue to march higher as the ECB is a long way from neutral, the Fed has gone 50, and falling gasoline prices should keep downward pressure on headline inflation in Europe.
Meanwhile, I’m not so sure we are seeing anything more than a mid-cycle slowdown in the USA. The structural issues plaguing China and Europe are nowhere to be seen in the US as real estate is fine, the consumer is strong, GDP is on trend, and Initial Claims show that while hiring has clearly slowed, firing is still not an issue. I think US yields are bottoming.
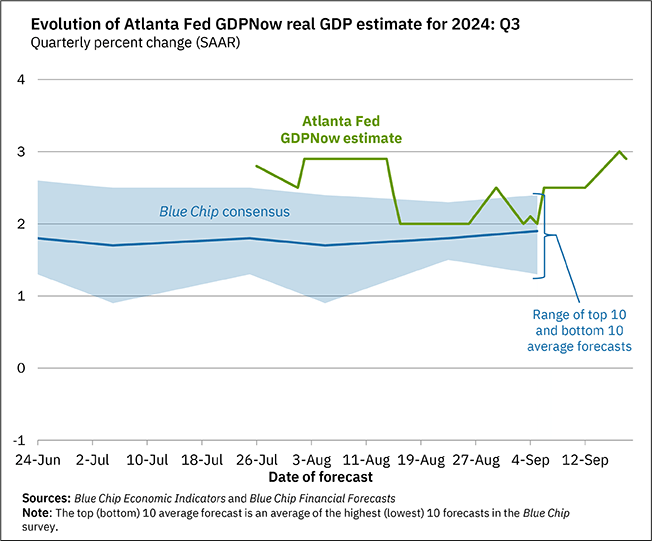
Zooming in a bit more, Atlanta Fed GDP remains nowhere near anything that would even vaguely look or smell like a recession. And it gets more and more reliable as the quarter rolls on, and new data adds precision.
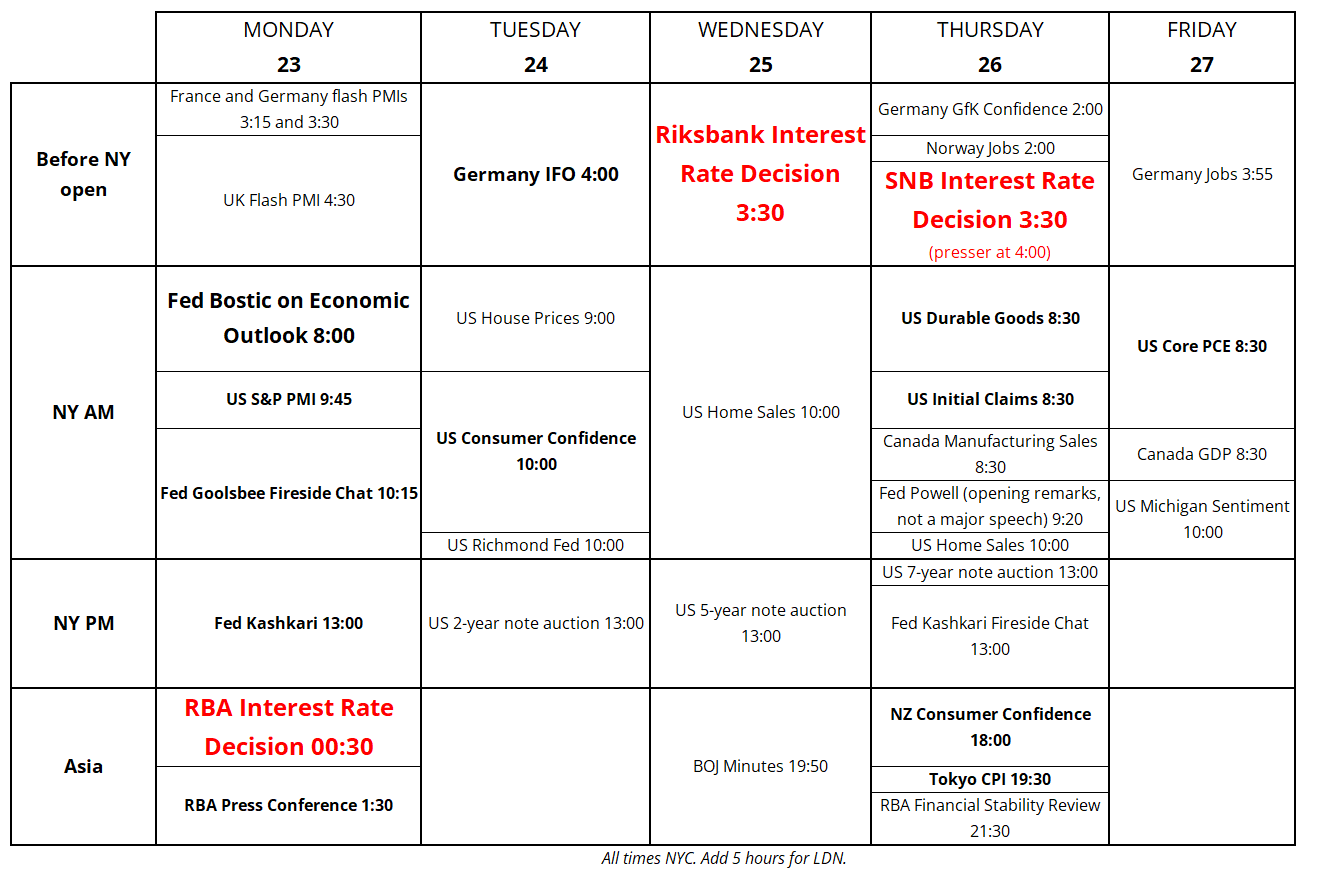
This week we have a plethora of USD-positive factors:
As such, I would lean towards a stronger USD this week and like short EURUSD or long USDJPY about equally. USDJPY has the random risk of the LDP vote, so I’m adding short EURUSD to the sidebar as a trade. The stop loss is pretty clear as a break of 1.12 means the idea is wrong. Rate differentials already point to something like 1.1050 and I think the data will continue to show USA vs. German economic divergence.
Two more polls over the weekend show Ishiba in the lead with 31% and 26% vs. Takaishi and Koizimu both around 17%. Ishiba is the JPY-positive outcome, and this is one more reason for me to avoid USDJPY.
Here it is:
A well-written essay condemning the grossest aspects of influencer culture:
https://www.freyaindia.co.uk/p/you-dont-need-to-document-everything
Have a comical day.
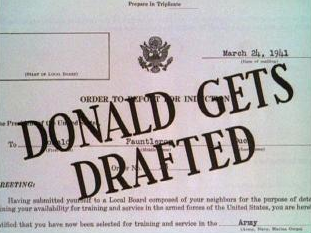
When the United States officially entered World War II following the 1941 attack on Pearl Harbor, Disney cast Donald in a series of animated propaganda shorts that had the tacit approval of the U.S. Army. The most famous of these was 1943’s Der Fuehrer’s Face. Early in one of shorts “Donald Duck Gets Drafted”, his draft notice flashes on screen, revealing his middle name.


This piece is mostly for people who are interested in backtesting

