
EURUSD looks high. Consumer Confidence estimates look low.
Bees can recognize different human faces

EURUSD looks high. Consumer Confidence estimates look low.
Bees can recognize different human faces
Short EURUSD @ 1.1128
Stop loss 1.1226
Take profit 1.0966
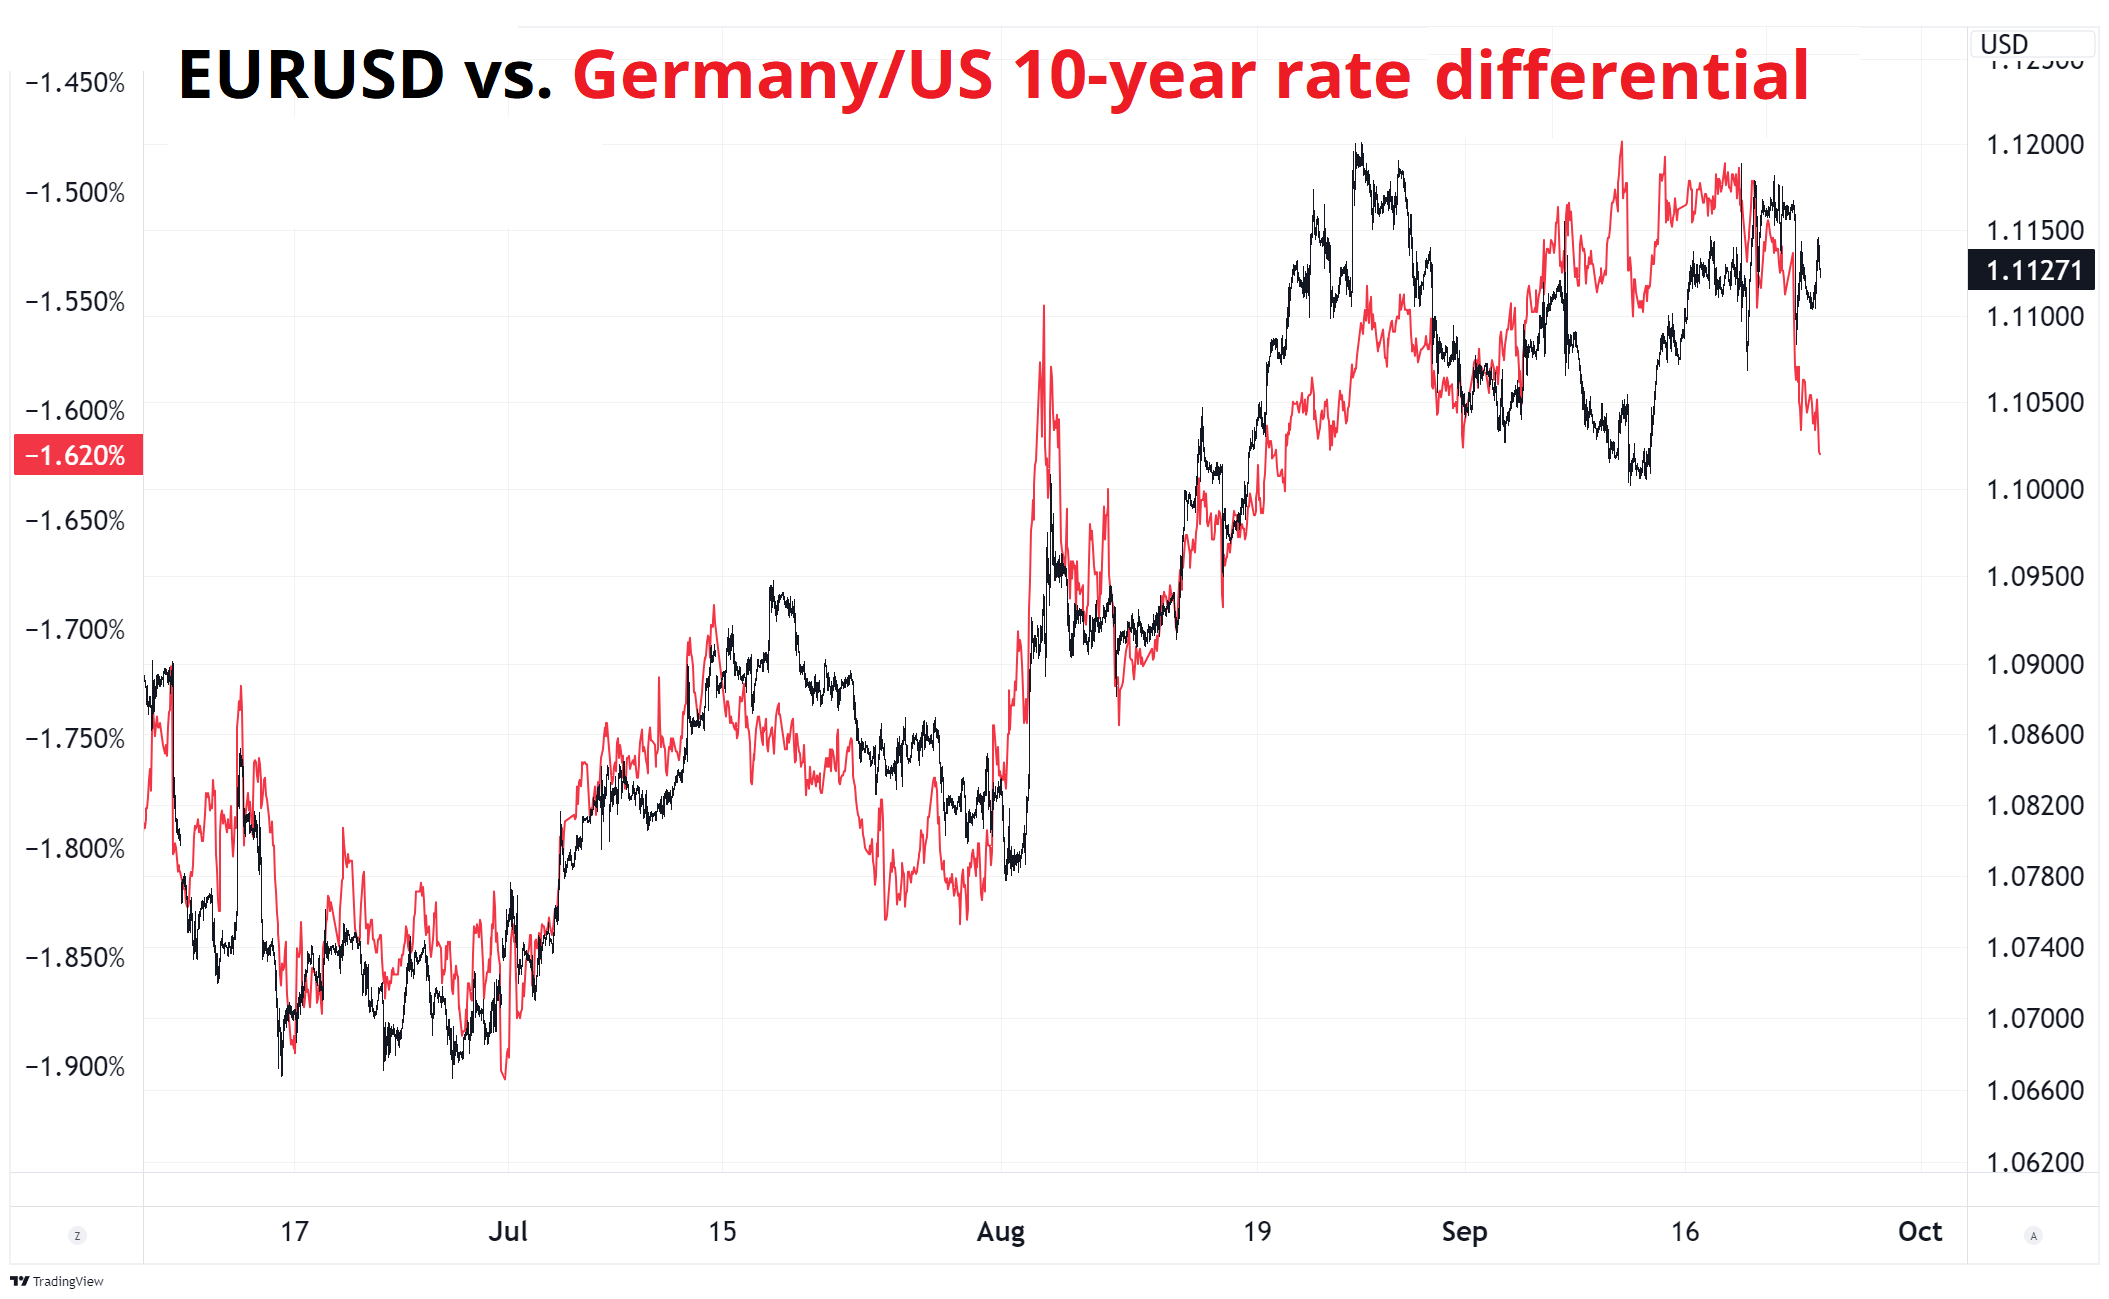
EURUSD remains a bit high relative to interest rate differentials. Here I show 10-year spreads, but 5s and 2s look similar. The overall USD weakness vibe is dominating for now as the 77th round of China stimulus has pushed USDCNH down. I still like EURUSD lower.
Part of my thesis for the long USD trade this week is that US Consumer Confidence should be higher than expected. I find generally that a simple model using gas prices, unemployment, and stock prices does a good job of capturing the major moves in Consumer Confidence and these moves tend not to be adequately forecasted by the median consensus, perhaps due to anchoring. This economist anchoring bias is one of many topics covered in Spectra School.
Here is the simple regression model and the current output. The signs of all the variables make sense (lower unemployment, lower gas prices, higher stocks = higher consumer confidence) and the r2 is 72%.
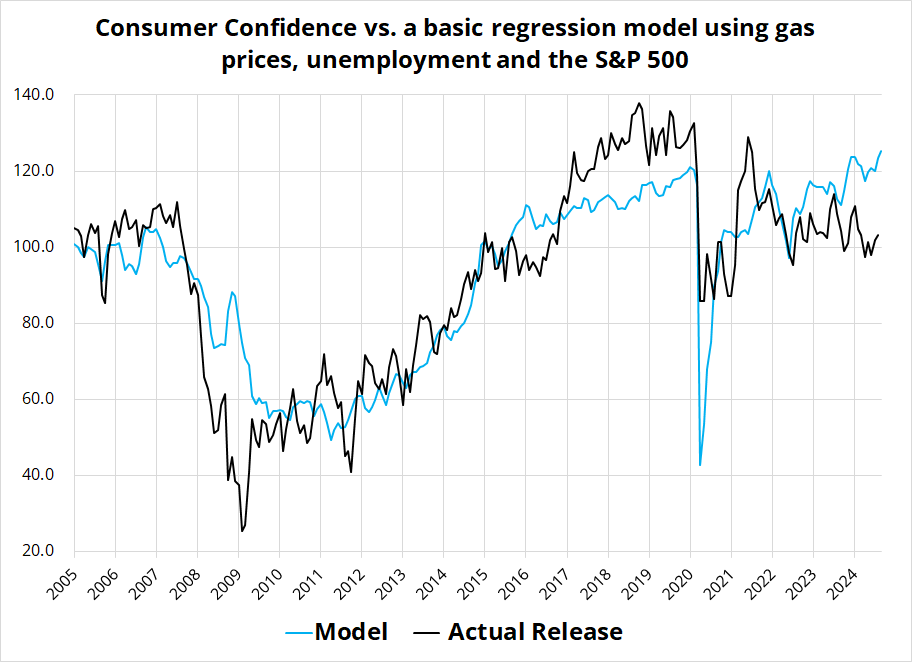
There’s a lot of noise in the official series, and I am not a big user of regression models, but I think this is a good heuristic when attempting to determine the asymmetry in the release. Ideally the number is strong, and I survive until the US corporates come in to buy USD on Wednesday and Thursday.
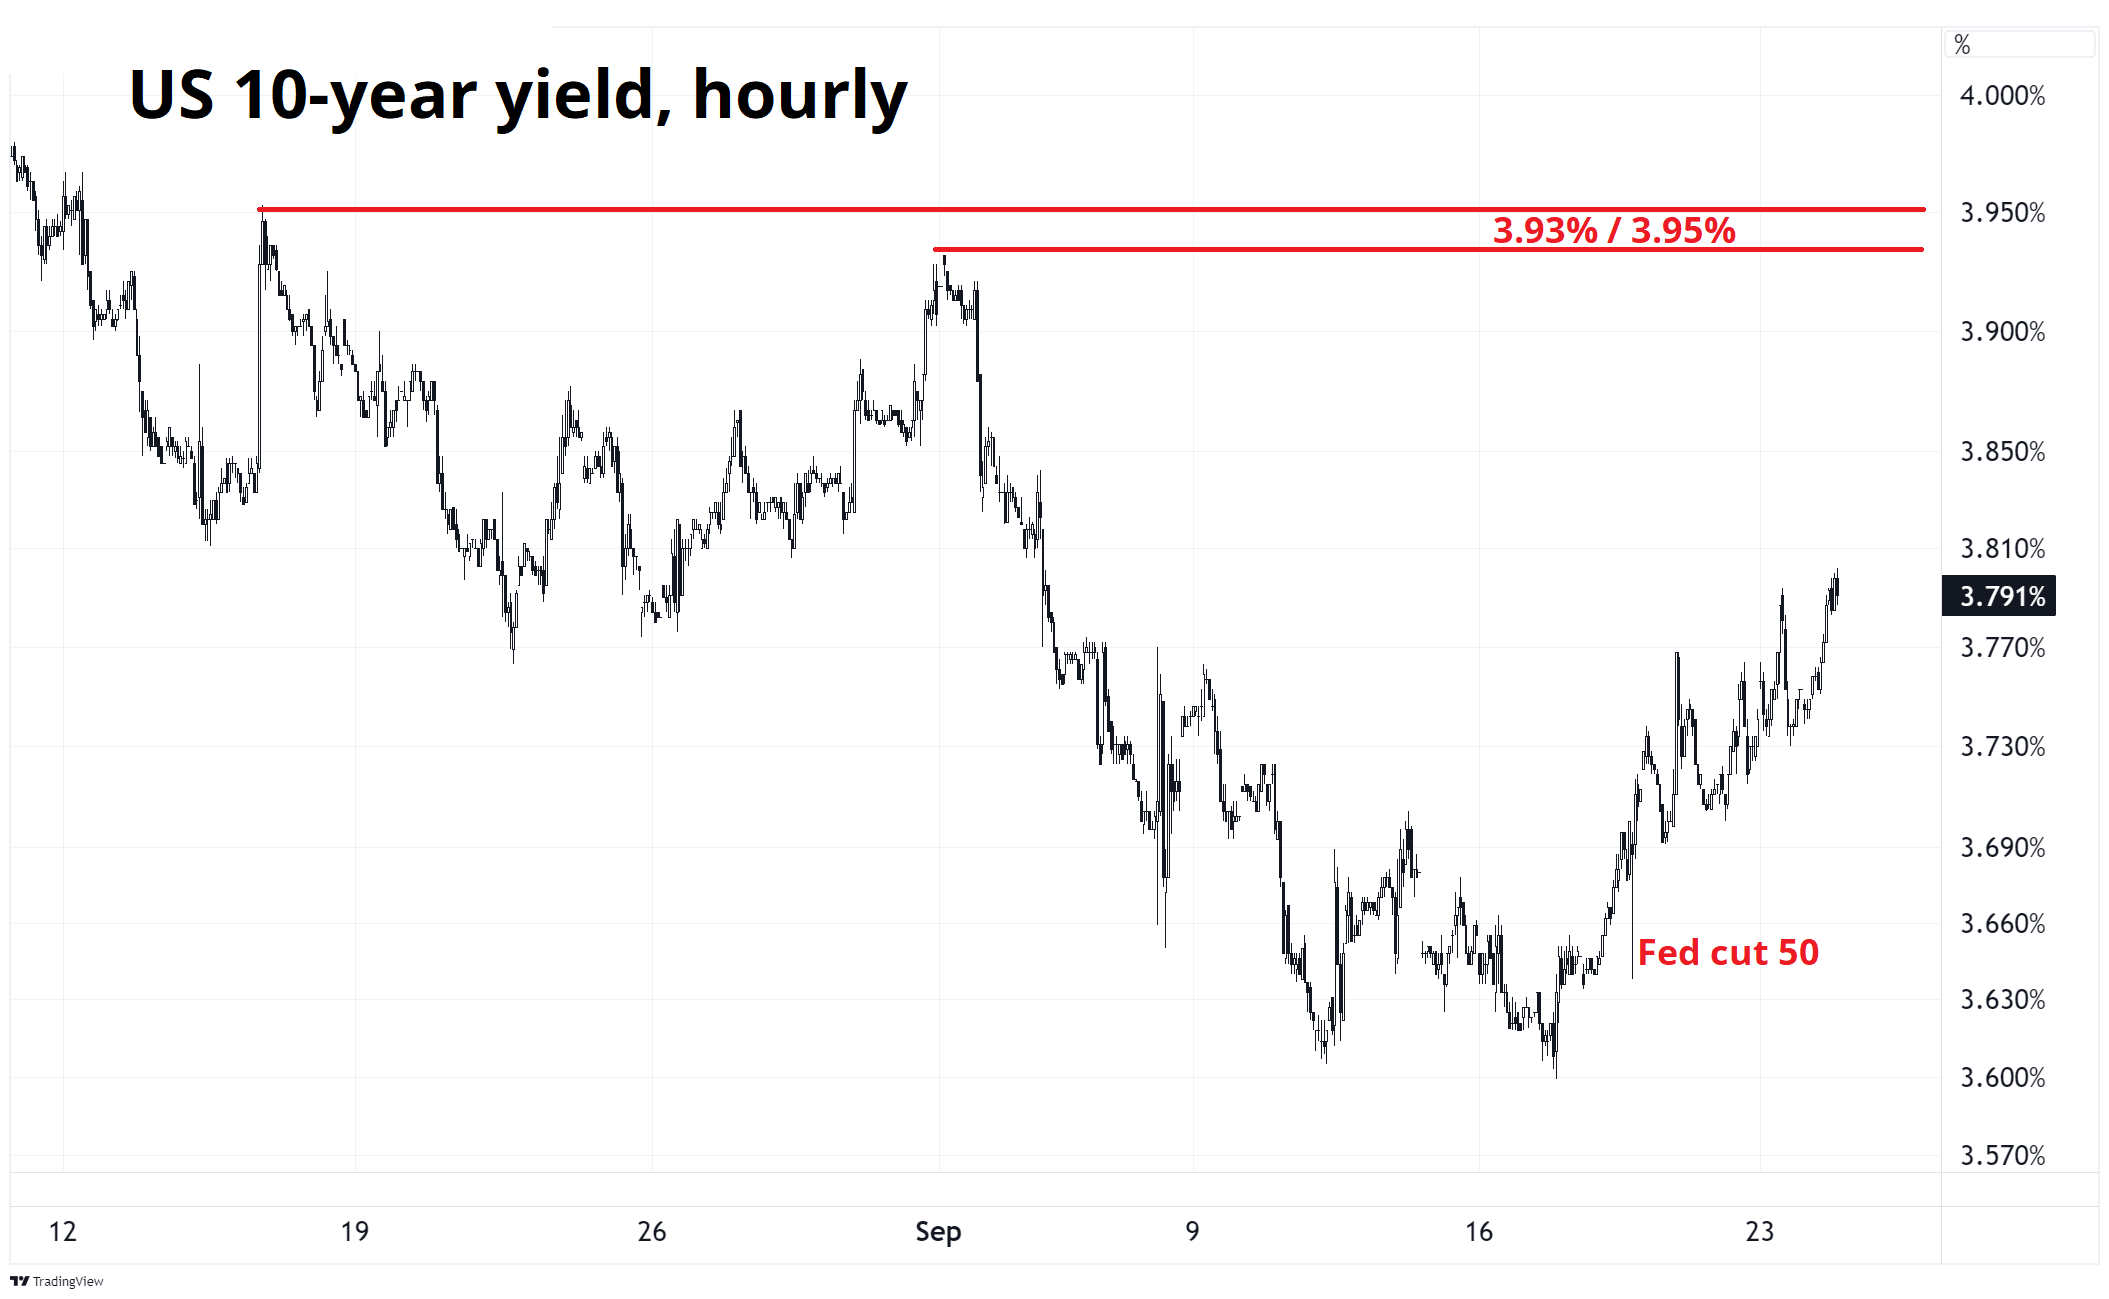
I am also counting on a continuation of higher US yields as the market sits long bonds despite higher yields after a surprise 50bp cut. If you’re short bonds, the take profit zone is around 3.93% in 10s as you can see here. Until we get to 3.93/3.95, I think long USDJPY will also work.
The fly in the long USDJPY ointment later this week is the potential Ishiba victory on Thursday night (3pm Tokyo on Thursday approximately). While I will note that there have been some big surprises in LDP elections in recent years, Ishiba put in another strong showing in a new poll overnight. That poll (from ANN) shows Ishiba with 31%, Koizumi with 20% and Takaichi in third with 15%.
Note that in all these polls, the undecided count is high. This ANN poll had 24% undecided, and the Mainichi poll yesterday had 34% on the fence. History shows surprises are possible, but I continue to like the idea of owing topside USDJPY for a rally this week that culminates around 145/146. If you own strikes up there, and we get there, you have super nice gamma for the LDP result.
Is China pushing on a string? Commodities are saying fool me a hundred times and fool me 101 times too. So let’s see. Look at Aussie yields, though, post-RBA. Hmm. Is AUD a trap up here?
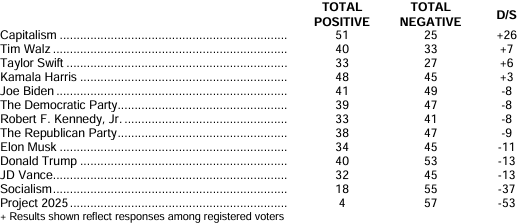
This NBC survey is full of interesting data points. The most compelling chart comes near the end, and I have shared it with you below. The table shows how the positive and negative views of a mix of registered voters (50/50 Democrat and Republican) with regard to various important and unimportant topics.
May your vision bee 20/20 today.
GBP hate has turned to love
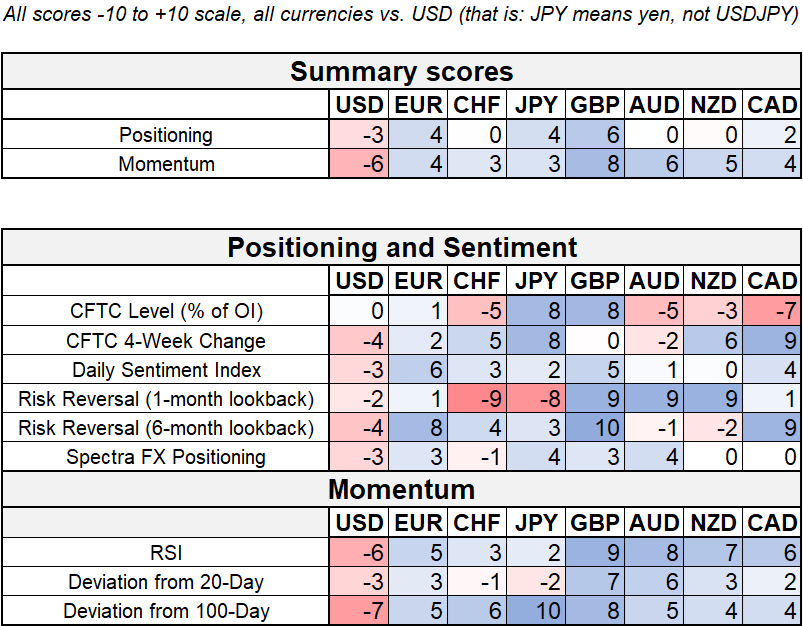
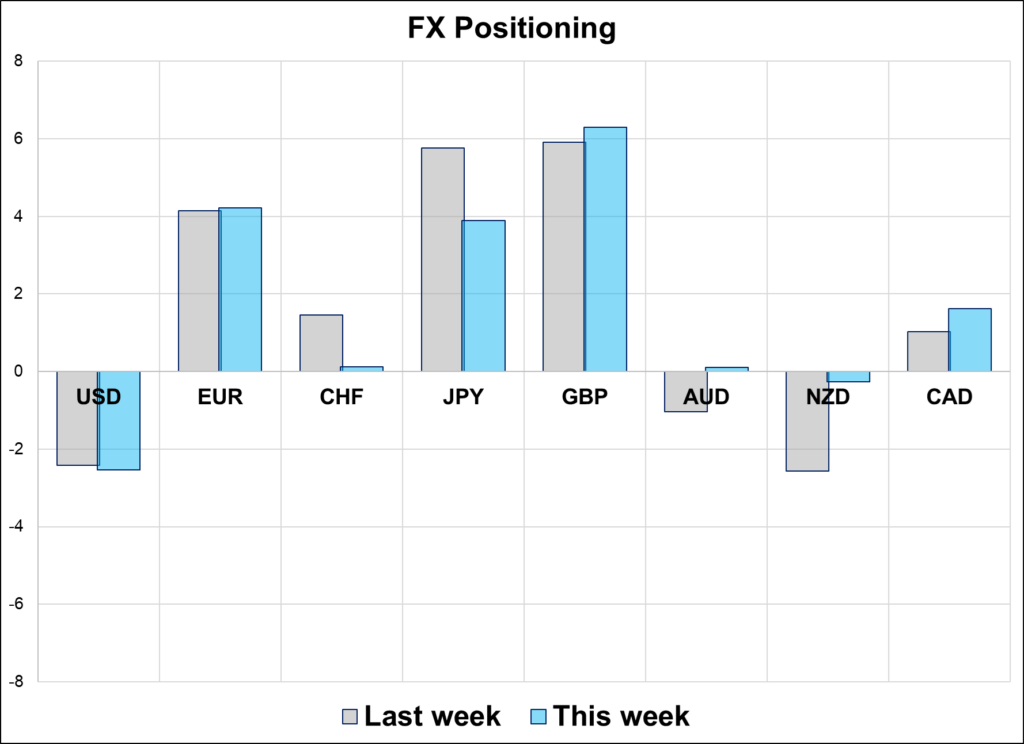
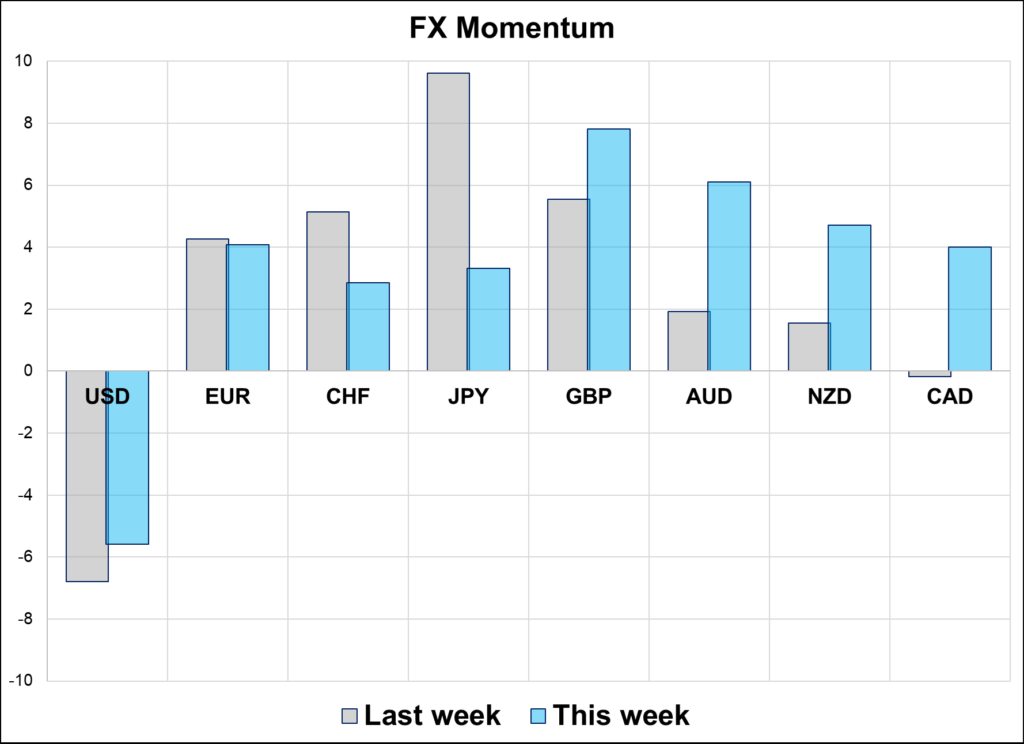
Hi. Welcome to this week’s report. The market is comfortable with GBP longs and remains long euro and yen. These positions are at risk if US yields turn as yield momentum is the primary driver of the flip from large USD longs a few months ago to substantial USD shorts now.
The stealthy runup in cable remains the most interesting aspect of positioning in FX as GBP continues to grind higher as dovish Bank of England bets unwind and the market goes short USD over the same time frame. There was a strong view in the macro community that those countries with the greatest household debt vulnerability would see more rate cuts and a weak currency.
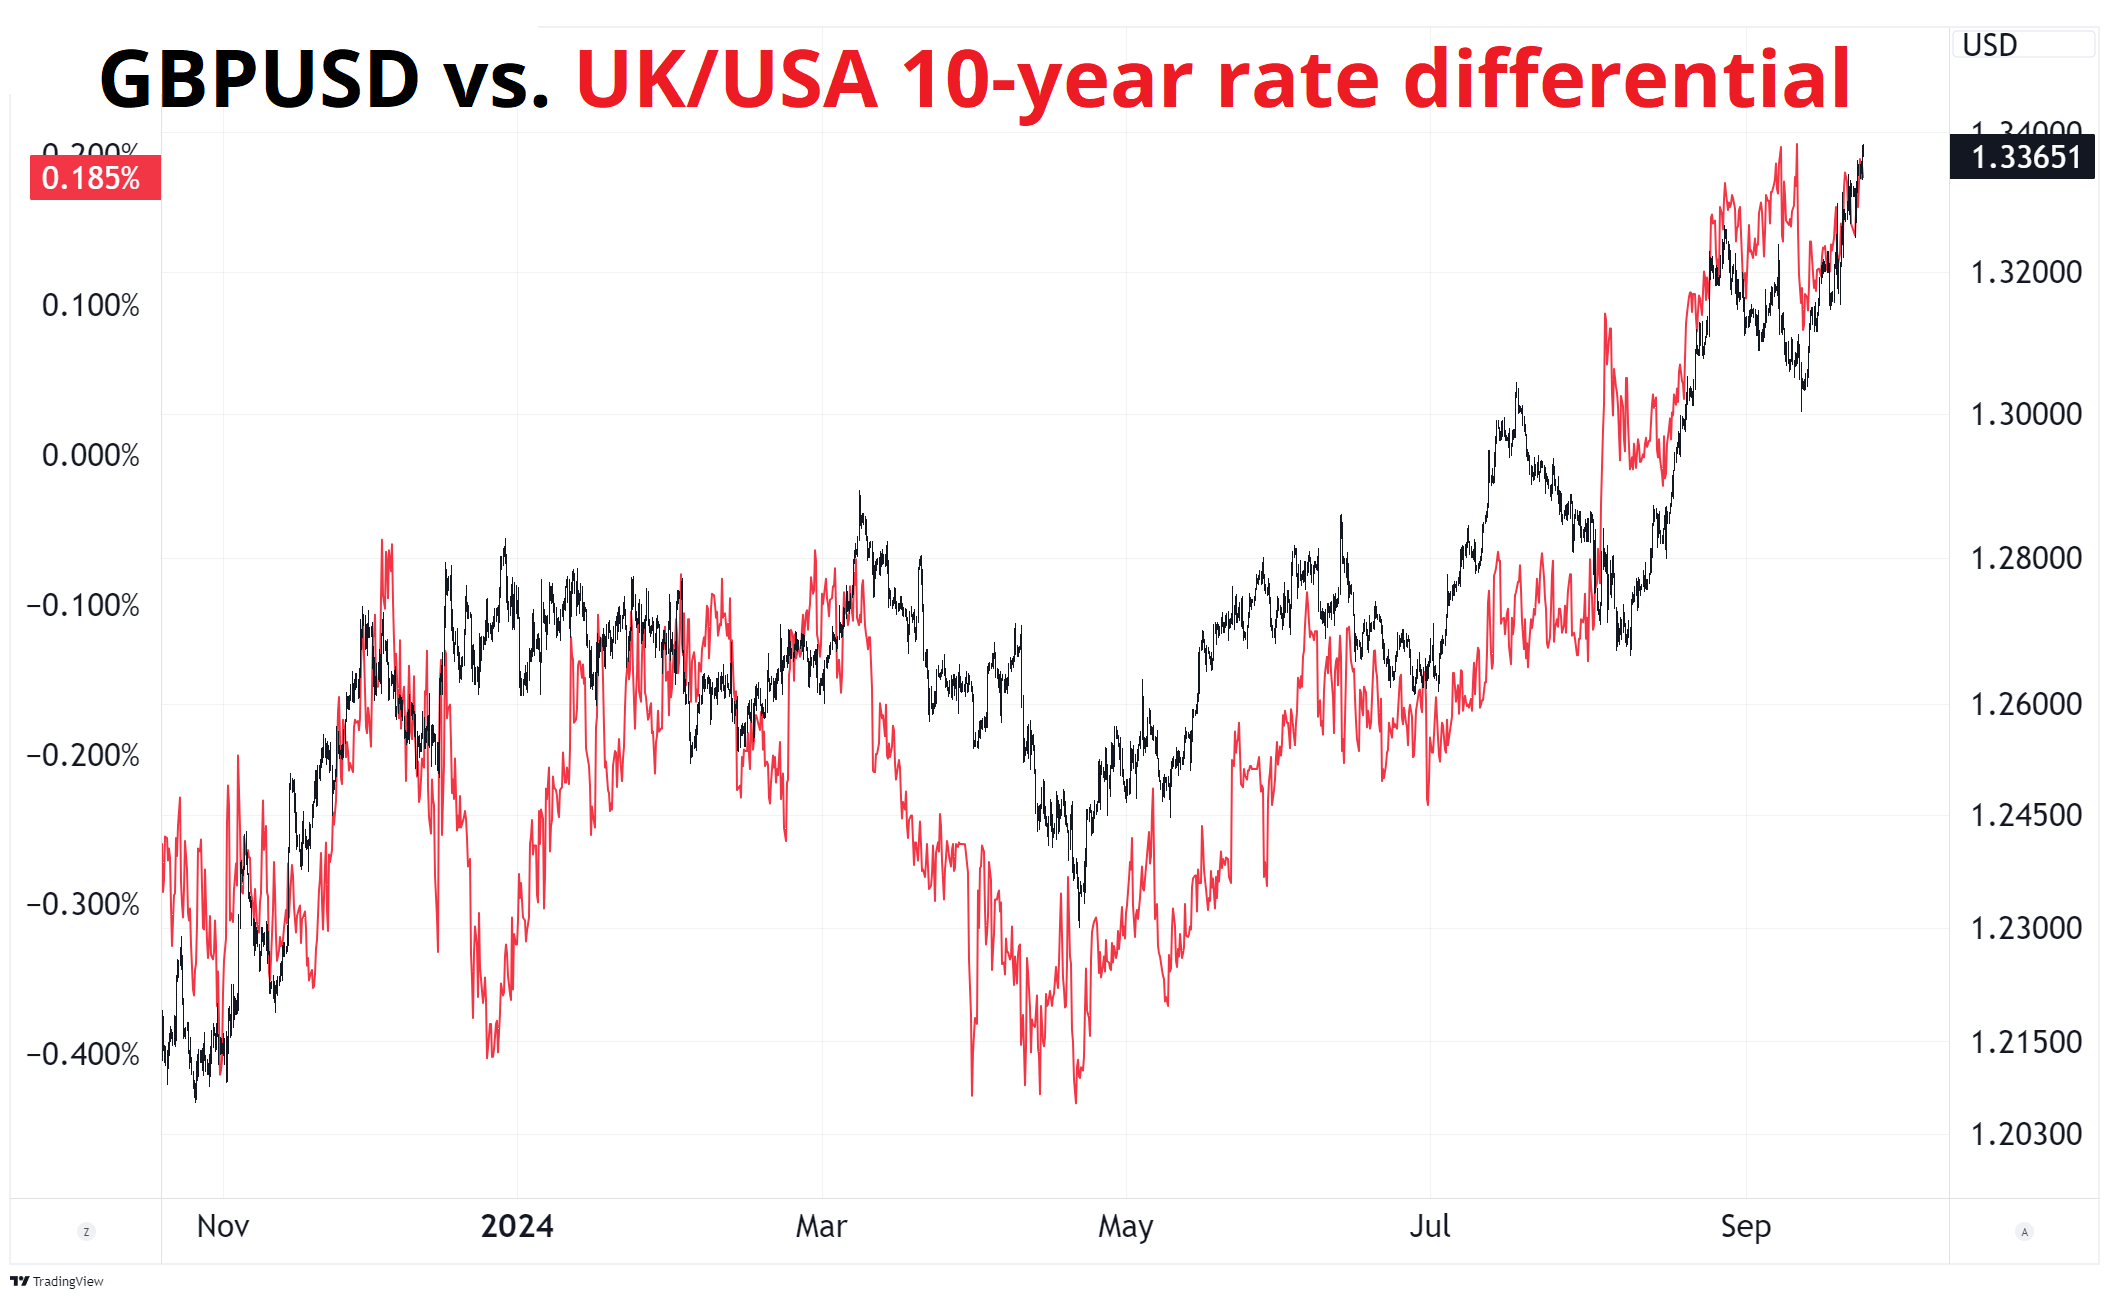
But these heavily-exposed countries have emerged unscathed as the global slowdown triggered by the massive rate hike cycle in 2022 has been somewhere between gentle and non-existent. Here you can see the rebound in UK yields, as Great Britain’s 10-year yield is now back above its New World counterpart. Note on the y-axis that the UK vs. USA 10-year spread has moved from negative 40 bps at the start of 2024 to +18.6bps now.
The next chart was a popular genre in 2023 and 2024 and many (including myself) thought it was a useful way to analyze performance in 2024 as the maturity walls, adjustable-rate mortgages, and consumer debt stories would all come to hamper growth in the countries most leveraged to housing. Instead, GBP is the best-performing G10 currency in 2024, and AUD, NZD, and CAD have all been fine. There has been no visible FX impact from high debt burdens.
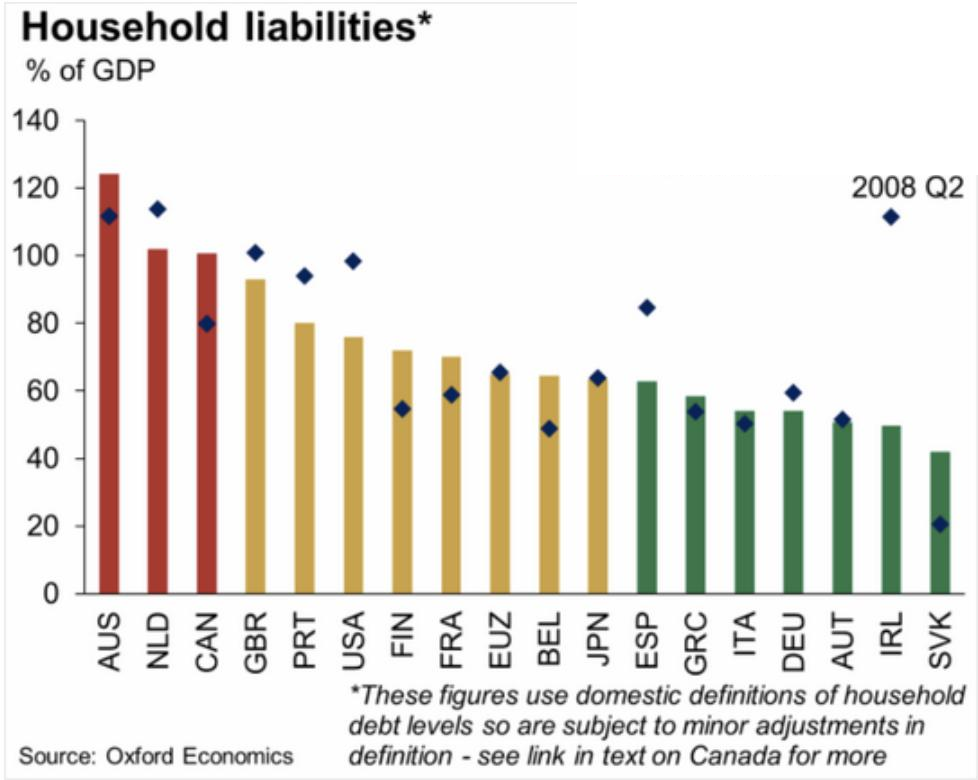
This despite meaningful discrepancies in GDP (average YoY for 2023/2024: US 2.7%, Australia 1.7%, Canada 1.0%, UK 0.9%, New Zealand 0.5%. Relative inflation has been more useful as a predictor of FX returns and even this has been nuanced as, for example, UK headline inflation has returned to target while services (and thus monetary policy) remain sticky. The market had the wrong framework for the UK and has been forced to unwind. The concomitant momentum has now encouraged the market to flip long.
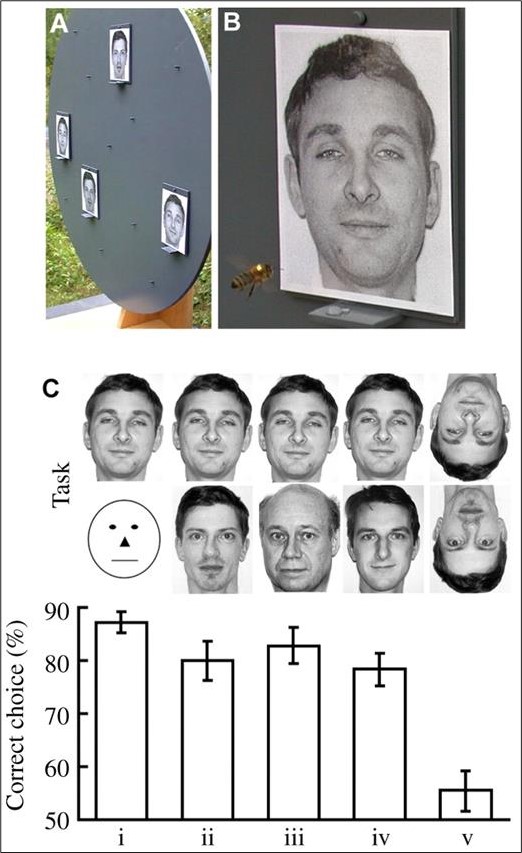
Honeybee (Apis mellifera) vision can discriminate between and recognize images of human faces.


This piece is mostly for people who are interested in backtesting

