FOMC
Today’s FOMC story is a simple one: Will Powell open up the distribution to reintroduce the possibility of hikes?
John Williams recently said that “if the data tell us that we need higher interest rates to achieve our goals, then we would obviously want to do that.”
Raphael Bostic said that if inflation does not continue to move toward the 2% goal, as he expects it will, central bankers would need to consider an interest-rate hike. “If inflation stalls out or even starts moving in the opposite direction, away from our target, I don’t think we’ll have any other option but to respond to that. If it seems that the level of restrictiveness that we’re at today is not enough to do the job or get the job done, I’d have to be open to increasing rates.”
If Powell says hikes are not a consideration, that’s dovish. If he says hikes are possible (this year?) that’s hawkish.
There has been no shortage of bad moments for the Fed during Powell’s tenure, most notably:
- “We are a long way from neutral” in 2018. That was the high in yields.
- 2019 framework review and introduction of FAIT to let inflation “run hot” right before the biggest inflation explosion in decades.
- “Inflation is transitory.” Continuing to stay loose and buy assets into 2022, goosing a prolonged 2-year inflation surge that led to 500 bps of hikes.
- Top Fed officials resign after trading their own investment accounts around Fed announcements while America was locked down under the cloud of COVID.
- Failure to understand, oversee, and properly regulate Silvergate.
- Pre-announcing rate cuts in late 2023 despite inflation well above target, triggering a rebound in animal spirits and inflation.
So it would be ironic and not too surprising if the Fed were to pivot back to rate hikes just as the economy finally peaks. There is an element of reflexivity, of course. For example, saying “we’re a long way from neutral” can be the trigger for a move higher in rates that slams animal spirits and ultimately delivers lower yields. So perhaps if Powell delivers a hawkish pivot of the dovish pivot today, we get a repeat of 2018? Maybe.
I have been skeptical of the soft (survey) data throughout this cycle because it’s been like the inverted yield curve—worse than useless. Still, it’s hard to completely ignore the spate of weakening soft US data of late. Higher inflation and weak sentiment are a toxic cocktail that make the Fed’s job difficult.
I find it surprising that the Conference Board Confidence figure dropped so much yesterday with stocks and housing both near all-time highs. Are consumers feeling the inflationary pinch that crushed sentiment in 2021 and 2022?
As a refresher, the fruit salad below shows the evolution of the US hard and soft economic data in the years after COVID. The numbers represent the ranking of the economic figure that month, relative to the past 60 months (5 years). “1” means it’s the strongest on a 5-year lookback and “60” means it’s the weakest. You can see how sentiment buckled when inflation shot higher early in the cycle, while the hard data remained robust.

The hard data is less obviously stonking now, but part of that is simply down to the strong 2022 comps. That US economy was reopening after a pandemic. I feel like the odds are highish that we are entering some sort of soft patch here and a hawkish Fed today might seal the deal, 2018-style.
Trading FOMC
At the risk of making a boring prediction: I think today’s market response to Powell is symmetrical and orthodox. Cartloads of USD have been bought and positioning is very long dollars. Therefore, if Powell were to say “we are not considering hikes”, I think the dollar will get smashed. On the other hand, if yields reprice higher and the hike side of the distribution enters the chat, FI vol will ramp and the USD will just keep going. I think USDMXN and AUDUSD work both directions depending on what he decides to say.
Final Thoughts
The peerless Fred Goodwin ran a poll on safe havens, and I find the results surprising. Here they are.
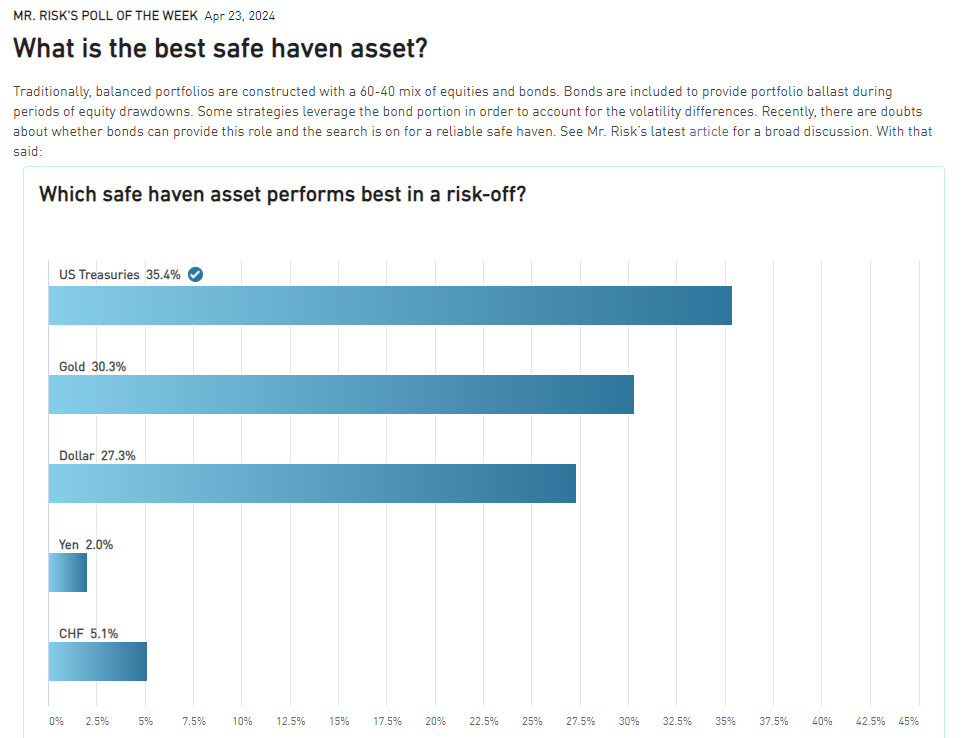
I take issue with most of these:
- Bonds are not a safe haven if the “risk-off” is triggered by resurgent inflation.
- Gold is not a reliable safe haven. It’s often a liquidity thermometer and often sells off in tandem with risky assets. That’s exactly what it’s doing recently.
- The dollar will not be a safe haven in a US slowdown. I think the 2000-2004 analog is the right one here as in that period the dollar sold off along with stocks as money flowed out of the NASDAQ bubble and into other stuff. Given the rapacious demand for US assets throughout the last decade, a reduction in appetite for US stocks isn’t bullish USD.
- Yen and bonds are the same trade. If 35.4% of people think bonds are a good safe haven, it makes no sense that only 2.0% think JPY is.
These points all bolster the idea that going forward, there is an acute shortage of safe assets.
Have a C-plus day (or better).