I think we are in a slow topping process for USDJPY and cross/JPY. CHF weakness remains impressive.
HT CR!

I think we are in a slow topping process for USDJPY and cross/JPY. CHF weakness remains impressive.
HT CR!
Stop loss 112.16
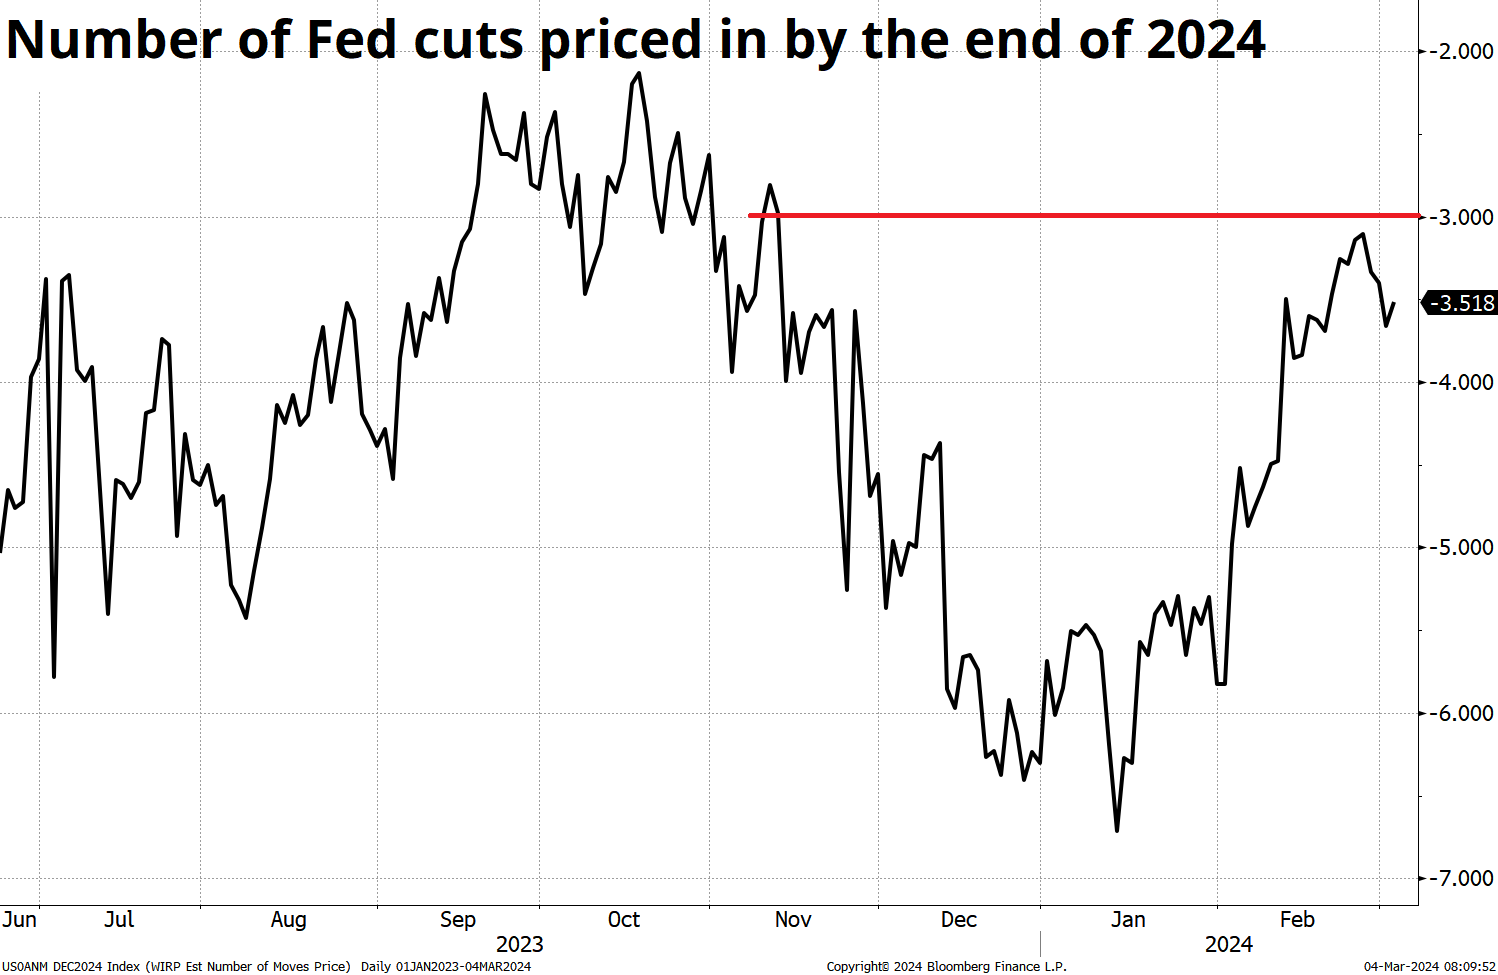
FX remains themeless as the central banks are all thinking about thinking about cuts but not yet ready to reduce rates. It’s possible that we get some insight from the BoC, ECB, or BOJ this week as somebody will have to go first and it could easily be the Bank of Canada or Team Lagarde. I think US pricing will remain sticky here as 3 cuts priced in matches the dots, and this includes a bit of risk premium around a modal outcome of only 2 cuts now.
To price fewer than three cuts in the US, I think we will need a strong February CPI (released March 11). This would stamp out the argument that the inflation rebound in the US is purely an artifact of weird new year seasonality and could potentially open up a move in the dots in May (to two cuts) and a move in the STIRT market well before that.
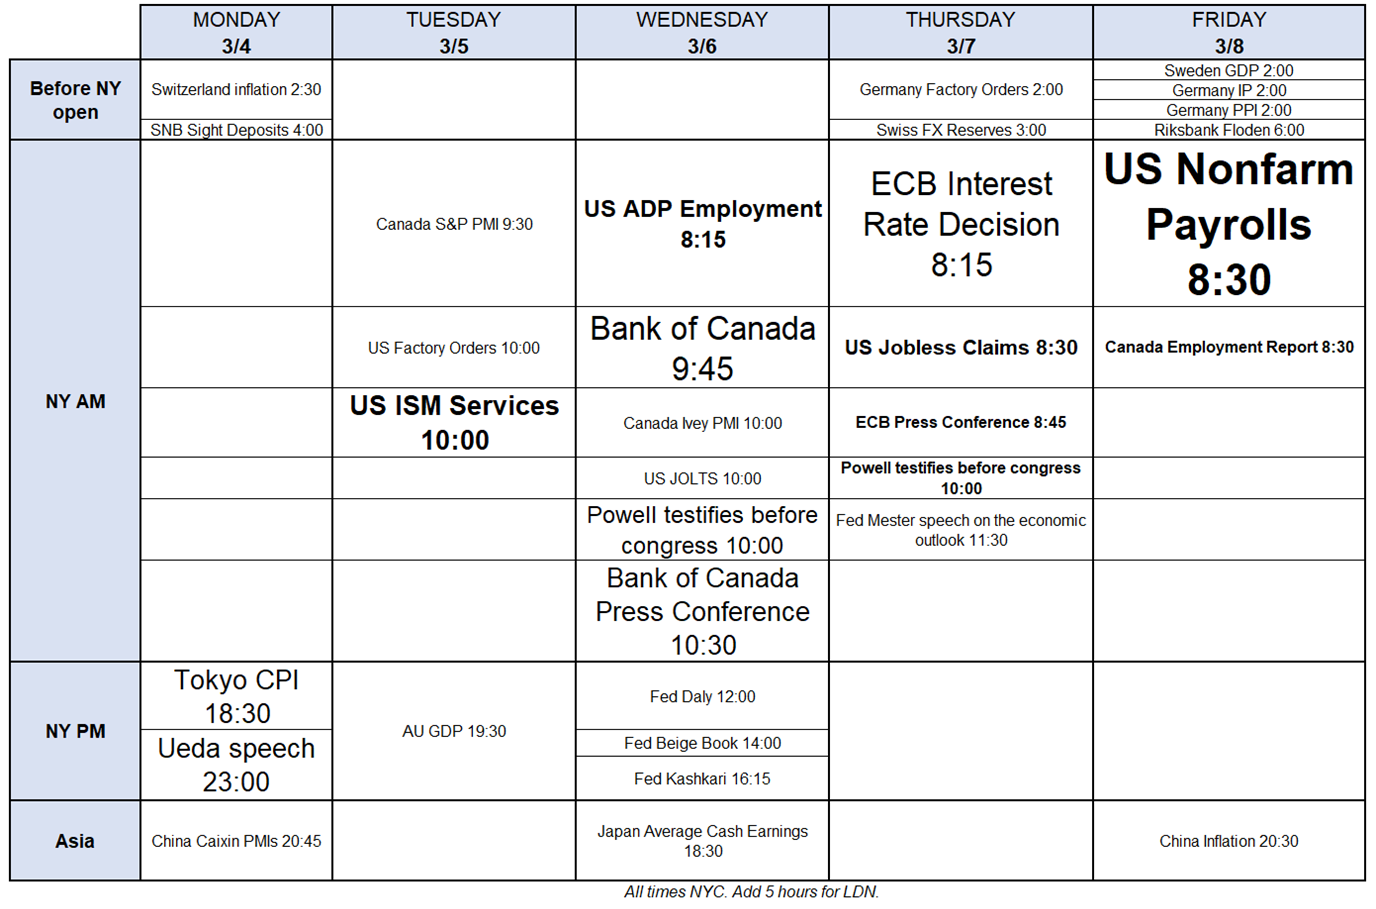
We do get a bunch of labor market data this week, but I don’t think those releases are game changing for the Fed. Sure, they matter, and weakness in jobs would soften the reacceleration narrative a bit, but the Fed (and most central banks) are fine with a strong labor market as long as inflation is coming off. Policy is mostly geared to inflation right now, not employment.
With lack of narratives in FX, the main play these days remains long carry. EURMXN looks particularly attractive still as the US election is too far off to worry about, carry is high, and volatility is low. Our carry/vol sheet shows CHFMXN, EURMXN and CHFHUF as some of the best non-JPY carry trades right now. In contrast, as my view is that US yields will struggle to go up from here, I don’t think JPY crosses are as good a place to hide out long carry for now.
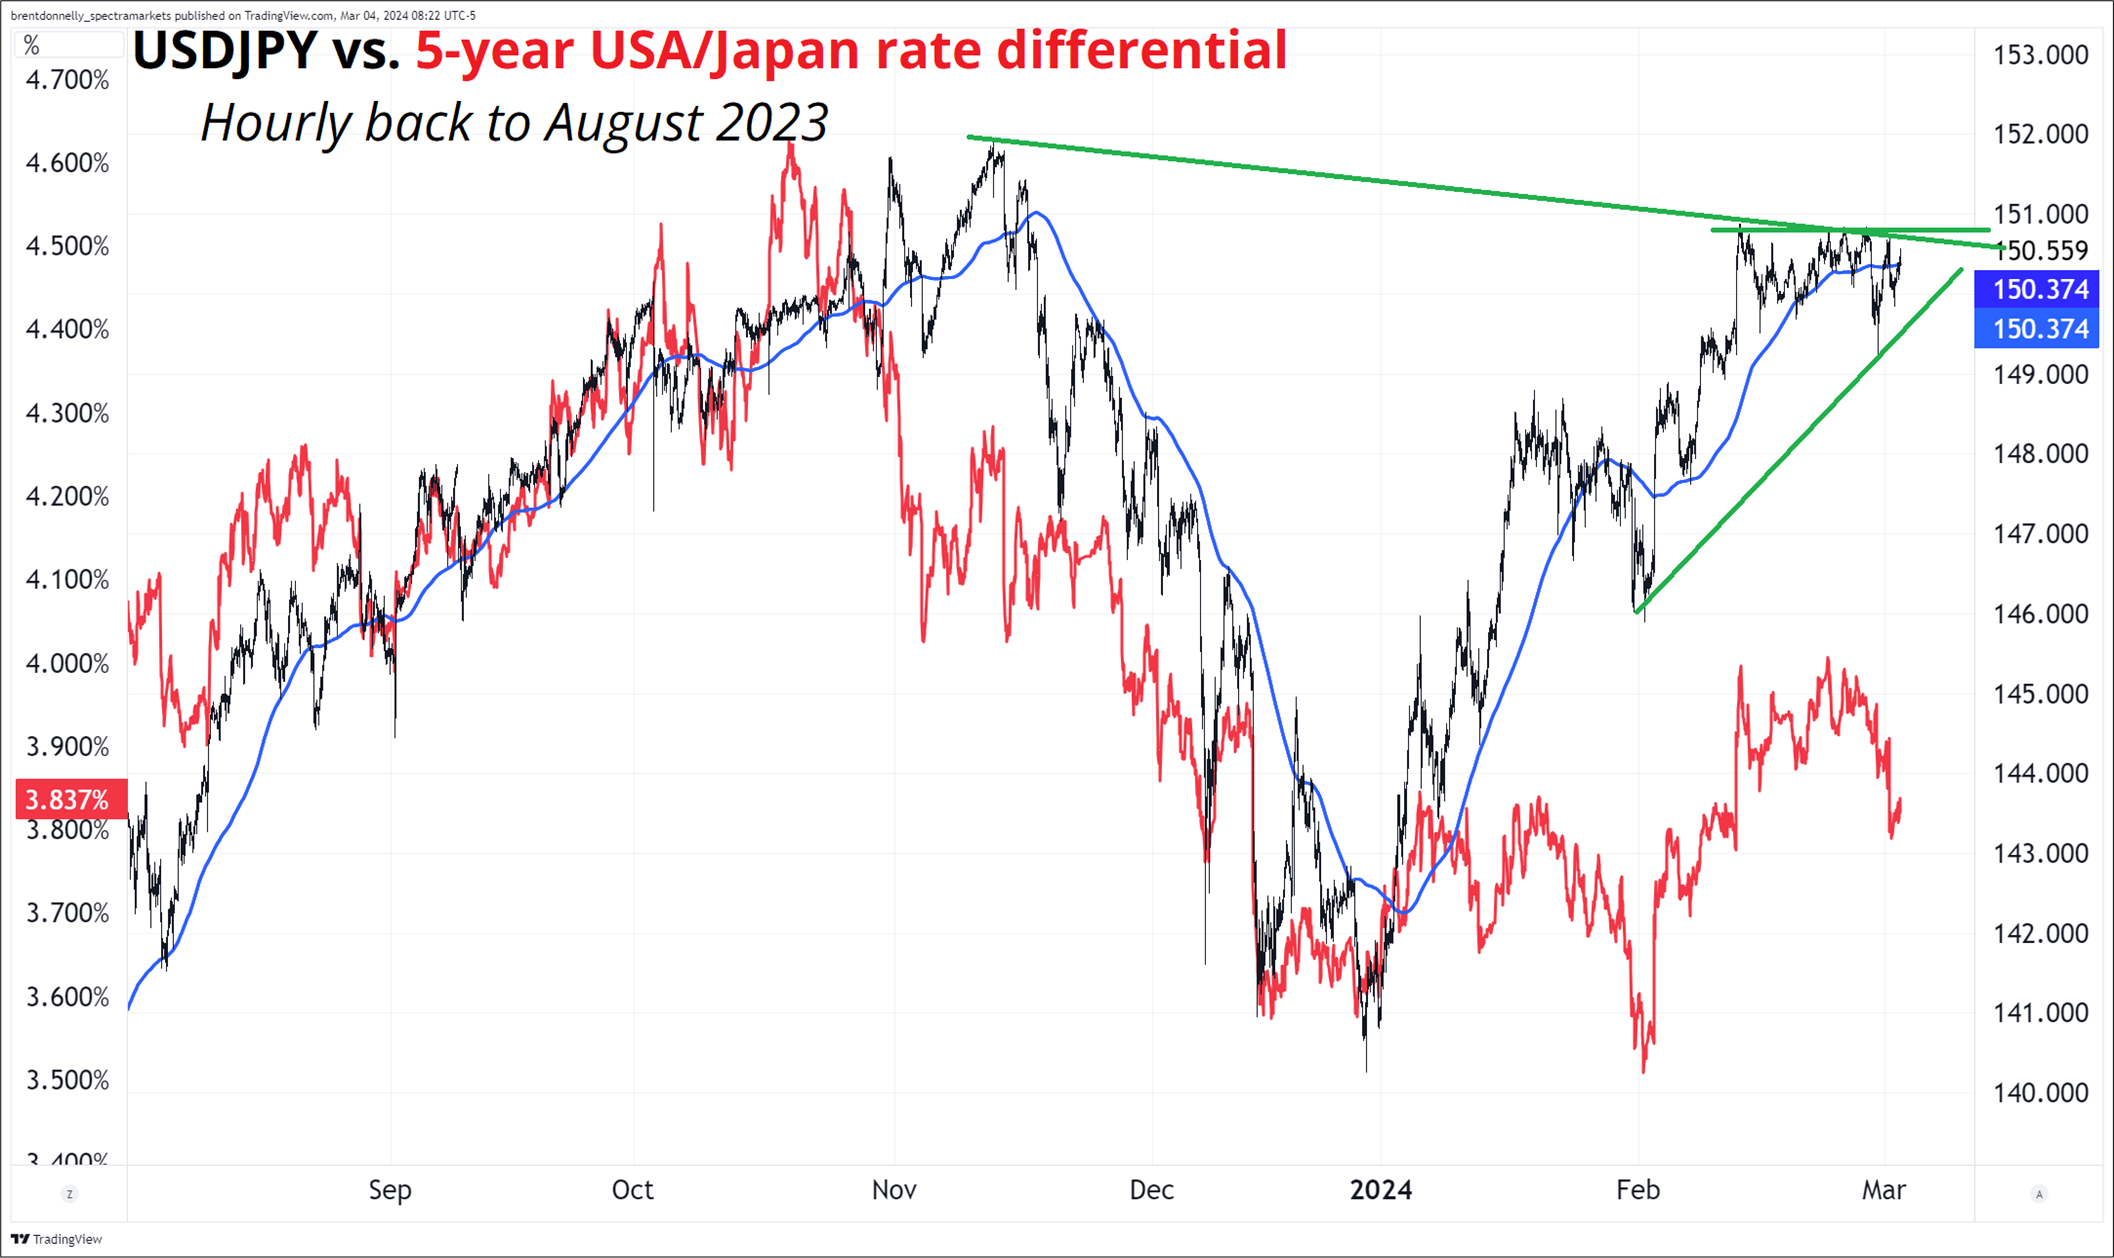
USDJPY has been in a super-tight consolidation since the 13FEB CPI release, with one aggressive foray to 149.20 on month-end USD selling. We have now made seven tops at 150.60/80 and yields are substantially lower than where they were last time we were up here. There is plenty of downside potential if we get any sort of catalyst now as USDJPY looks high, momentum is low, and we could be set to make a lower high compared to the 152 double top in late 2023. We’re also making a bit of a rising wedge, triangle formation (marked in green).
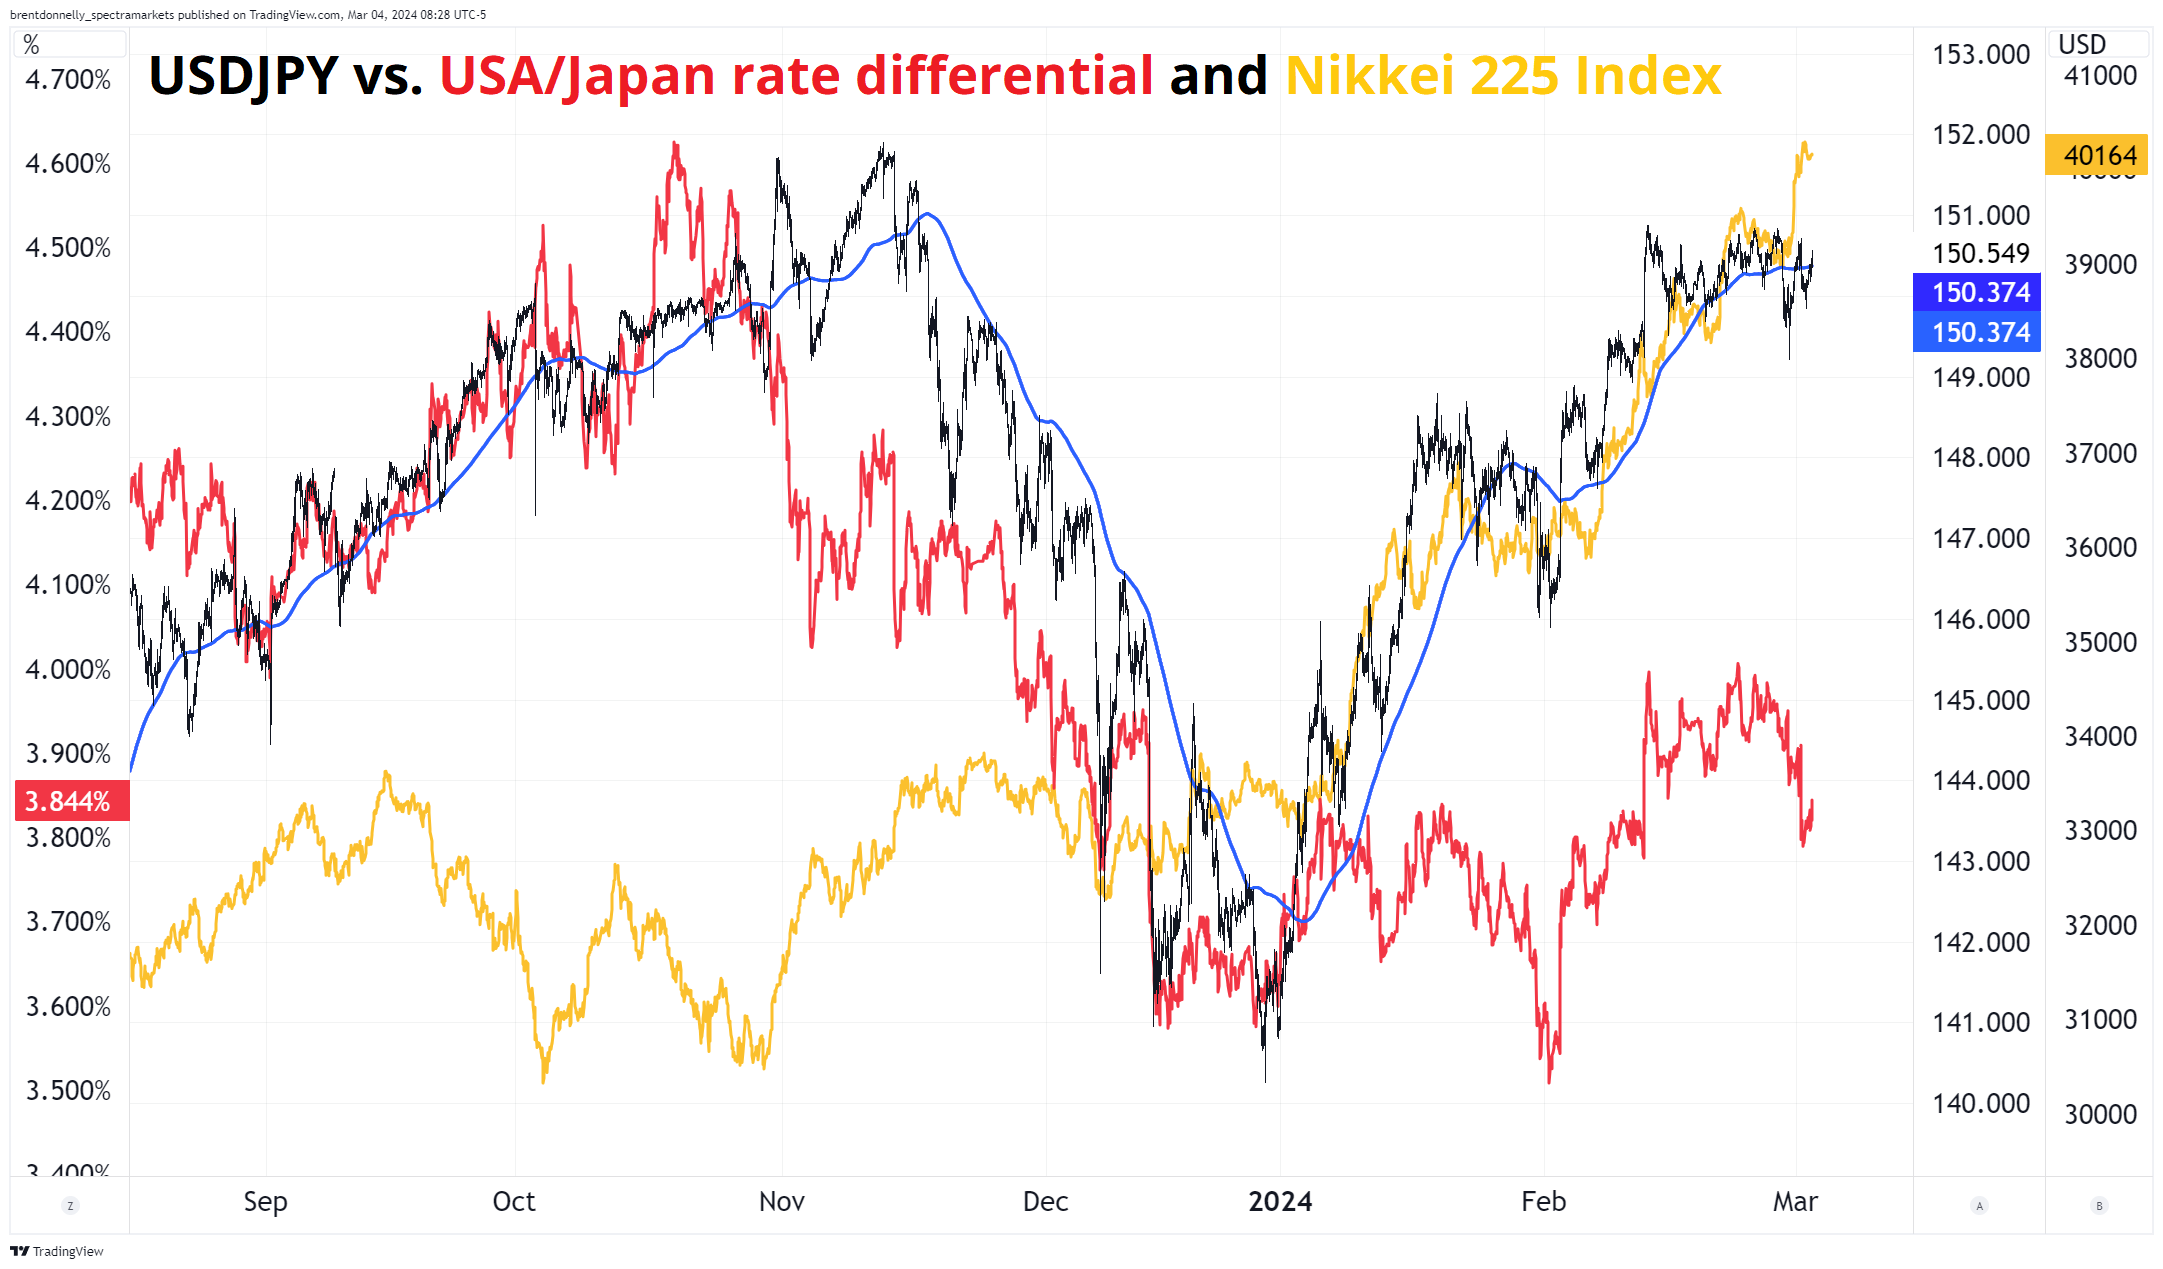
If we add the Nikkei to the same chart, you can see that recently the fit between Japanese equities and USDJPY has been better than the fit with yields. I don’t find those non-yield relationships tend to hold for long, but still, if you’re bearish USDJPY or cross/JPY, you would definitely prefer to have lower Nikkei, not higher. Something to watch.
I added one update to the calendar: Ueda at 23:00 NY time tonight. Things have become a bit confusing in Japan with the wages (Shunto) on March 13 looking like a key event. Ueda’s commentary of late has been mixed but the market is slowly zooming in on March or April for a hike. With US yields toppy for now, USDJPY tending to trade heavy into mid-March (before rallying into fiscal year end), and the BoC more likely to be dovish than hawkish… I still like selling the rally in CADJPY (see sidebar).
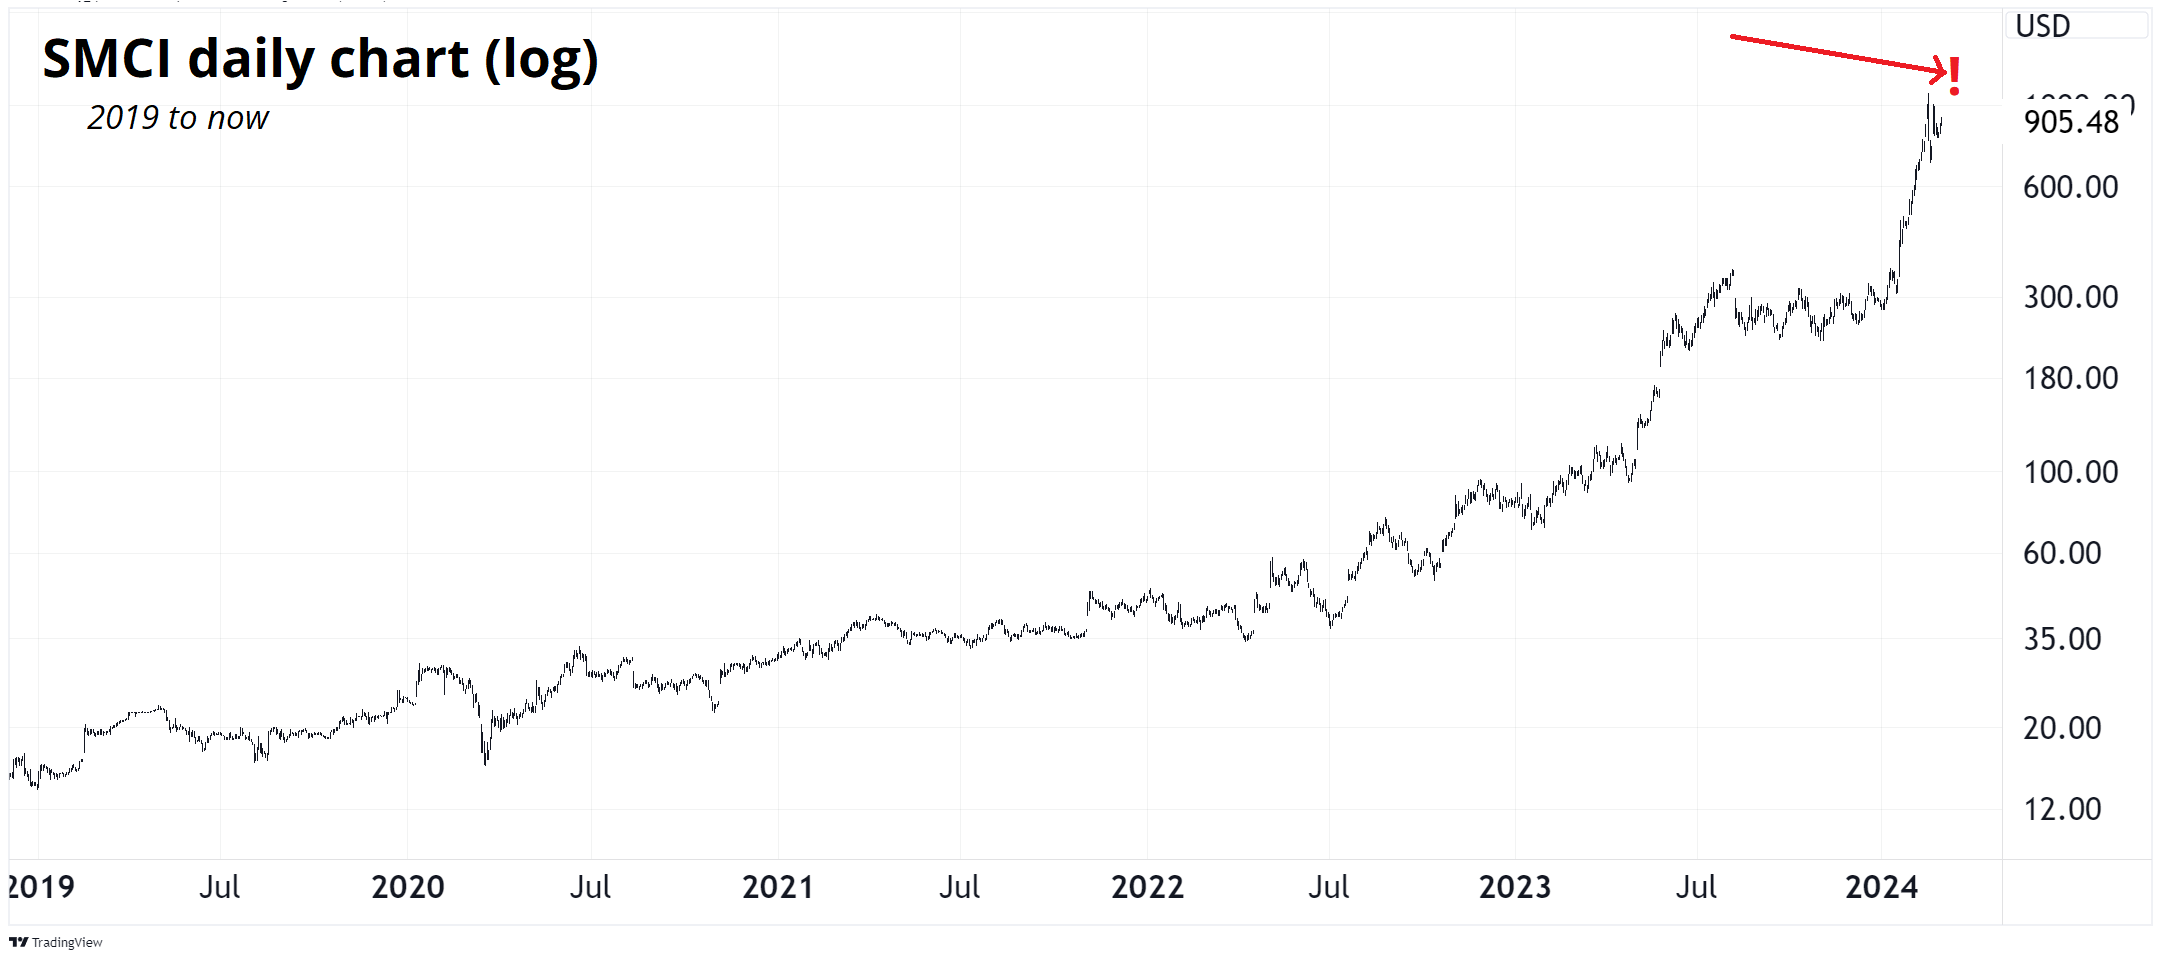
SMCI is trading 1050 pre-market as it is set to be added to the S&P (effective Monday, 18MAR).
Have a fantastic day.
HT CR