
Today’s FOMC is probably noise while the series of bottoms in gasoline, lumber, housing, and business sentiment might not be.
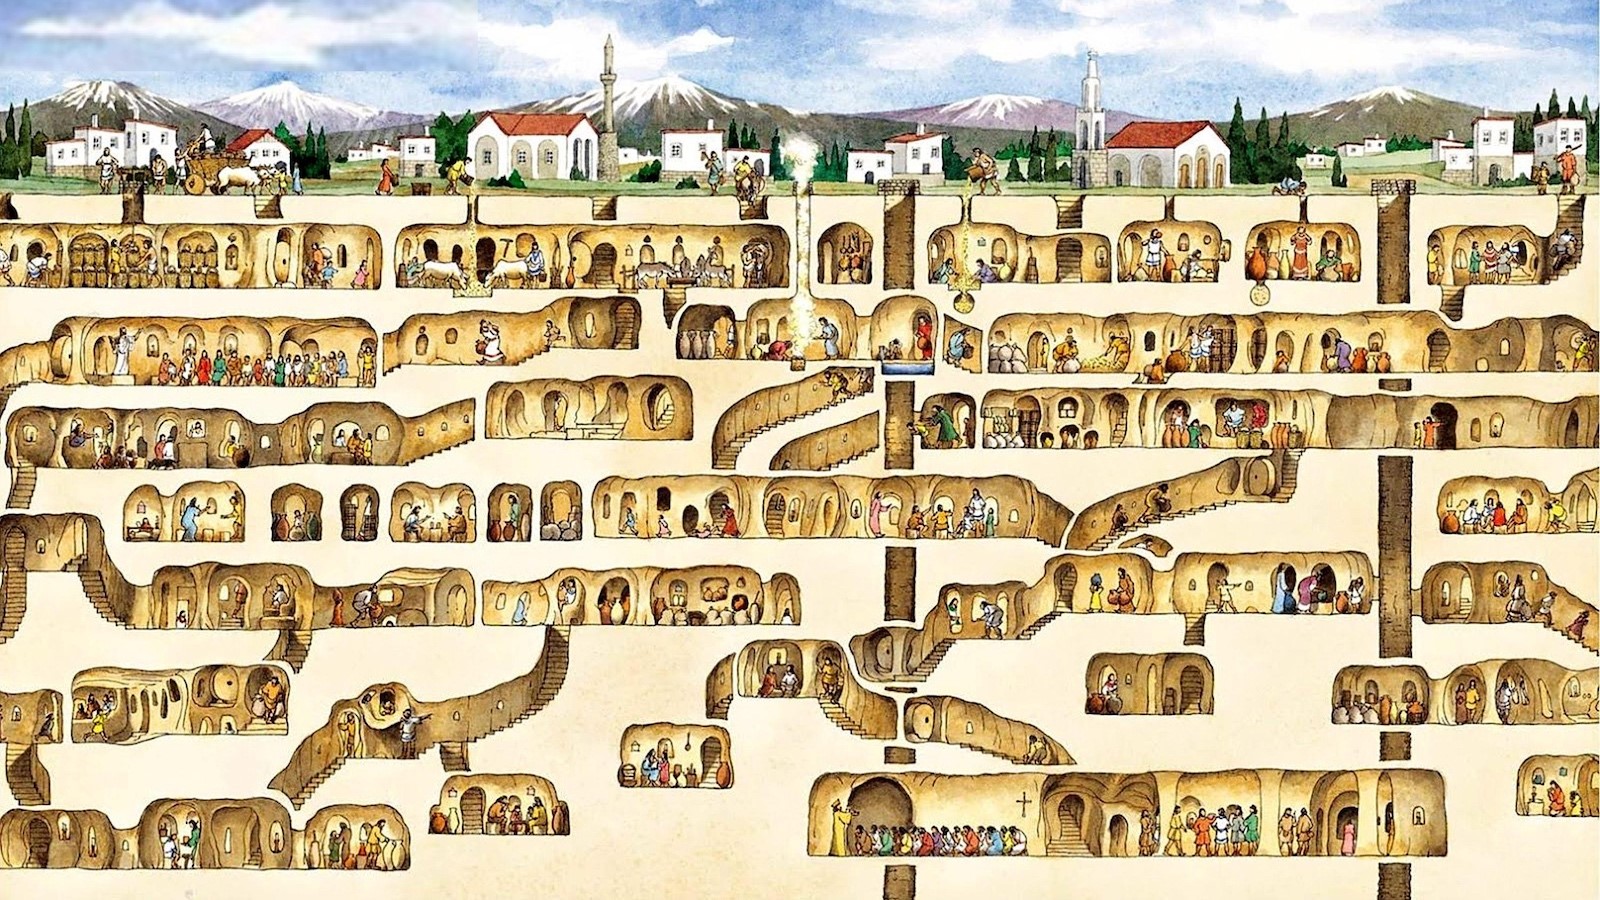
There is an underground city in
Turkey that housed more than
20,000 people and their livestock
for almost 2000 years.

Today’s FOMC is probably noise while the series of bottoms in gasoline, lumber, housing, and business sentiment might not be.
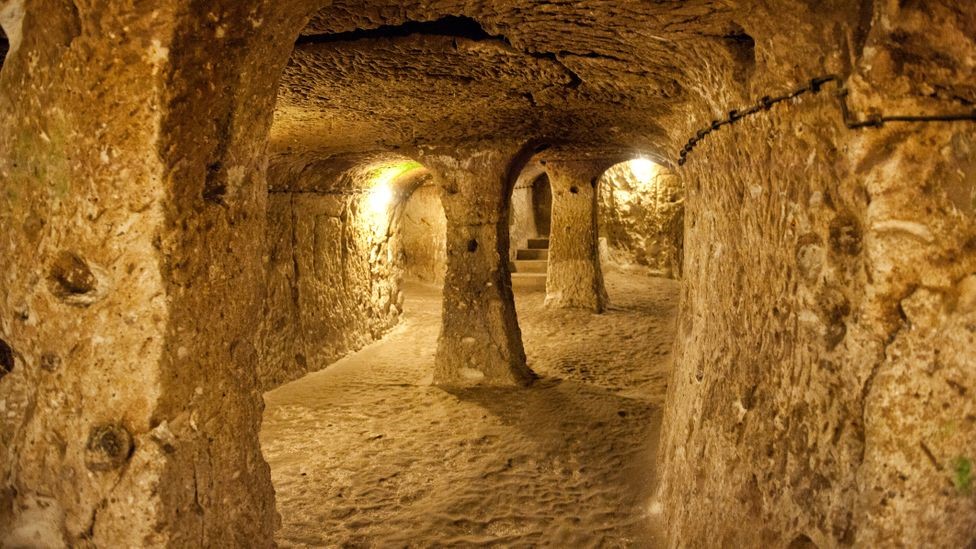
There is an underground city in
Turkey that housed more than
20,000 people and their livestock
for almost 2000 years.
Short NZDCHF at 0.5950
Stop loss 0.6055
Take profit 0.5827
Long 07FEB EURGBP call
spread 0.8870/0.8920 risking
22 GBP bps to make 50
Spot ref. 0.8850
February 1, 2023
There is a nice window here for all three central banks (Fed, ECB, and BoE) to flex their hawkish chops with the market in a happy mood, financial conditions loose, and the immaculate disinflation narrative in full force.
I generally have a decent imagination, but I am struggling to imagine what Powell can say today to meaningfully change the narrative around the future path of Fed policy. Sure, cuts are priced in, but it’s not really like the market is overwhelmingly expecting the Fed to cut. It’s simply that there is a distribution of outcomes that includes more cuts than hikes in H2 and one of those paths is where the Fed cuts 250bps because of an abrupt slowdown. Therefore, the average of all the possibilities is rate cuts in H2, but I would say the median expectation for cuts is subdued.
The setup going into FOMC is kind of strange, too, as there are not many players expecting a dovish outcome and yet stocks are up 8% going into the meeting and the USD is going in on the lows. Maybe what the Fed says just doesn’t matter that much these days and it’s more about the data than the guidance.
For the past 12 months, I have generally been saying that it’s not that important what the Fed says, because their guidance is not super credible and their forecasts are no different from those of the private sector. Therefore, it’s the data that matters, not Fed pontification. Whether you have 6, 60, or 600 PhDs running workhorse economic models, if those workhorse models are not good at predicting the future (which they have not been in this cycle)… Does it really matter what the models suggest for policy? The Fed used to be viewed as some sort of oracle. Not anymore.
My view is markets care about data, and today’s FOMC is noise. That said, the removal of the risk event will give comfort to the consensus soft landing / China reopening trade and therefore the path of least resistance will continue to be a weaker dollar.
Perhaps more interesting is the recent bottoms put in by the four horsemen of the 2021 inflation apocalypse. Recall that throughout 2021 and 2022, all eyes were on gasoline, lumber, used cars, and rent as each took a turn capturing attention on the way up, then on the way down. Here are gas and lumber, indexed to 1.0 on 01FEB2022.
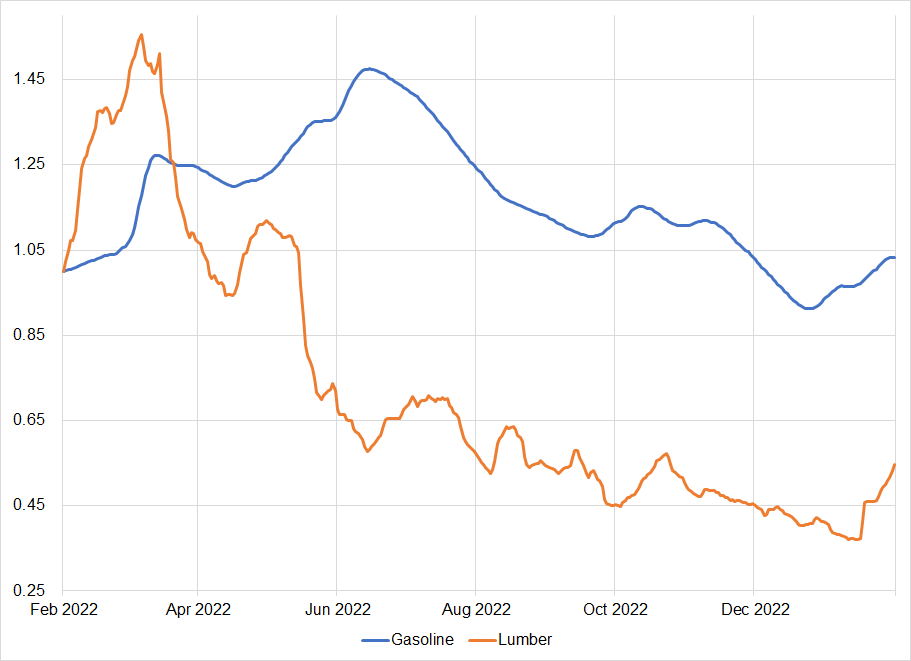
US inflation peaked in mid-2022 and has been falling since. There has been this growing feeling of relief like: “OK, at least we know where the ceiling is!” The next question was: “Where will inflation find a floor?” but the tricky thing for trading (as I wrote about a few times) was that it would take many months for us to know where that floor was because we needed multiple months of inflation data.
Is it possible that the continued resilience in the US labor market and the inflationary impact of China reopening means we are nearing the low point for the immaculate disinflation narrative? Base effects will help the official data still for a while, but the market is forward looking as we saw with the epic SPX bottom at 3500 on the October CPI report. People are talking about backward-looking annualized 3-month changes in recent CPI data but if we look forward, rising commodity prices probably mean that 3-month annualized rate is about to go higher from here.
None of this is super relevant to today’s FOMC meeting, but it could mean that US 10-year yields will find a base here and the next real move in yields is up, not down. Most January 2023 business sentiment indicators also look like those charts of gasoline and lumber, with encouraging moves up off the lows. For example, all these have ticked up this month:
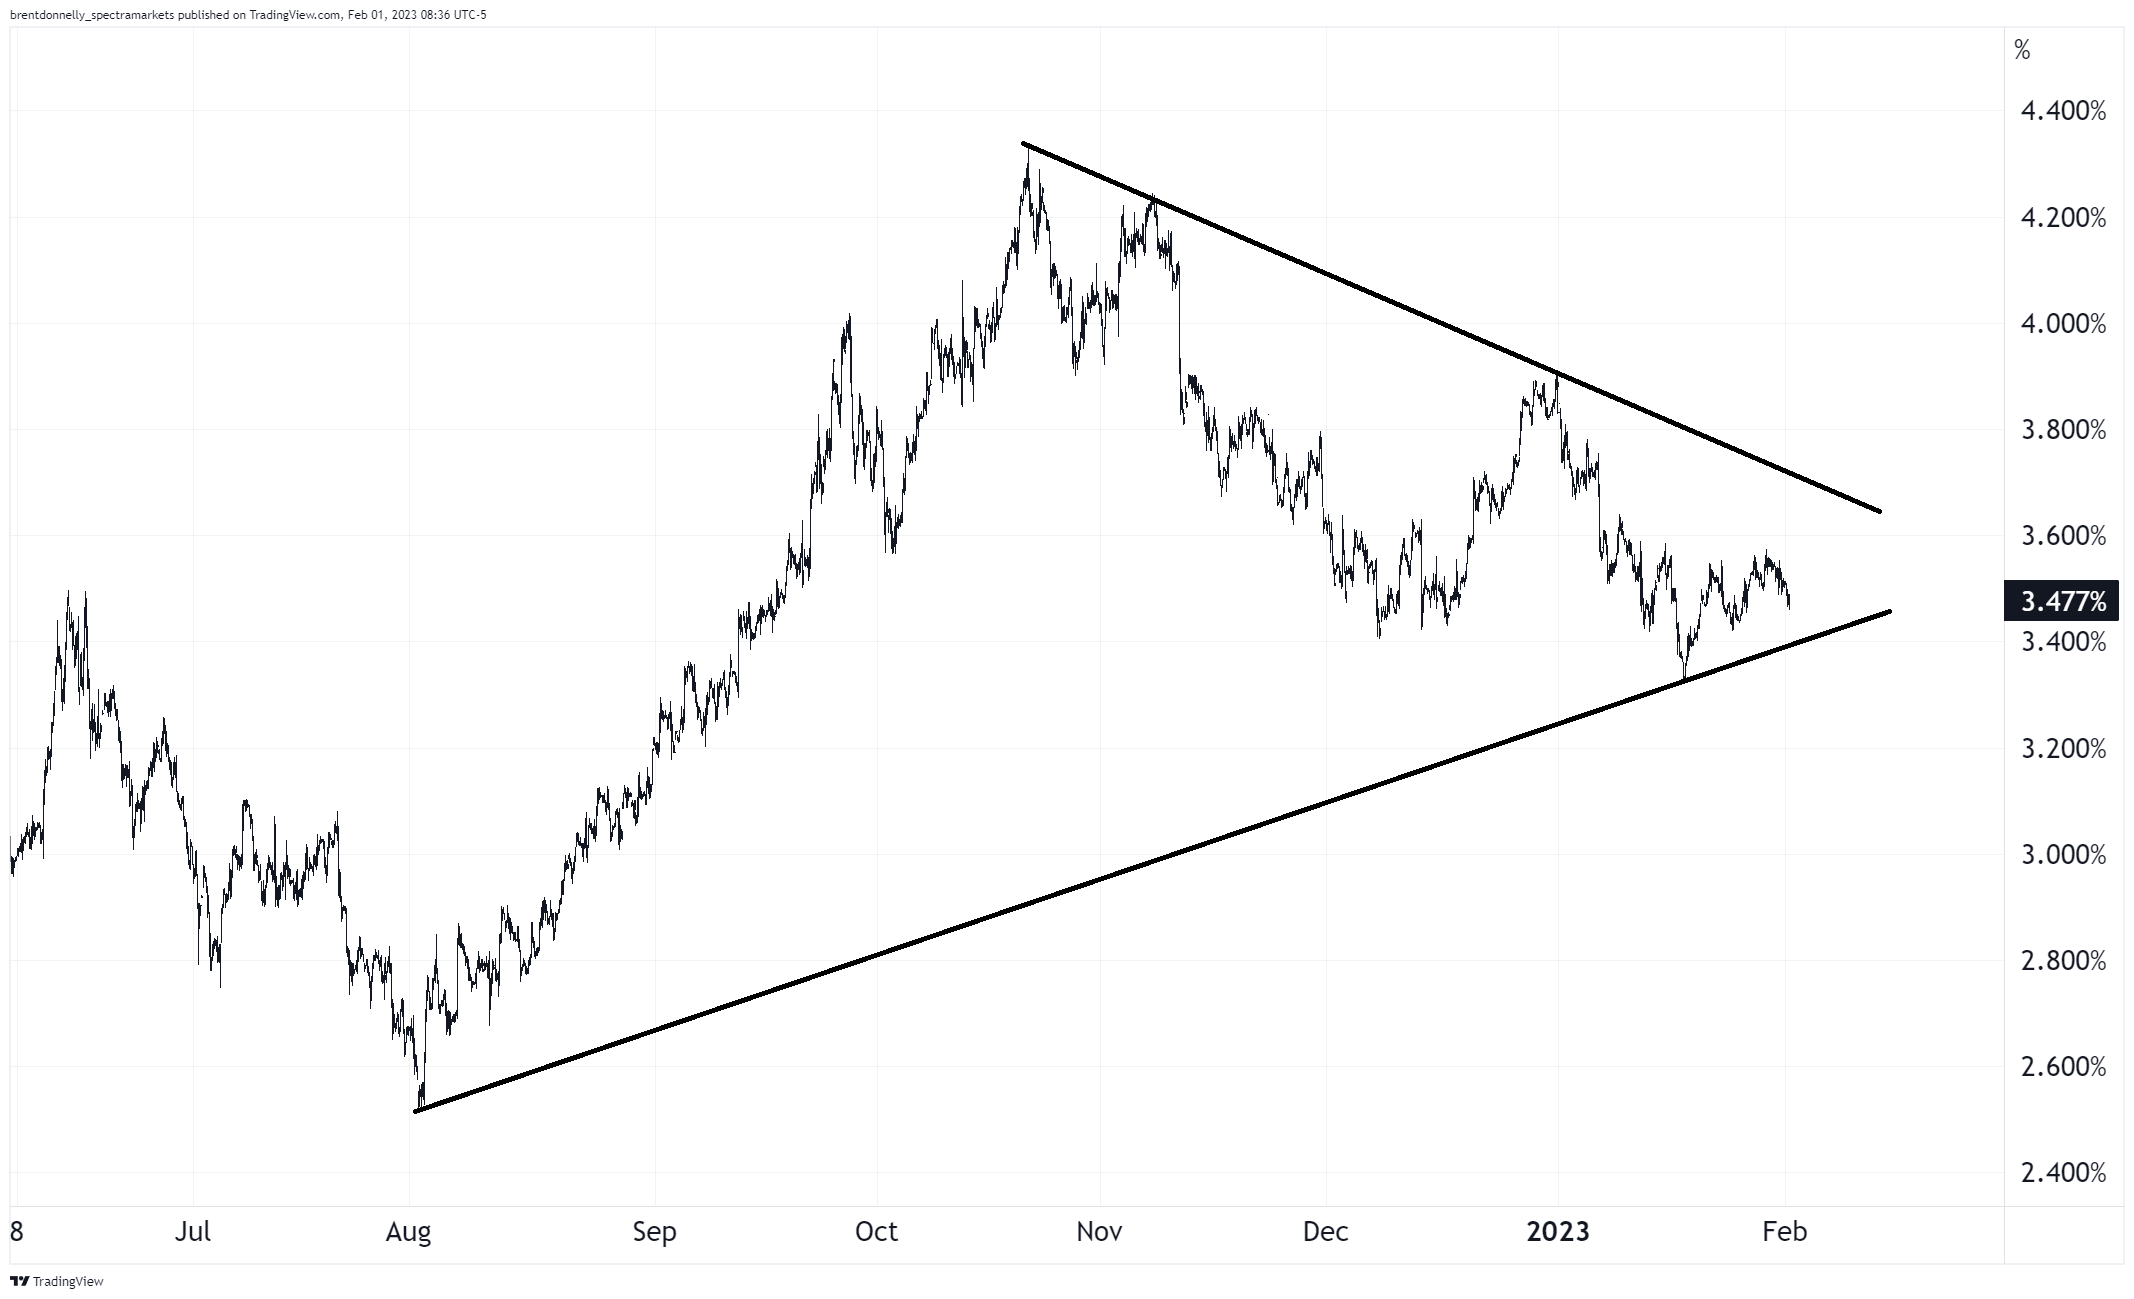
Meanwhile, US 10-year yields are in a massive triangular consolidation phase. It feels like we are close to the end of the immaculate disinflation narrative. Whether that means we go back to risk parity unwind like 2022, or we see a bullish growth phase where yields and equities rally together, I’m not sure yet. Watch this triangle in yields, and the charts I showed yesterday (HSI 25200/25600 + Bitcoin 25000) for overall direction from here. Yields up, HSI up, BTC up would be immaculate reflation, I suppose.
On housing, NAHB ticked up, and the excellent monthly rent report from apartmentlist.com is out for January. The rate of decline in rents has slowed while the MoM number for January was still negative. This spring’s housing market will be interesting to watch.
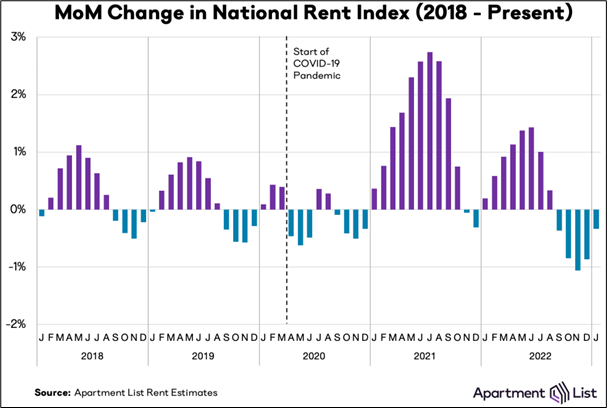
https://www.apartmentlist.com/research/national-rent-data
Last night’s NZ jobs data was one of the few weaker-than-expected labor market numbers I can remember in any G10 country in ages[1]. The moderation in the Kiwi labor market and lower wage pressure is probably encouraging enough to take 75bps off the table at the February 21 RBNZ meeting. NZDCHF lower still makes sense to me.
Finally, I don’t have a strong view on equities right now, but here’s something to keep in mind.
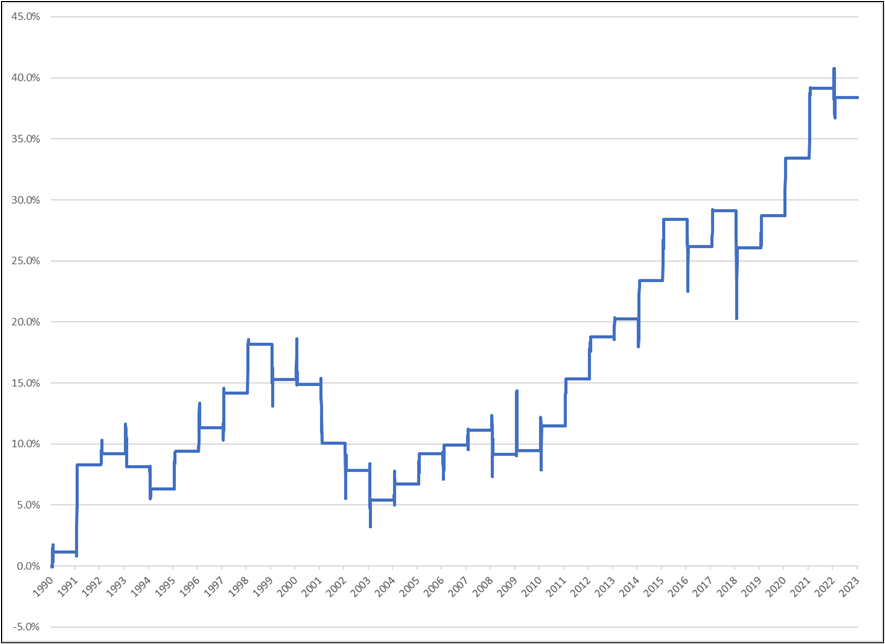
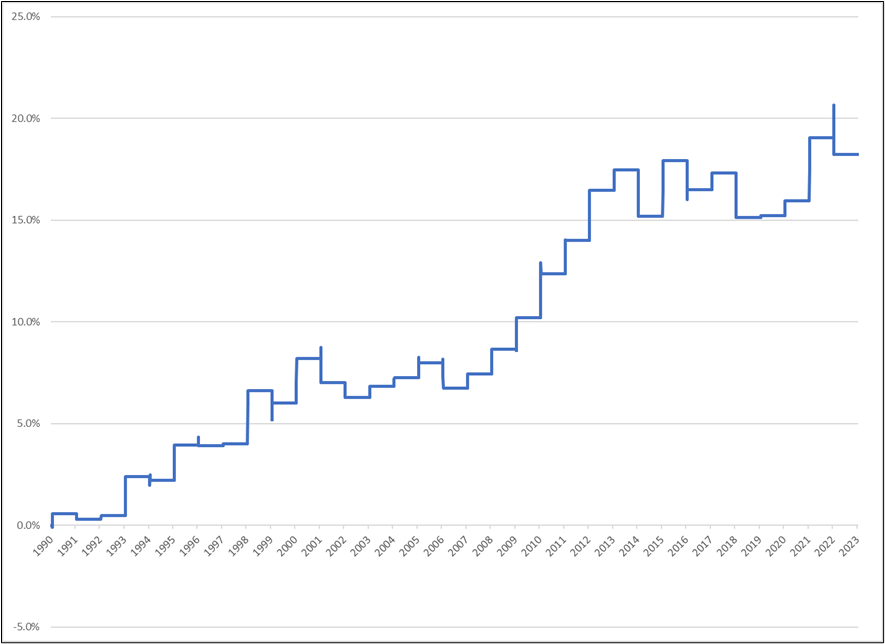
Cumulative P&L since 1990
Have a subterranean day.
—
[1] The Aussie jobs release on 18JAN23 was weak too.
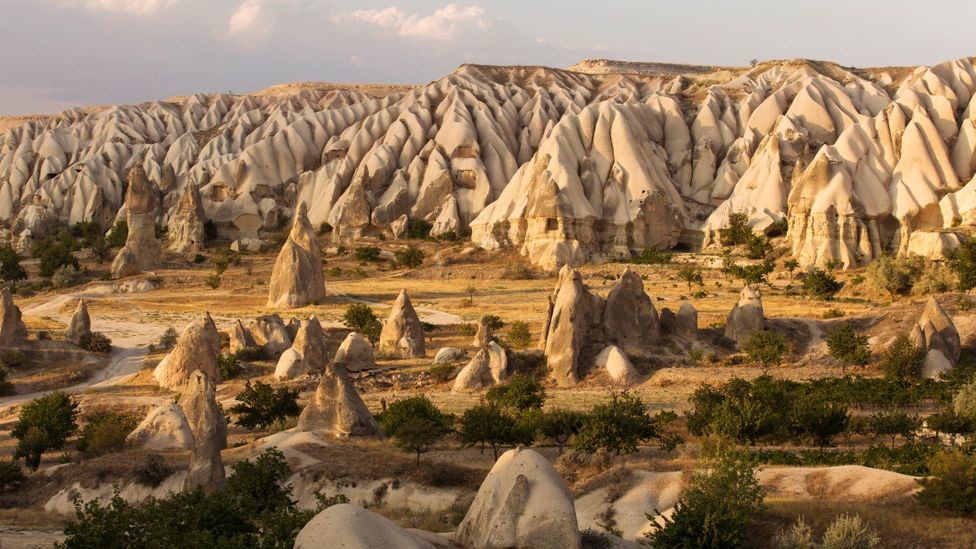
More than 85m beneath the famous fairy chimneys of Cappadocia lies a massive 18-story, subterranean city that was in near-constant use for thousands of years.
https://bigthink.com/strange-maps/derinkuyu-underground-city/
https://www.bbc.com/travel/article/20220810-derinkuyu-turkeys-underground-city-of-20000-people
Hat tip Ben Briody


This piece is mostly for people who are interested in backtesting

