Low Expectations

Subscriber-only

2024 forecasts for GDP and CPI of the major economies are all in the same ballpark and assume mean reversion.

BD
by Brent Donnelly

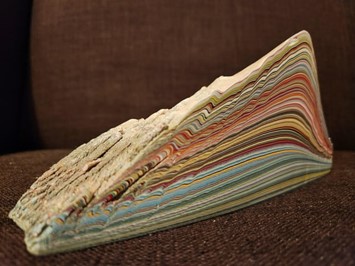
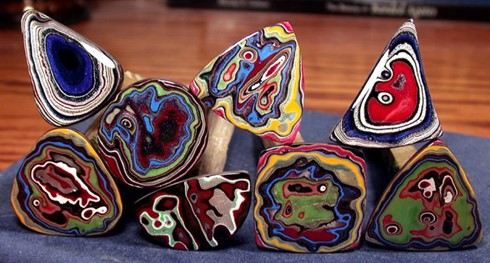
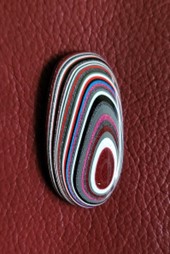
An 18-ounce chunk of Fordite


Fordite, also known as Detroit agate or Motor City agate is a lapidarist term for polished pieces of finely-layered paint masses from automobile factories.


Current Views


Friday 0.6380 AUD puts

for ~14 USD pips off 0.6420 spot

September 26, 2023


Low Expectations

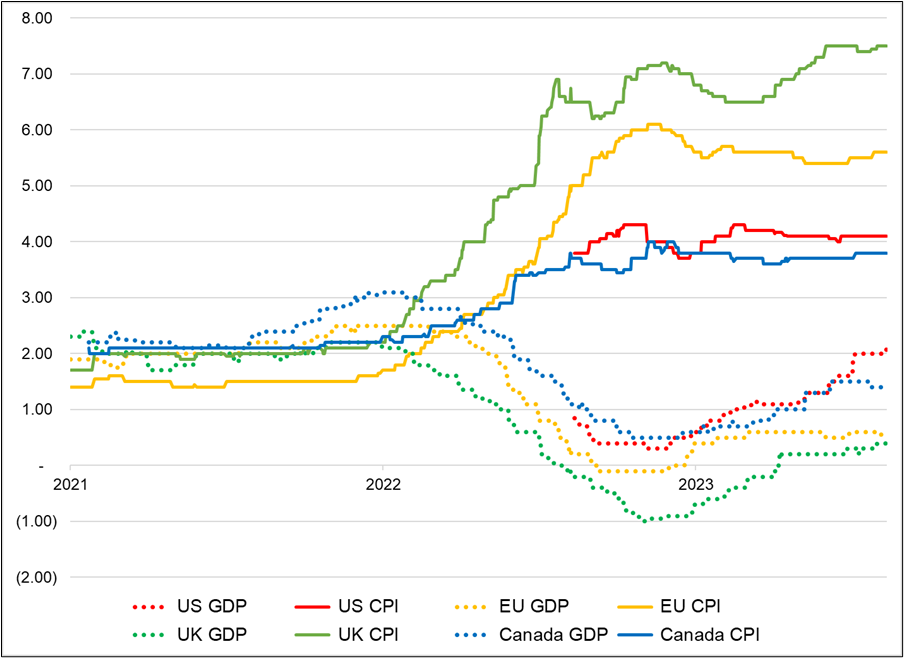
Torsten Sløk had a cool chart in his daily yesterday showing the 2023 forecasts for EU GDP and CPI. I thought it would be interesting to look at the evolution of those forecasts for more countries and 2023 and 2024. Here is the chart for 2023.

Economist 2023 GDP and CPI forecasts for four big economies
Economist 2024 GDP and CPI forecasts for four big economies
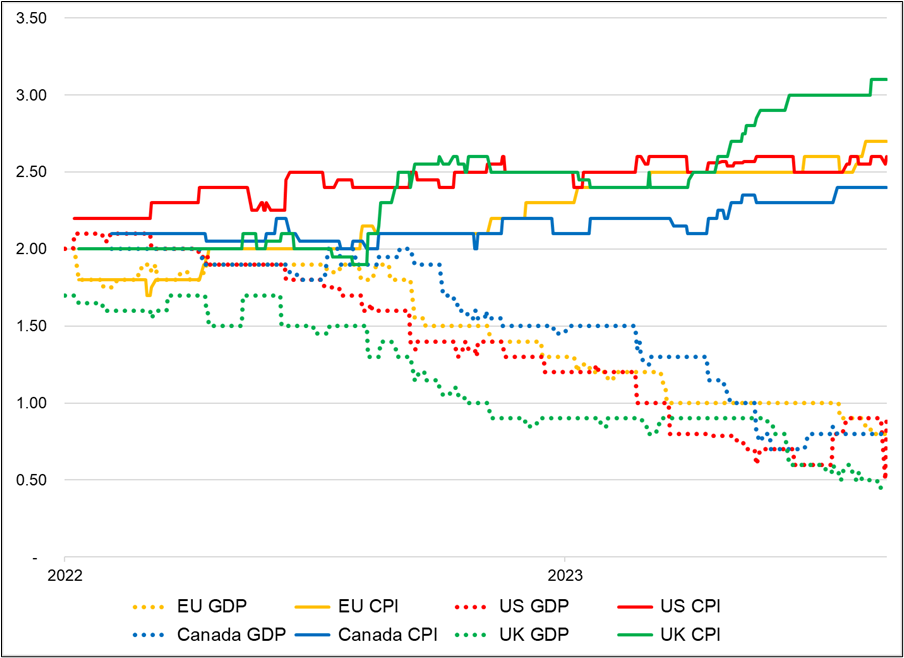
While there is a certain amount of extrapolation involved in the 2024 forecasts, it’s interesting how much convergence is expected and how economists expected all four economies to be similar in 2023 (wrong) and 2024 (maybe wrong?) The bar for the USA is once again set incredibly low and if we get through the government shutdown and student loan restart without a hiccup, there is plenty of room for a positive surprise from the US again in 2024. The Fed’s GDP forecast is 1.5% vs. a median private sector US GDP forecast of 0.9%.

Low expectations for 2024 and ongoing recession fear due to the always-scary inverted yield curve might create a bullish setup for stocks once the fall equinox seasonality expires October 9. Here is the performance of stocks from September 27 to December 31 in the years before an election back to 1991.

S&P 500 performance September 27 to December 31 at end of pre-election year
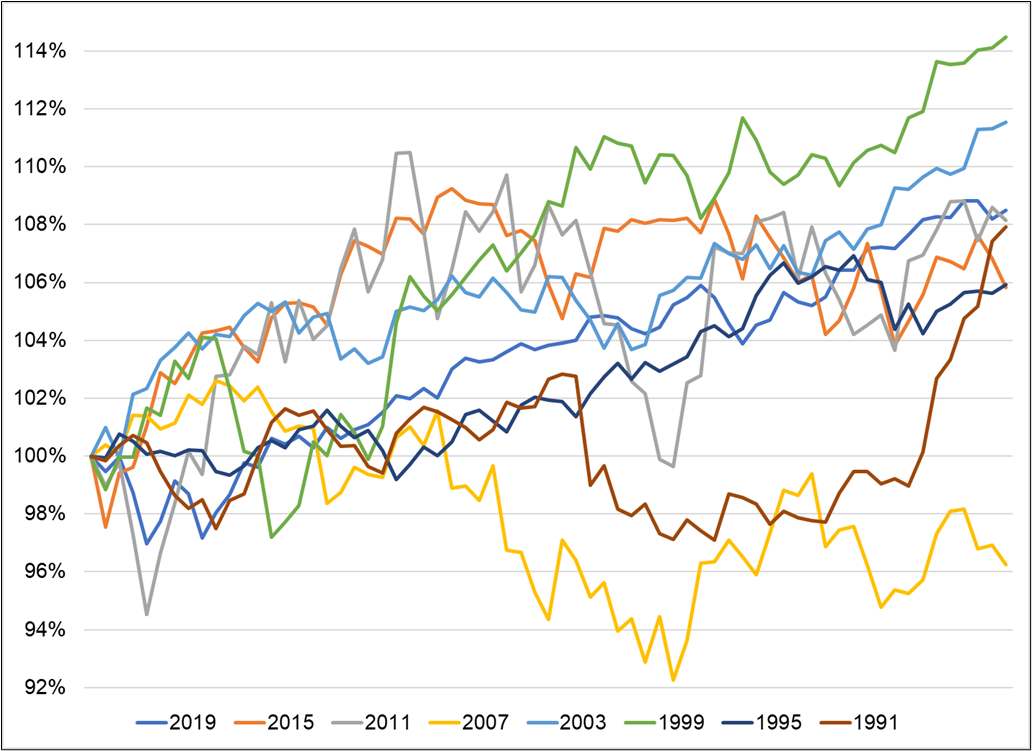
This predominantly bullish price action is consistent with bullish year end stock market seasonality through history. The closest analogs to the current year are 1995 and 2007, where the Fed was hiking aggressively. 2007 is the one down year out of the eight, while stocks rallied 6% in Q4 1995. For the short-term, the outlook remains bearish, but if you can get S&Ps around 4200/4250 on a sell off in the next two weeks, that’s probably the place to get long into yearend.


Final Thoughts

Could you please take 90 seconds to complete this quick survey about am/FX and how we can make it better?

https://www.eSurveysPro.com/Survey.aspx?id=e1cfd508-6160-43ed-8126-c17f09781633

Here’s a great little anecdote Kurt Vonnegut relayed at Joe Heller’s funeral:

Joseph Heller, an important and funny writer now dead, and I were at a party given by a billionaire on Shelter Island.

I said, “Joe, how does it make you feel to know that our host only yesterday may have made more money than your novel ‘Catch-22’ has earned in its entire history?”

And Joe said, “I’ve got something he can never have.” And I said, “What on earth could that be, Joe?” And Joe said, “… Enough.”

Have a colorful day.

good luck ⇅ be nimble


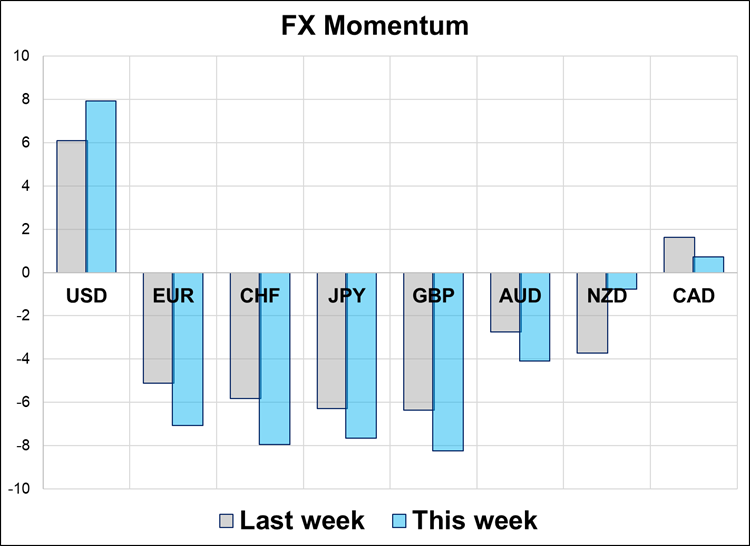
The Spectra FX Positioning and Momentum Report

Dollar remains King

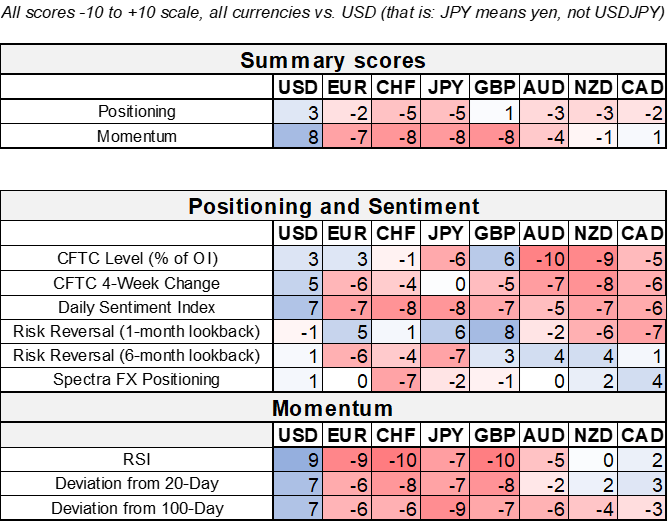
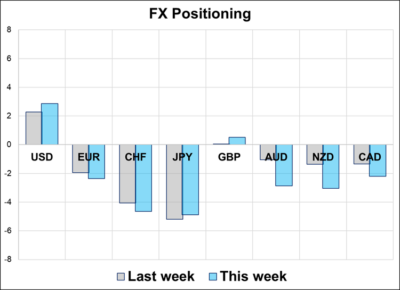
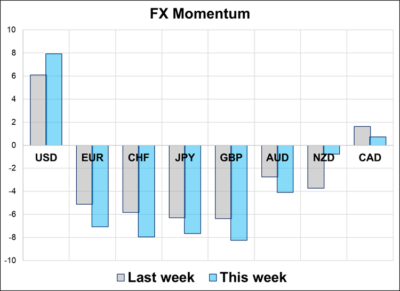
Hi. Welcome to this week’s report. The dollar remains King as dovish outcomes from the BoE, BOJ, and SNB have combined with a hawkish FOMC meeting to put the divergence trade back in force. The dollar has strong momentum but still only medium participation as investors love to be short dollars but are often hesitant to go all-in from the long side. Month end should feature more dollar buying.

Two Observations

1. CHF and JPY remain the largest positions vs. the dollar as momentum and carry remain in favor of USDCHF and USDJPY and the central bank meetings last week open more upside for the monetary policy divergence trade as the SNB looks to be done and the BOJ never got started. It’s amazing to see the increase in Japanese inflation and the non-response from the Japanese monetary policy even as the JPY is historically weak.

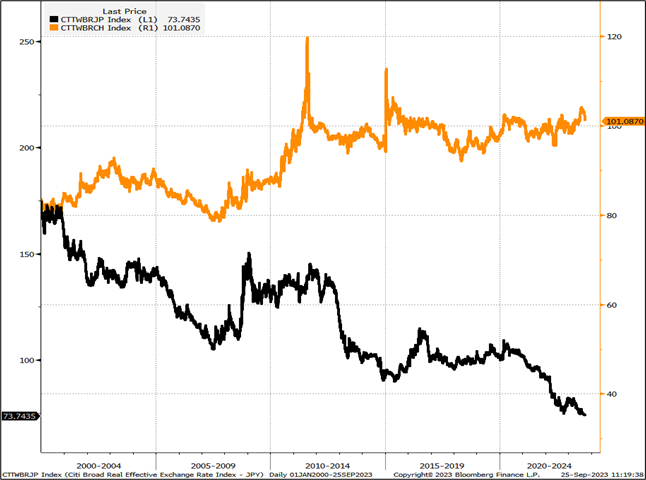
The divergence between CHF and JPY valuation is stark and has attracted some speculative interest in short CHFJPY as the SNB backs off its hawkish policy and the market continues to anticipate something from the BOJ at some point. The trade is also buttressed by the idea that the probability of MOF intervention in USDJPY increases exponentially as we near 150 in USDJPY.

CHF REER vs. JPY REER, 2000 to now

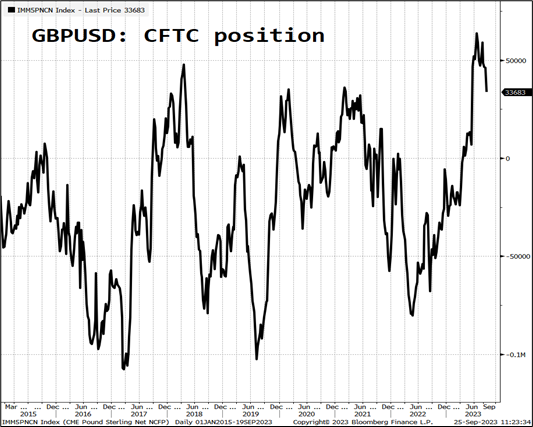
2. Whoever was responsible for the huge increase in CFTC GBP longs has been left holding unprofitable bags as the average entry point of 1.28 is now about 600 pips underwater. This is consistent with past bouts of gigantic GBP selling by the CFTC. The bearish signal described in this report a few months ago has played out and the long position remains elevated, even as it shrinks.

Fast money was aggressively short GBP through CPI and BoE last week but most of that position was squared up as specs were quick to TP on fears that too many had the same position. This opens up further risk for GBPUSD down to massive support at the 2023 lows near 1.19.

—

G10 FX Positioning and Momentum Scores


That’s this week’s report. Thank you for reading.


From Wikipedia: Fordite, also known as Detroit agate or Motor City agate, is a lapidarist term for polished pieces of finely-layered paint masses from automobile factories. The masses consist of automotive paint which has hardened sufficiently to be cut and polished. It was formed from the buildup of layers of enamel paint slag on tracks and skids on which cars were painted with acrylic lacquer, which have been baked numerous times. In recent times the material has been upcycled into jewelry.

https://rockngem.com/fordite/


Click here to subscribe to am/FX

More recent posts

Subscriber-only

Enough of this EUR

The window for a euro rally was open and now it’s closing

Rabbit Holes

CAD and Rabbit Hole #18

This piece is mostly for people who are interested in backtesting