Talking about Global R* versus secular R*, and why EUR might be a good short next year.
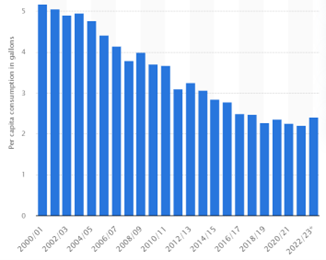
US per capita orange juice consumption fell 50% between 2000 and 2023

Talking about Global R* versus secular R*, and why EUR might be a good short next year.
US per capita orange juice consumption fell 50% between 2000 and 2023
Long 10DEC EURMXN
18.70/18.20 put spread
~50bps EUR
off 19.16 spot
November 30, 2023
As a follow up to yesterday’s piece about whether or not we return to very low inflation and low yields… Coincidentally, the Bank of England Underground blog published a piece supporting that notion today. The piece is short, and easy to read, and links to a longer research piece if you want to get into the weeds.
https://bankunderground.co.uk/2023/11/30/global-r/#more-13192
The main takeaway rhymes with yesterday’s am/FX: The forces driving yields and inflation lower over the last 43 years or so continue unabated. Here’s global R* back to 1900 (from the blog).
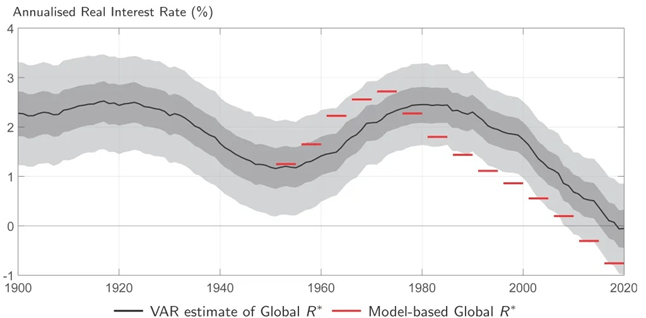
One of the more interesting parts of the writeup is the concept of global R* itself. Generally, I tend to think and read about R* in various individual countries, mostly the US, but the paper claims the following:
Within a standard macroeconomic framework, secular movements in real interest rates are determined by the factors that drive the supply and demand for capital. Over the long run, when capital can move freely across countries, there exists a single interest rate that clears the global capital market. This global trend real interest rate, Global R*, acts as an anchor for domestic interest rates in open economies, so that estimates of Global R* are important inputs to longer-term structural analysis, including the design of policy frameworks. So studying the factors that drive global wealth and capital accumulation is crucial for understanding interest-rate trends around the world.
This makes sense to me and is a good (less cynical) explanation for why central banks tend to move as a pack. Of course, this pack-like movement could be more about groupthink and regret minimization. If you copy what everyone else is doing, and you’re wrong, you can just say “whoops.” It’s the central bank equivalent of fund managers hugging the benchmark, even when they might believe doing so is not financially optimal.
They could be optimizing for the two kids in private school, the leased Defender, and the huge McMansion mortgage, not the advertised investment objectives.
It’s interesting that only one G10 central bank took a substantially different approach to the inflationary shock after the pandemic rebound, even though such a unique event would present an opportunity for more creativity and independent thinking… The BoJ was the only central bank that deviated from the herd and they deviated in the dovish direction when the “logical” deviation would have been more hawkish! Amazing.
There was a pretty good argument for hiking US rates (or at least stopping QE) in March 2021, for example, when the American Rescue Plan should have allowed a baton pass from monetary to fiscal policy. We have the benefit of hindsight now, but there were plenty of people howling about the insanity of low rates throughout 2021. So it’s not really hindsight, it was argued ex-ante.
To their credit, at least the RBNZ went earliest. The RBA waiting until May 2022 is widely seen as a failure.
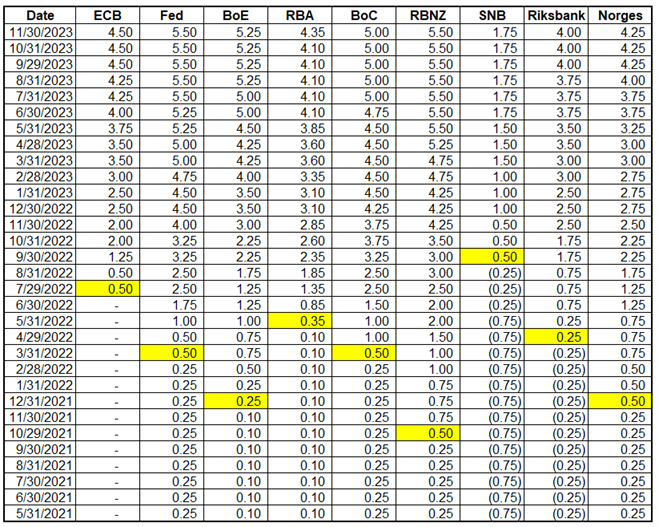
Anyway, post-GFC central bankers are politicians. They will cut at the first sign of danger and wait as long as possible to hike. The reward is fewer, shorter recessions and the costs are hard to measure but probably include greater financial instability and possibly even greater societal dislocation. If I was a central banker, I would probably do the same thing because my incentives would be the same. Unless your first name is Paul and your last name is Volcker, the path of least regret is never to be to go rogue / early hiking.
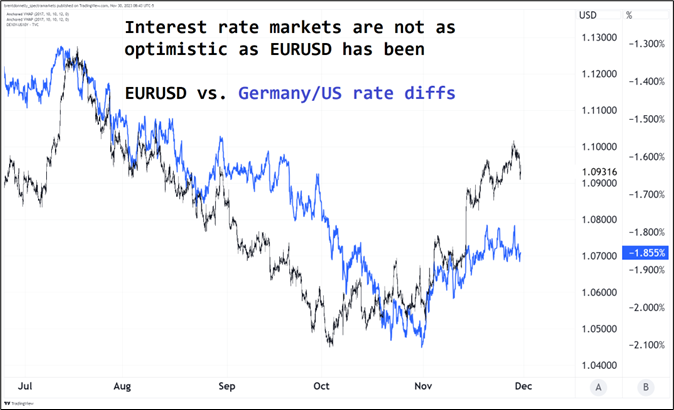
While the SELL DOLLARS! trade has worked pretty well post-CPI, I sense a new stream of consciousness entering the mind of the market: Sell euros for 2024. Contracting credit, persistently weak growth, a lack of good investable companies, and all that other stuff makes it really hard to own Europe. It’s one of those trades where people put it on and then three days later they ask: “Why the heck am I long Europe???” As Matt Gittins put it: “You can buy the EUR for a number of reasons, but a dynamic recovery is not one of them.”
And rate differentials reflect much less optimism than the currency. The anti-USD sentiment can persist but maybe not the pro-EUR sentiment.
Here is a sad and beautiful song to get you through December.
I first heard this song on headphones, walking out of Grand Central Terminal and into a mega snowstorm on December 16, 2020. As I trudged through the freezing, horizontally-travelling snowflakes on the way to work through the morning darkness, the weird surreal fear and sadness of 2020 got all mixed up inside my head with the certain hope that 2021 would be better. It almost made me cry.
But I only cry when I cut onions without safety goggles.
Have a sweet and not too acidic day.
In the 1980s and 1990s, orange juice was viewed as a super healthy, delicious morning staple. Now, a more general perception is that orange juice has the same sugar content as soda, it’s low in fiber, and thus increases excess calorie consumption, obesity, and diabetes.
I find it endlessly fascinating how nutrition science evolves and how financial interests often influence the public’s perception of the health benefits of particular foods. Foods are demonized or glorified in different decades depending on random influencers, corporate advertising, tell-all documentaries, smartly written books and other non-scientific information.
https://levelshealth.com/blog/how-and-why-the-food-pyramid-diet-recommendations-changed