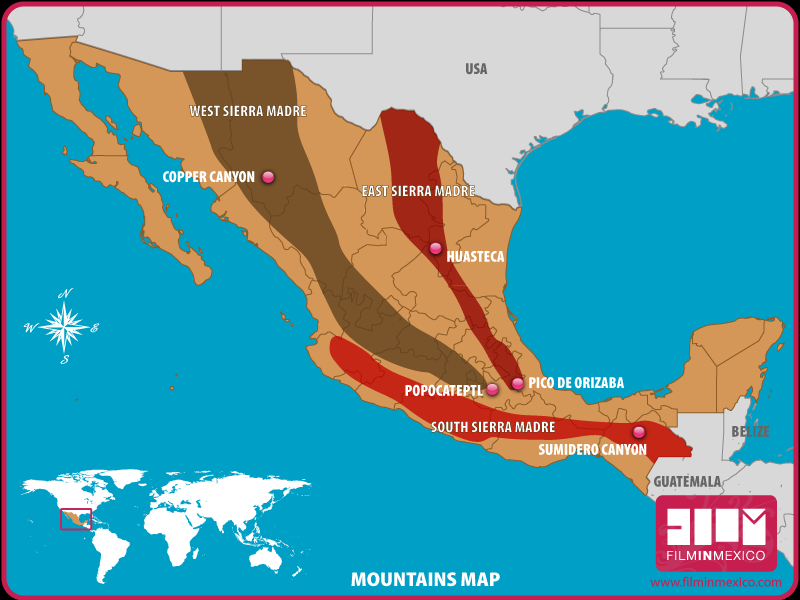
Sell rallies in stocks / expect a weak US CPI / look for an RBNZ cut.
Nighttime map of Mexico. Most of the activity is in the middle and huge swaths are undeveloped and mountainous.
Why is 80% of Mexico nearly empty?
Image from Tomas Pueyo

Sell rallies in stocks / expect a weak US CPI / look for an RBNZ cut.
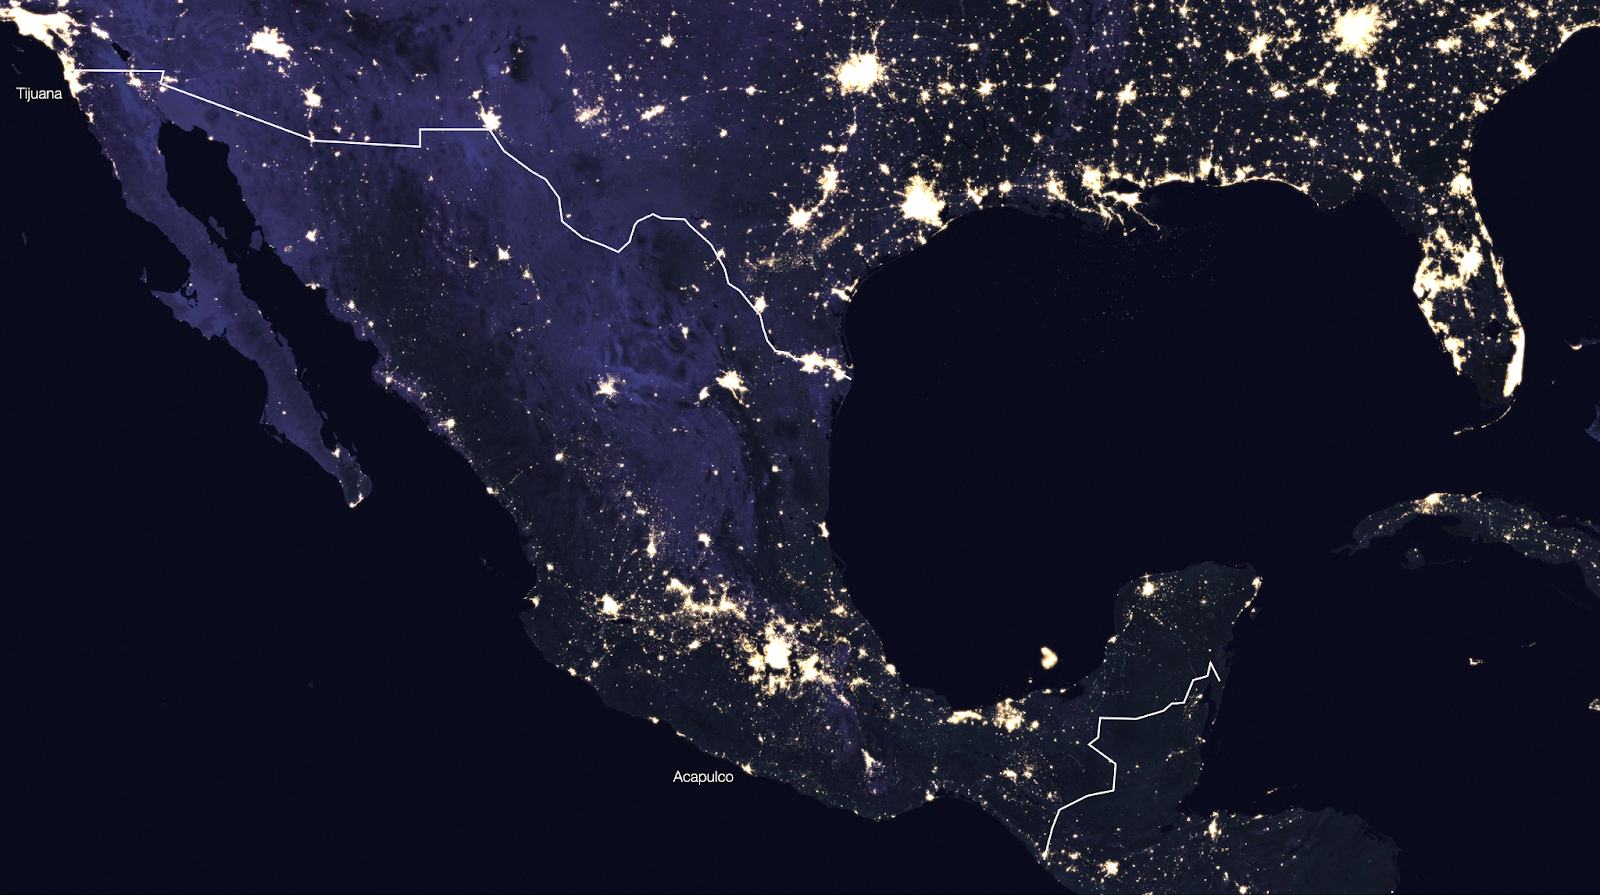
Nighttime map of Mexico. Most of the activity is in the middle and huge swaths are undeveloped and mountainous.
Why is 80% of Mexico nearly empty?
Image from Tomas Pueyo
Long AUDNZD @ 1.0954
Stop loss 1.0834
Take profit 1.1211
With Harris now holding a significant 53%-45% lead in the gambling odds and the recent vol shock sending a reminder that there is two-way risk in the stock market, I think this is a sell rallies market. Vol tends to cluster, and I doubt we simply get the one scare and then go back to all-time highs.
The rising and surprising odds of a Harris victory bring the MMT trade into question and raise the risk of fiscal drag concerns for 2025. The NASDAQ is getting up towards the 19,000 pivot (see chart) where I would expect strong hand sellers to emerge. As long as we are below 19k on a closing basis, I think this is a bearish setup.
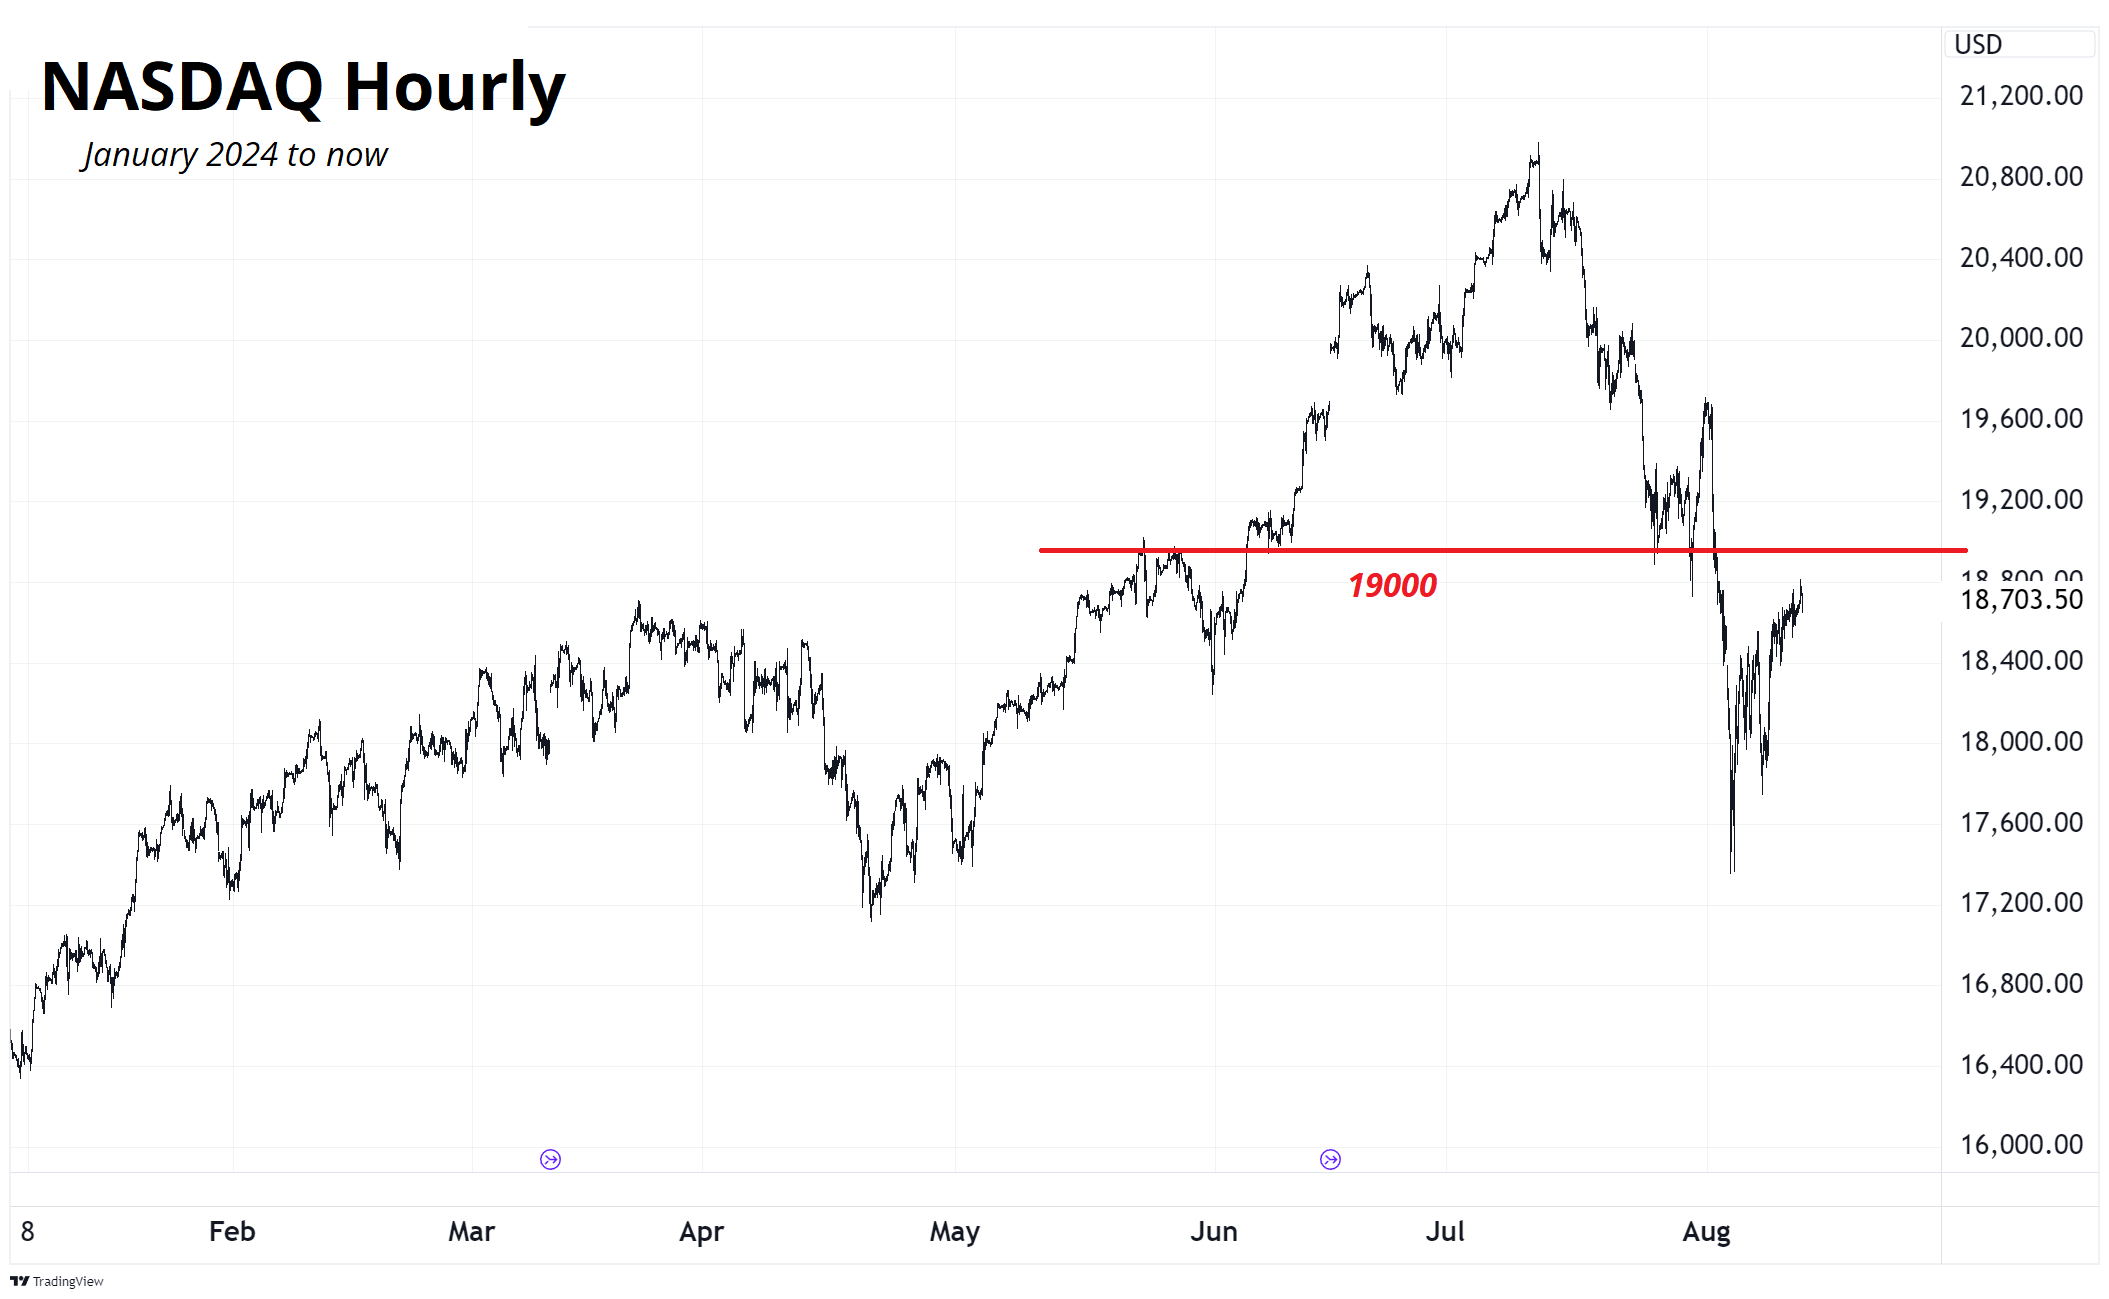
That red line marks the highs in late May, the support before launch to 20,800, and should be resistance again. It’s been a good pivot.
While CPI data has been by far the most important release throughout most of this cycle, we are transitioning away from inflation angst and into employment fear and therefore I don’t think PPI and CPI this week are nearly as important as they once were. Yes, they matter, but the market and the Fed are much more concerned about the employment picture now that inflation is back under control.
As discussed Friday, there is signal for CPI when PPI beats or misses on both headline and core. Here is the grid I published on the topic.
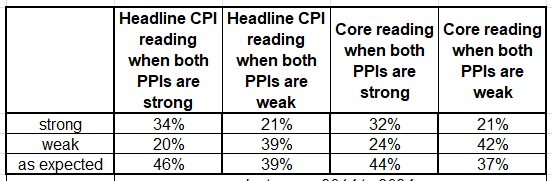
Today, both PPIs miss, which is a signal that suggests to me that the distribution for tomorrow’s CPI is something like a 20% chance of strong, 40% chance of weak, and 40% chance of as expected. Trade accordingly! As mentioned above, CPI is not as important as it used to be, and this PPI will obviously have the market leaning towards a weak CPI. So don’t be surprised if we get weak CPI, weak stocks by EOD tomorrow. For now, the PPI is good news at the margin.
There has been less interest in AUDNZD than I would have expected into RBNZ, and this has led to soggy price action as the event approaches.
I believe the RBNZ will cut tonight, and the outcome could look dovish as they tend to look at the turn of the cycle. That said, there is about a 60% chance of a cut priced in, so a cut is not a raging surprise. Still, with employment, inflation expectations, and net migration all supportive of a cut from very high levels of real rates, I like the trade.
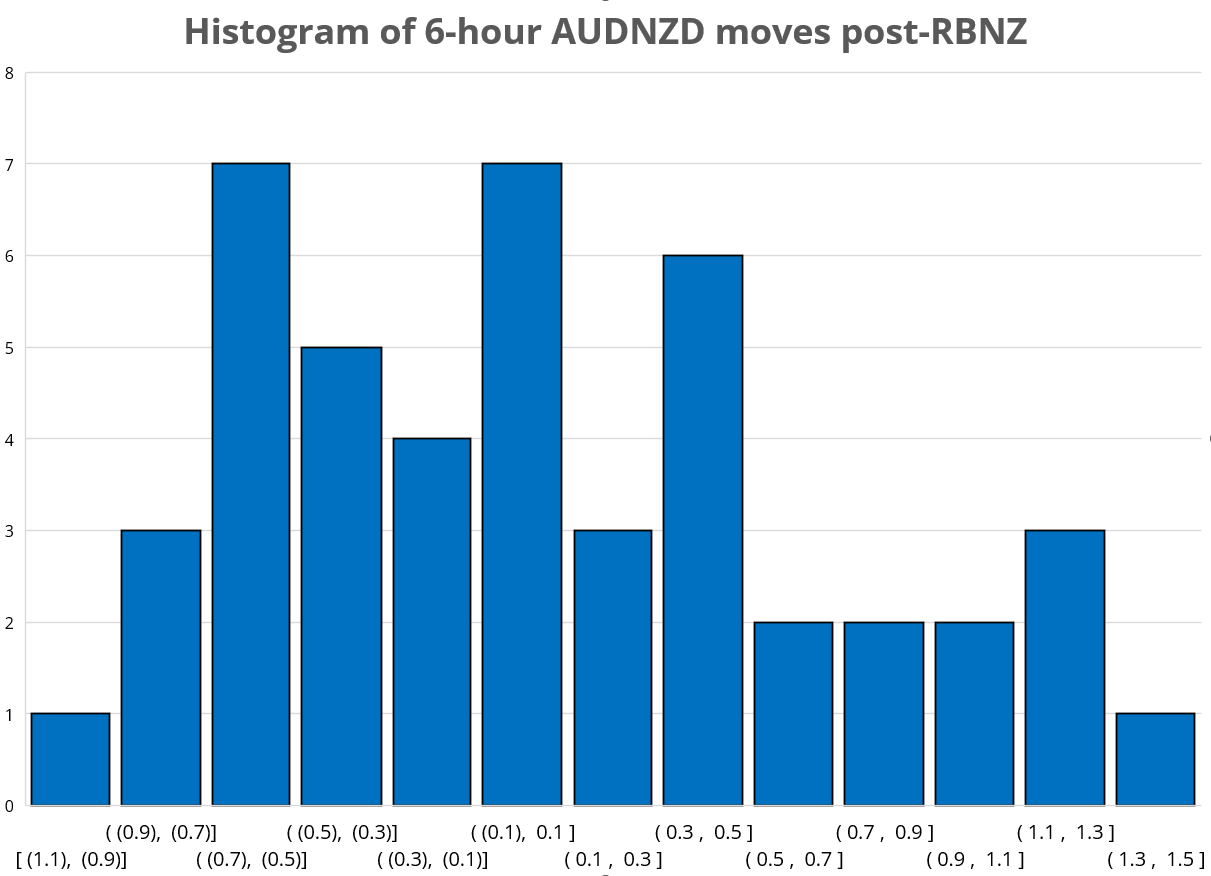
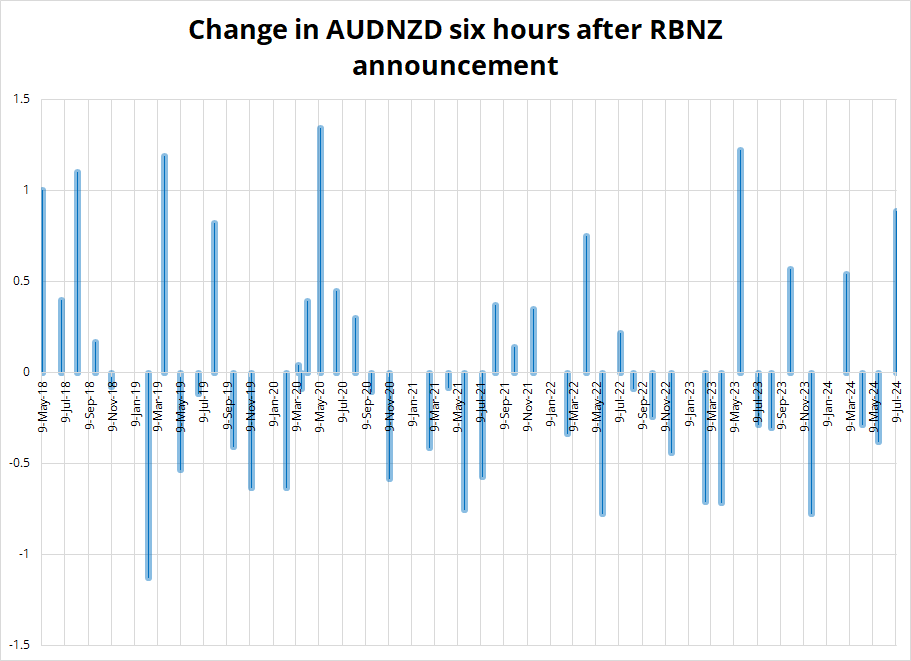
To get a sense of how much AUDNZD moves on RBNZ, take a look at this histogram and bar chart. The average absolute value of the 6-hour move is 0.52% and you can see the zero bucket, the -0.5% to -0.7% bucket, and the +0.3% to +0.5% bucket are the largest. I was surprised to see that if you isolate only RBNZ interest rate surprises, the volatility isn’t much different. There are plenty of times when the tone or language of the meeting is the driver, not the interest rate decision itself. These charts show data since the start of Governor Orr’s tenure in March 2018.
May you have Tyreek Hill levels of confidence today!
Clean
Hi. Welcome to this week’s report.
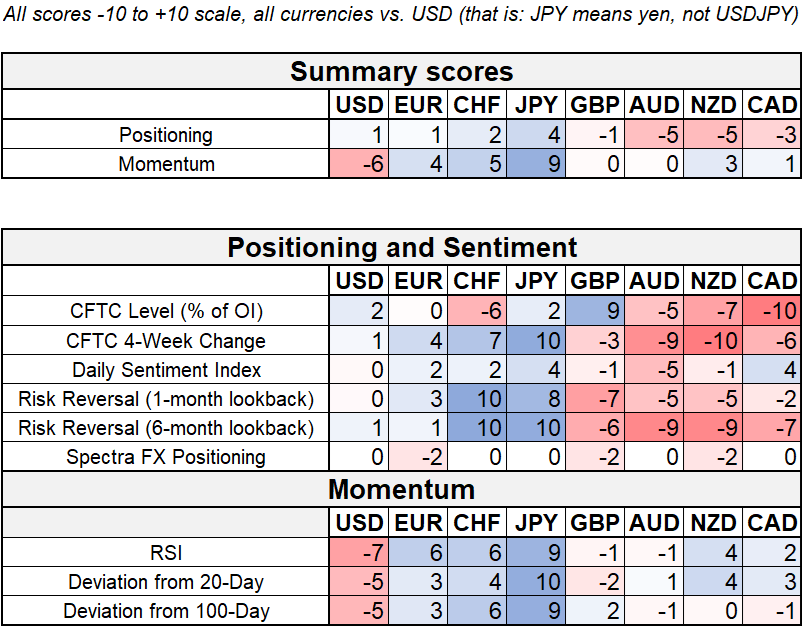
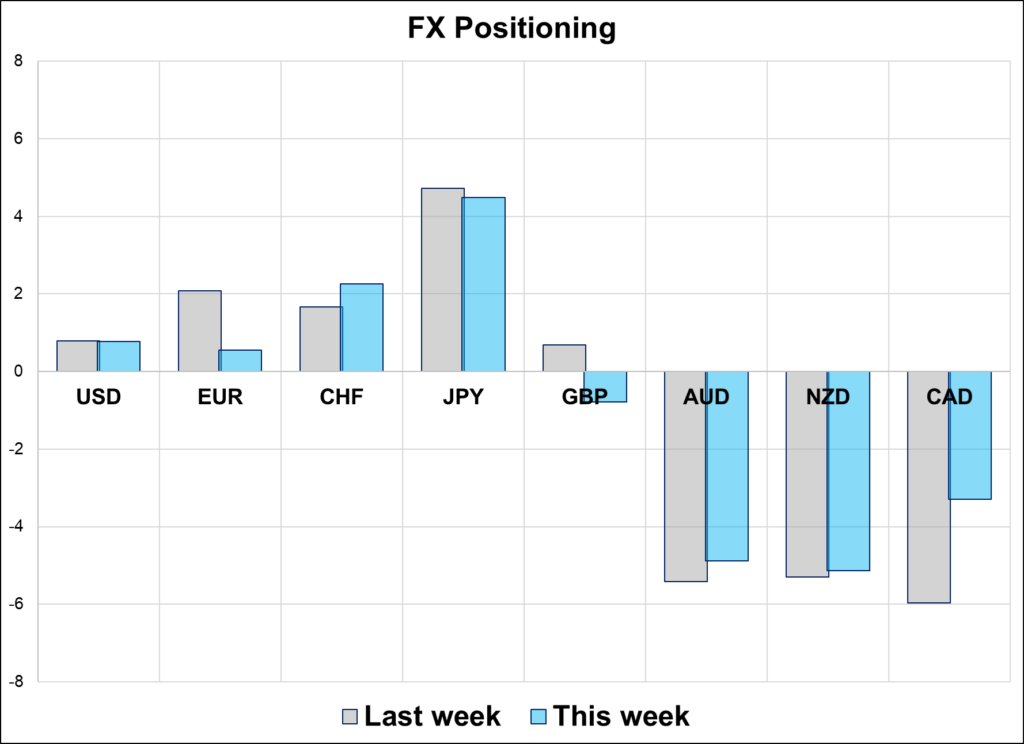
The JPY trade has unwound and while the CFTC is still tiny short, the size is minimal and is far less short than the average over the history of the series. The huge and nearly instant exit of massive JPY short positioning looks a lot like what happened after the carry blowup in mid-2007. In fact, it looks identical.
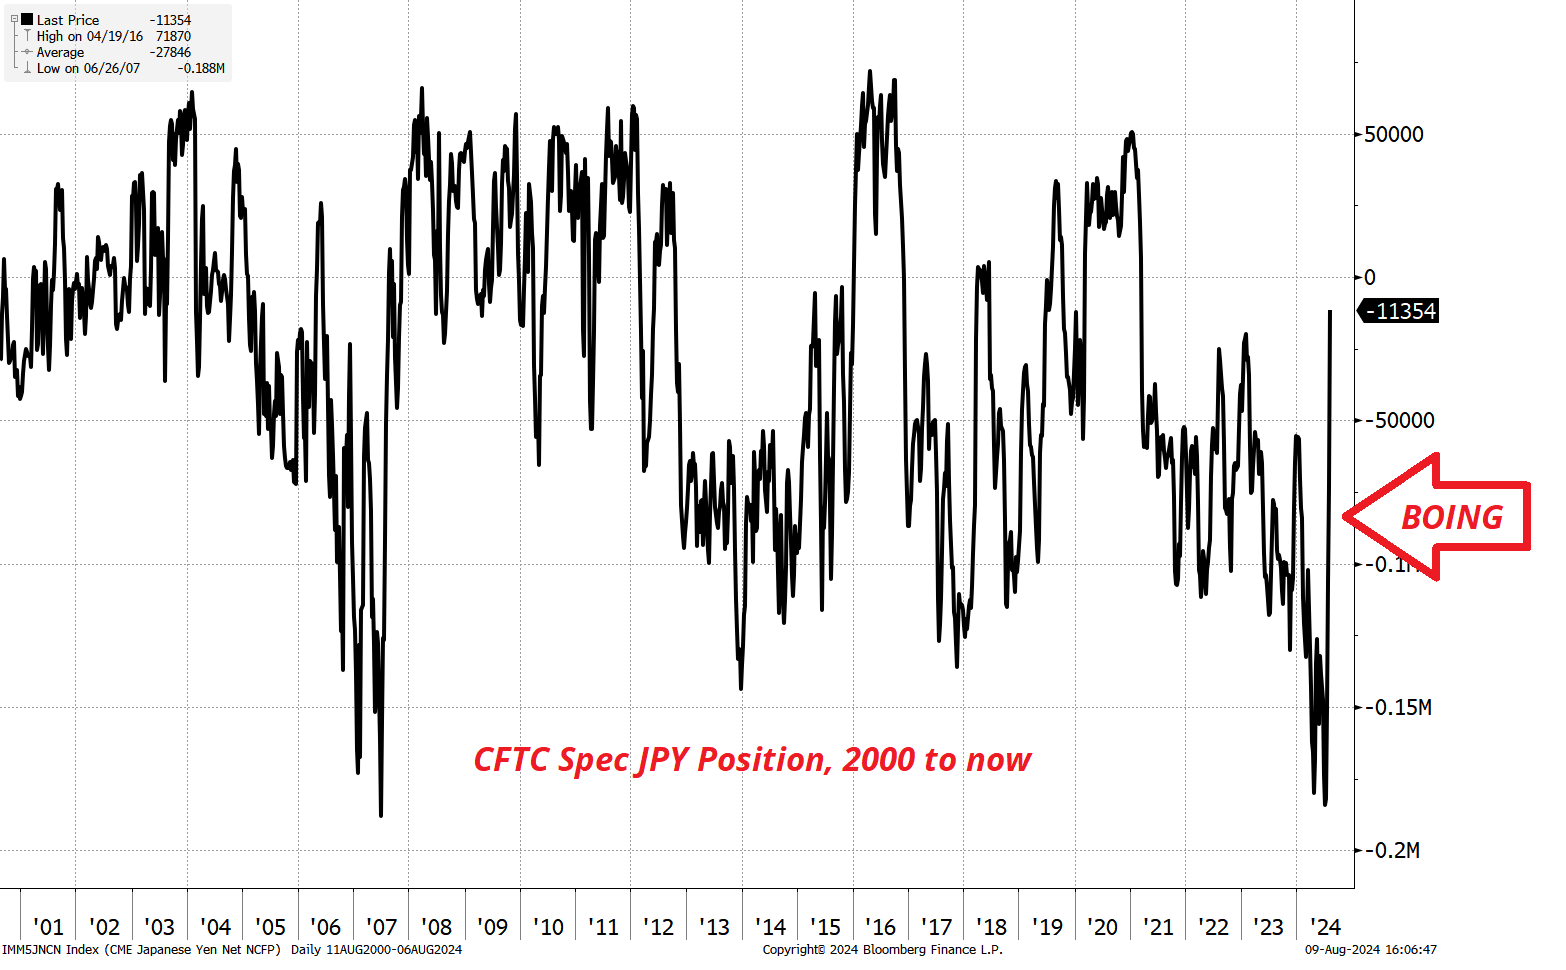
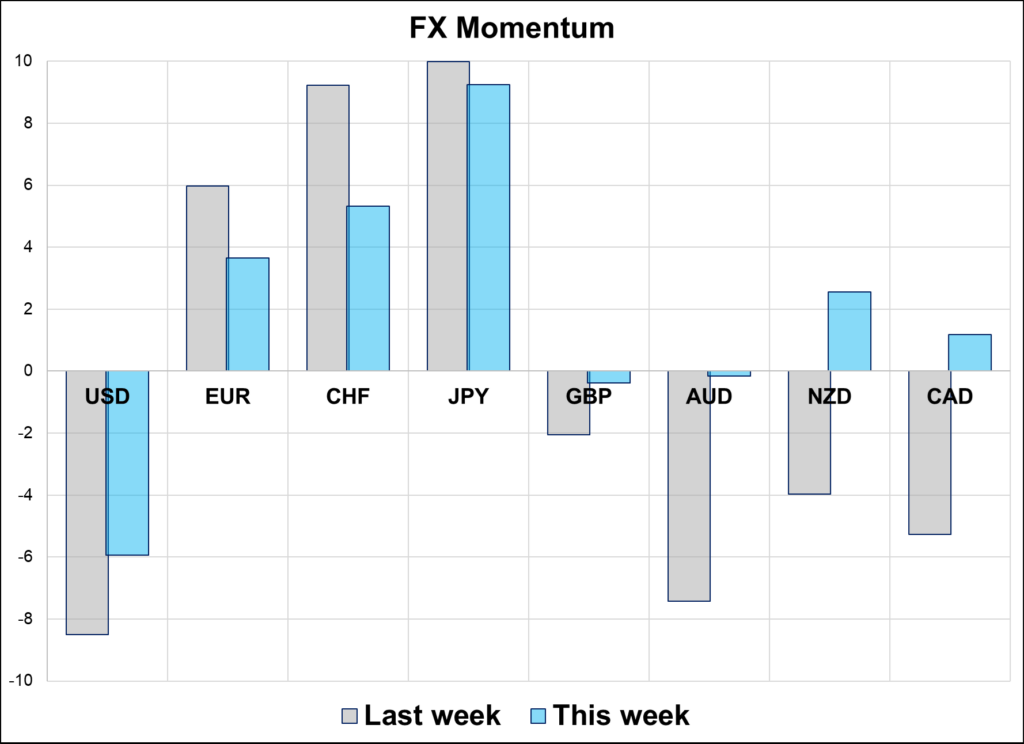
The positioning report now vs. most of 2024 has a completely different look as the short CHF and short JPY positions are gone post-volatility shock. I see no actionable signal in the data at this point, with everything a reflection of brutal unwinds as models and speculators run for the safety of the sidelines. There is plenty of room for specs to now get long JPY, or conversely, to get back into long carry, depending on how volatility and risk appetite evolve from here. Given my risk-negative view from here, my bet would be that specs now move to increase currently small long JPY positions over the next few weeks.
While FX positioning is not exactly flat, it’s close enough.


This piece is mostly for people who are interested in backtesting