February 22, 2023
Why is JPY vol so cheap?
I don’t really get why USDJPY vol is so cheap. As Phil Valori (of Spectra) pointed out this morning, you have FOMC Minutes today, then Ueda, and then Tokyo CPI on March 2nd. That release is particularly important because Tokyo CPI comes out before national CPI and that figure will include the new government energy subsidies and therefore headline should drop significantly. Recall what happened in every other country when the first whiff of disinflation appeared.
This February CPI situation is fiendishly complicated because the government energy subsidies begin, but energy companies are also planning huge price hikes at some point soon. To give you a sense of the situation, here is a bit more info.
Tokyo and Japan CPI back to 2010 with next month’s forecast in black/red
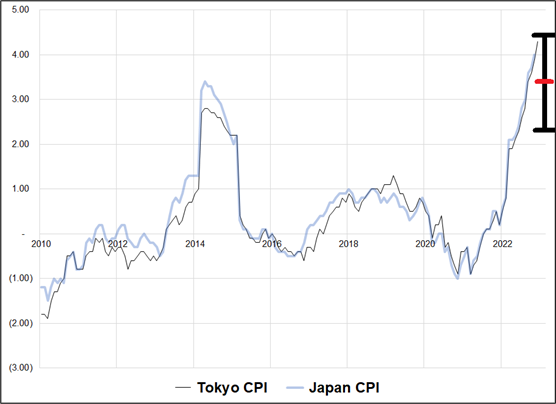
That black range bar that looks like it was drawn by a kid shows the range of estimates for Tokyo CPI (ex-food and energy) for February, along with the red line marking the median estimate. This is not to say that disinflation is locked in for Japan, because the subsidies might be wiped out by price hikes at some point. But that number is certainly going to be spicy with a 2%-wide range of estimates from five economists so far.
To be clear, that Tokyo CPI release is March 2. Tonight’s release is the national number for January and that release is close to meaningless because the Tokyo figure tells you everything you need to know about Japanese inflation and January CPI for Tokyo came out three weeks ago. As you can see in the chart, there are few meaningful divergences between the two series so the more timely series (Tokyo) is all that matters.
So you have FOMC Minutes today, Ueda speaks at 9:30 am Tokyo Friday coinciding with corporate month end on 24FEB. Then real money month end 28FEB and Tokyo CPI 02MAR. If you want to look further out, you also have payrolls on March 10 and the results from the shunto spring wage negotiations in mid-March. So you have all this and here’s 2-week USDJPY (below).
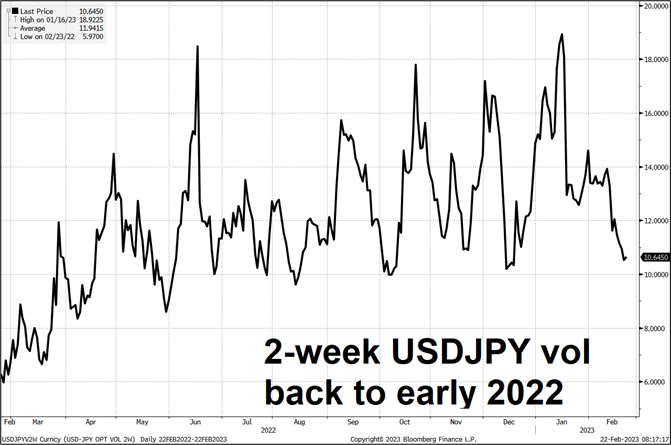
That looks totally wrong to me.
Two ways to play it. If you are an options trader, just buy gamma. 2-week or 1-month both make sense. If you must pick a direction, I would pick topside because:
- Seasonality is bullish until April 5
- US yields have broken 3.90%
- Ueda hasn’t sounded all that hawkish so far. This bullet point is the one I’m least confident on. There is definitely room for him to sound hawkish vs. pricing but all BOJ comments (including those from Tamura last night) have been on the boring, steady-as-she-goes side.
- Risk of disinflationary-looking data from Tokyo CPI on March 2.
- Carry and skew help you. 1-month 136.50 costs the same as 1-month 131.30. So the call that’s 200 points above costs the same as the put that’s 320 points below. More leverage, more fun if you’re right.
I am going to wait for Ueda because the problem with buying 1-month USD calls here is that if the new guvnah drops some kind of hawkish hammer, you own about 28 days of worthless topside. Better to wait for Ueda, buy spot if he’s dovish, then turn it into an option. Or, if you’re an options trader just own 2-week gamma now.
AUD and GBP
The last time there was a huge run up in AUDUSD and GBPUSD into the 11am NY/4pm LDN window, it was a two-day event. Therefore, the market will be keenly watching those two pairs for abnormal, mutant flows between now and the London close. Here is the price action yesterday:
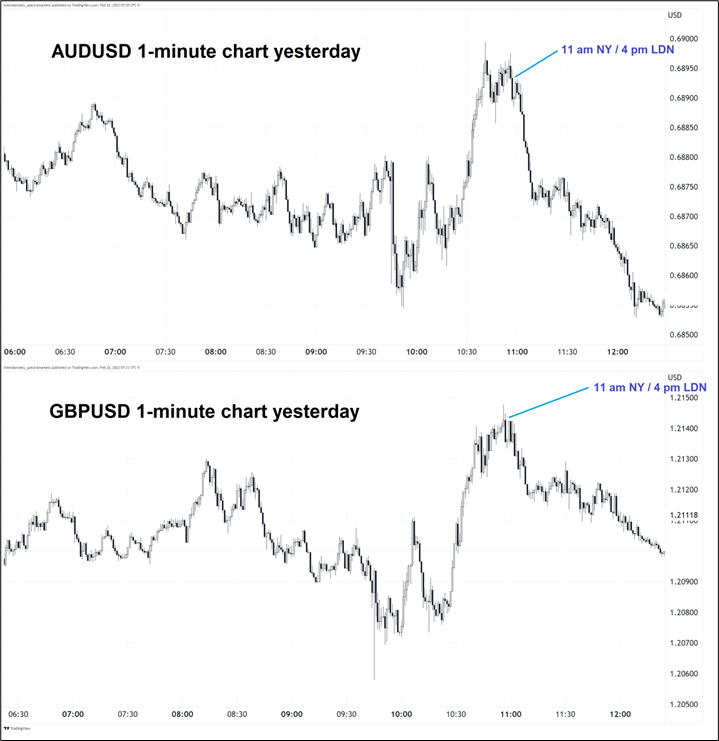
The flow started at 10am yesterday (one hour before the benchmark) and peaked at exactly 11 am. Something to watch as given USD was crushed across the board.
It feels to me that the bearish GBP theme is running out of steam after the labour market report and PMIs and risk is we dump to 0.8710/20 in EURGBP on a final wipeout of the UK recession, mortgage reset, dovish BoE narrative that has ruled for most of 2023. There is not really a bullish UK theme, per se, as strikes continue, mortgage resets still loom and so on (not to mention headlines about DUP and the Northern Ireland and Brexit are still a thing, seven years on)… So I am not putting a trade on here but just mentioning that the short GBP thesis feels stale.
Final Thoughts
This podcast is much, much more interesting than it sounds: “Will Ozempic solve obesity in America?” The US health care crisis, horrible US food, perverse incentives, toxic sugar, personal responsibility, willpower, genetics and more.
And this story is worth a read: FT: Joe Biden’s planned US building boom imperiled by labour shortage. I have written several notes about how US construction employment usually drops precipitously about six to twelve months after the NAHB Housing Index peaks. This is because construction projects take 6-12 months to complete and once a project is completed, the workers are unemployed and cannot find jobs because housing has hit a wall. In this cycle, there are many weird things going on and the delayed impact of slow-rolling infrastructure plans announced in 2021 could be another brick in the wall as we head to an unemployment rate below 3%.
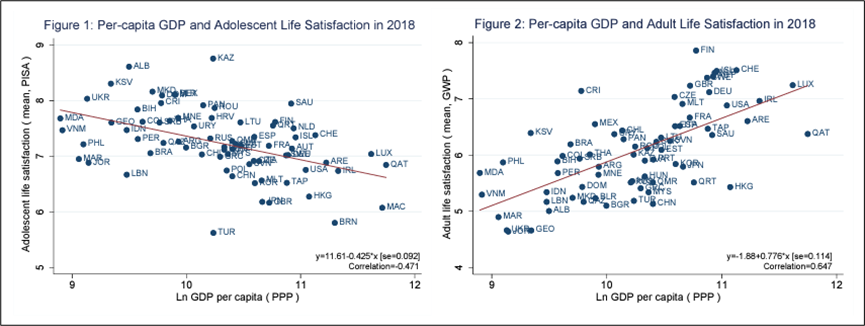
Finally, this paper is depressing but possibly important. The paradox of wealthy nations’ low adolescent life satisfaction.
“Our analysis suggests that this apparent paradox can largely be attributed to higher learning intensity in higher-income countries.”
Too much homework is pointless torment? Or perhaps the study fails to consider a hidden variable: the role of higher smartphone adoption in rich nations. Or both.
Have a cloistered day.
good luck ⇅ be nimble