There is no emergency and therefore 25bps is likely the signal at Jackson Hole this week and the action taken at 2051 Constitution Avenue on September 18.
Left side is mountains

There is no emergency and therefore 25bps is likely the signal at Jackson Hole this week and the action taken at 2051 Constitution Avenue on September 18.
Left side is mountains
Short NZDJPY @ 88.55
Stop loss 90.26
Take profit 86.01
Long AUDNZD @ 1.0954
Stop loss was 1.0834
now 1.0923
Take profit 1.1111
Going into his first Jackson Hole confab in 2018, Chairman Powell was still in rate hike mode and was months away from his famous “We are a long way from neutral” communication error. Claudia Sahm pointed out this potentially-relevant portion of his speech.
Finally, the literature on structural uncertainty suggests some broader insights. This literature started with the work of William Brainard and the well-known Brainard principle, which recommends that when you are uncertain about the effects of your actions, you should move conservatively. In other words, when unsure of the potency of a medicine, start with a somewhat smaller dose. As Brainard made clear, this is not a universal truth, and recent research highlights two particularly important cases in which doing too little comes with higher costs than doing too much. The first case is when attempting to avoid severely adverse events such as a financial crisis or an extended period with interest rates at the effective lower bound.
In such situations, the famous words “We will do whatever it takes” will likely be more effective than “We will take cautious steps toward doing whatever it takes.” The second case is when inflation expectations threaten to become unanchored. If expectations were to begin to drift, the reality or expectation of a weak initial response could exacerbate the problem. I am confident that the FOMC would resolutely “do whatever it takes” should inflation expectations drift materially up or down or should crisis again threaten.
Looking at his two conditions for large doses of monetary medicine, neither apply right now. There is no crisis and there is no issue with inflation expectations. Therefore, based on Powell’s 2018 logic at least, 25 bps would be the logical signal at Jackson Hole and policy change in September.
Honestly, I am surprised there is even a 20% chance of 50 priced in at this point given last week’s economic data and the clear gradualist message from the Fed, but maybe it’s simply the low-but-not-zero odds of a disastrous NFP on September 6th that has kept hopes for 50 beeps alive. Feels like a zero to me at this point, but it’s always hard to take the other side of a 4:1 bet, even when it feels like it’s positive EV.
The dollar has entered a meaningful down move here, kind of out of nowhere, and while I’m tempted to pin the blame on the Dems returning from the dead, it is hard to really make the connection between markets and US election odds right now. And sure, the Fed is about to cut, but they’re about to cut less than markets thought they were gonna cut a week ago and the USD is lower in that time. This article about strong Asian currencies overnight is a representative hodge podge of unsatisfying explanations.
A simple explanation that makes sense is: Rate differentials blew out after NFP and have never returned to levels they traded before that. The initial reaction on the interest rate blowout involved some reflexive USD buying due to risk aversion, but that never made a ton of sense and now we are pricing FX appropriately vs. interest rate differentials.
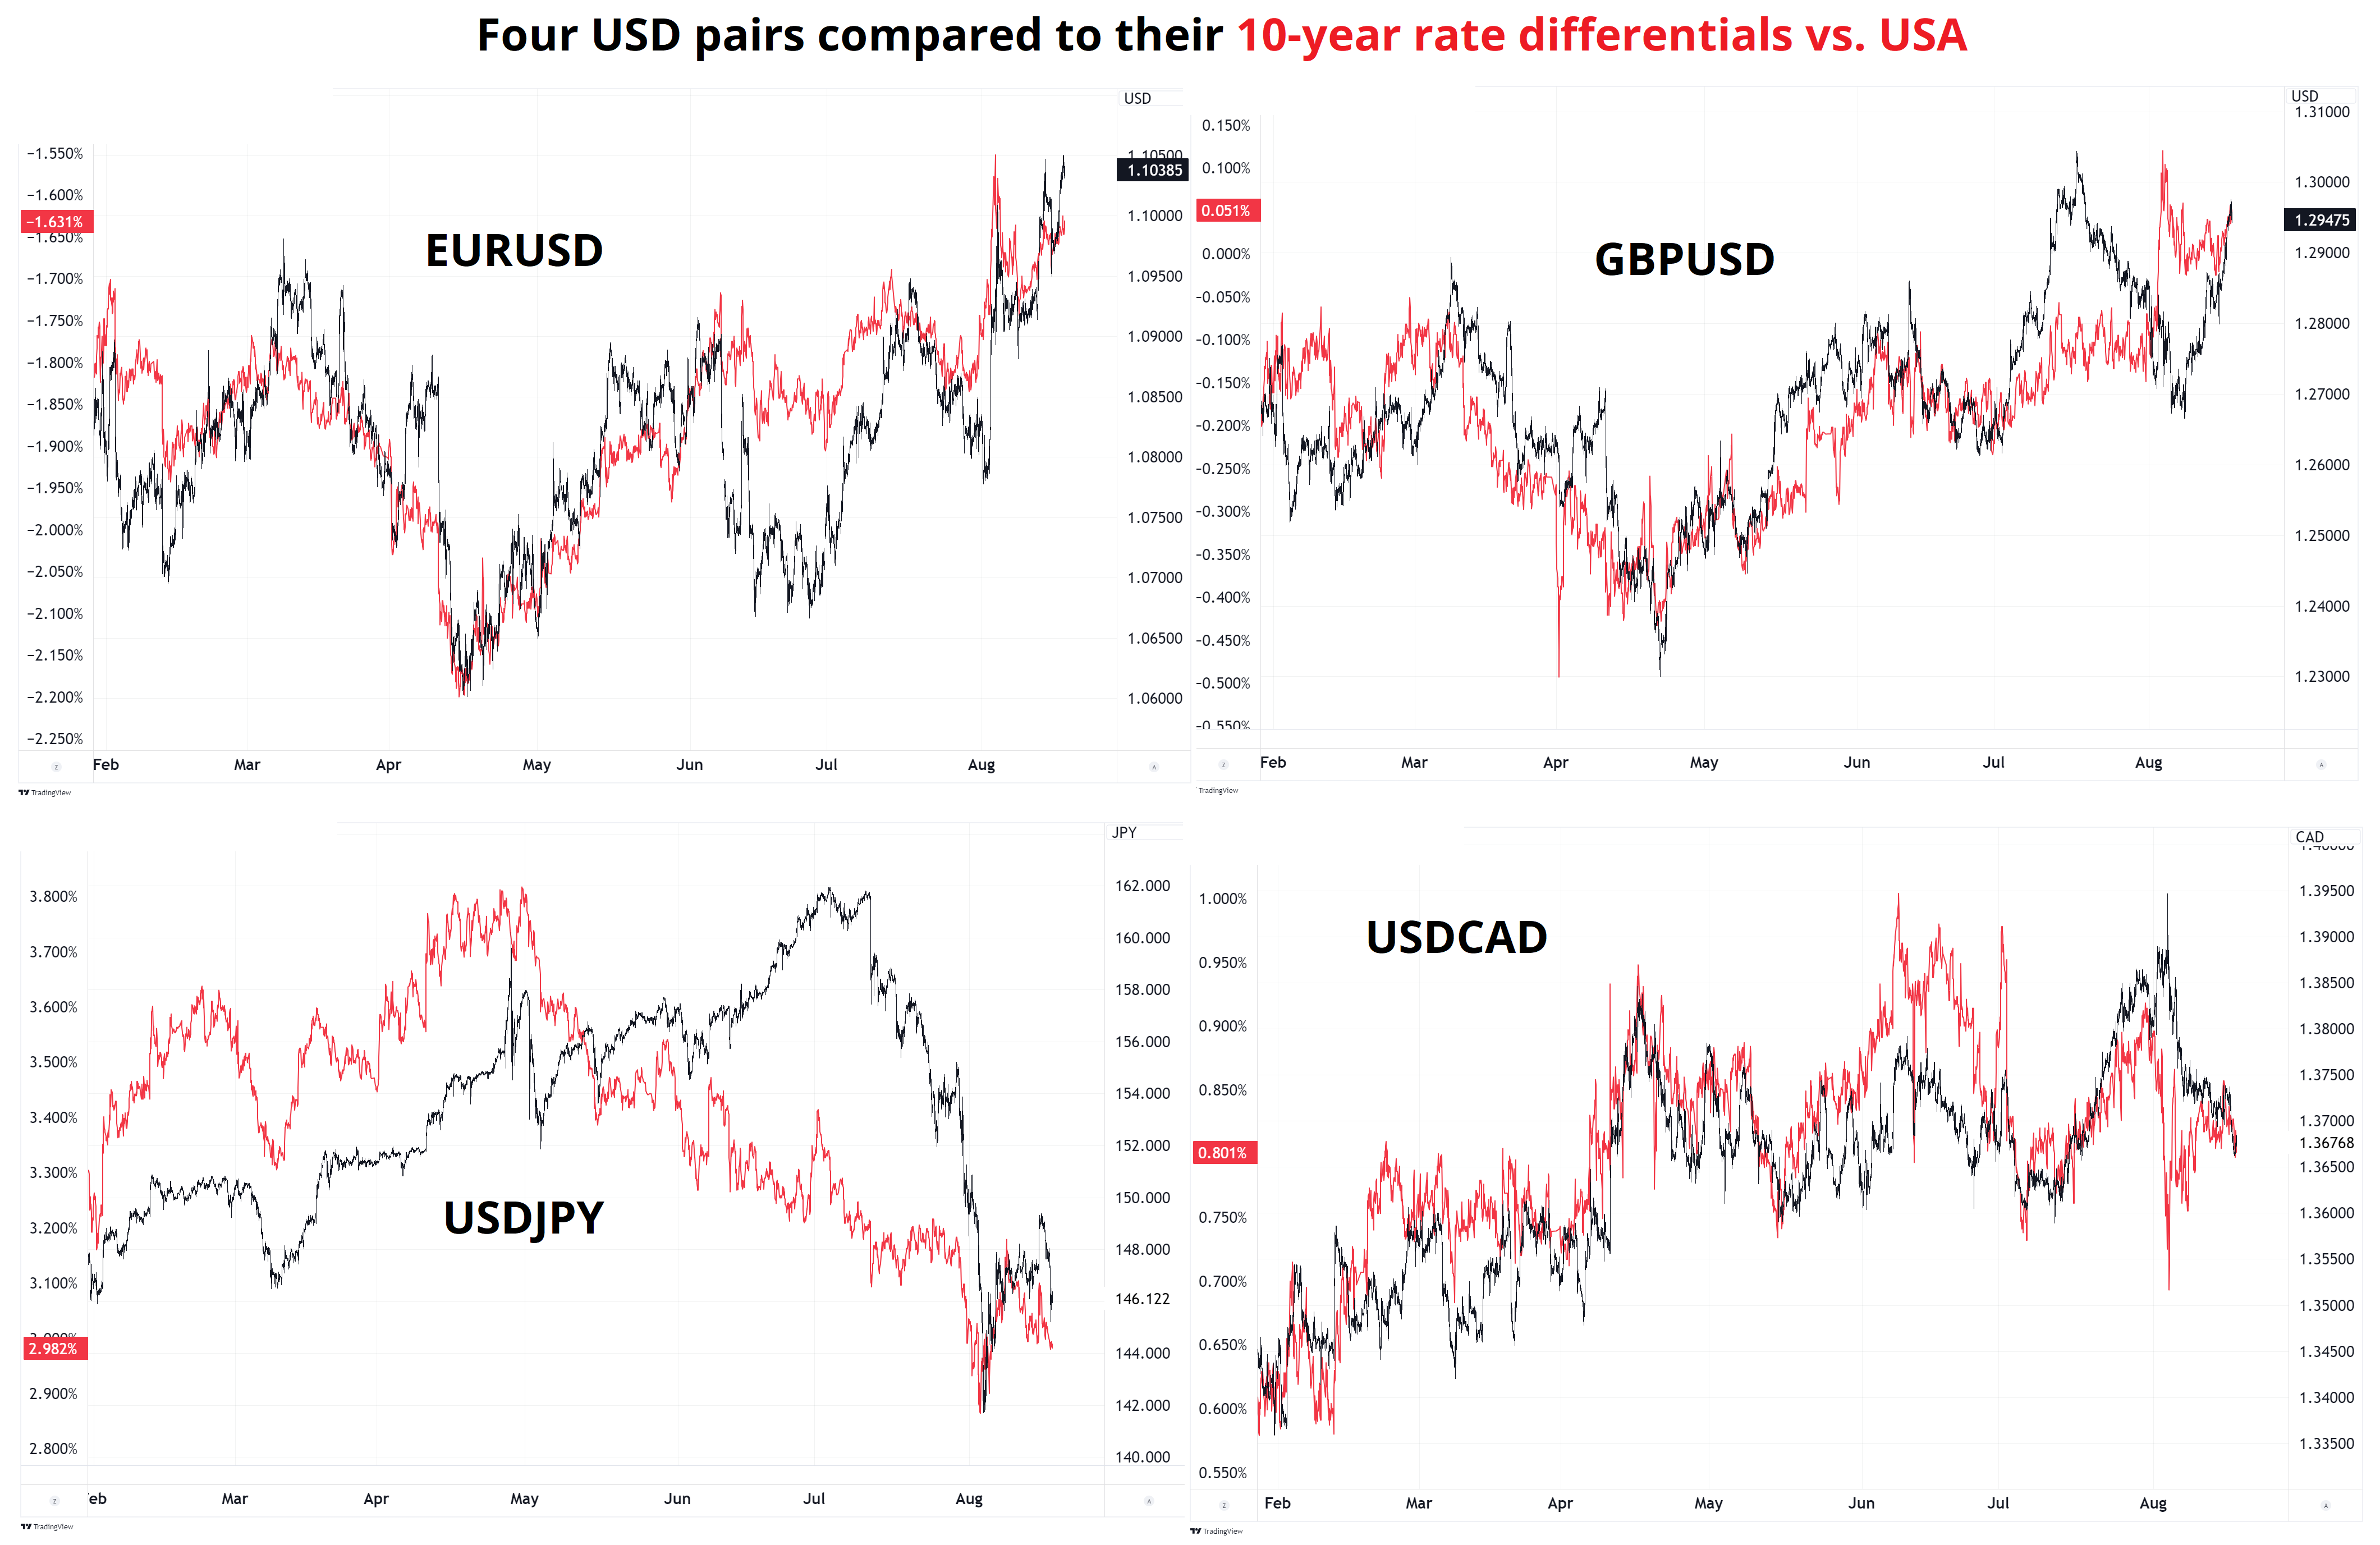
While EURUSD look a bit high vs. rate differentials, most pairs are within range of where they “should” be. It’s just that it took a couple of weeks to get there. Now that we are here, I am not sure further USD weakness is justified as the most likely message from Western Wyoming is one of gradualism and 25bp cuts. Obviously the 06SEP NFP release might have something to say about things, but there is no reason to expect anything weak there.
The Employment component of ISM Services and the continued stability in Initial Claims and Retail Sales suggest the US jobs market continues to cool but is not anywhere close to recessionary. We might also see a flick back lower in the UR as the “could not work due to weather” factor unwinds. Also, the important resistance in EURUSD is coming soon at 1.1100/30. With rates and FX now neatly recoupled, the path of least resistance for the dollar is no longer down. Finally, there are a couple of bond auctions this week, and auction weeks have been better than non-auction weeks for the dollar. Rangebound is my base case for EURUSD this week, let’s say 1.0960/1.1100.
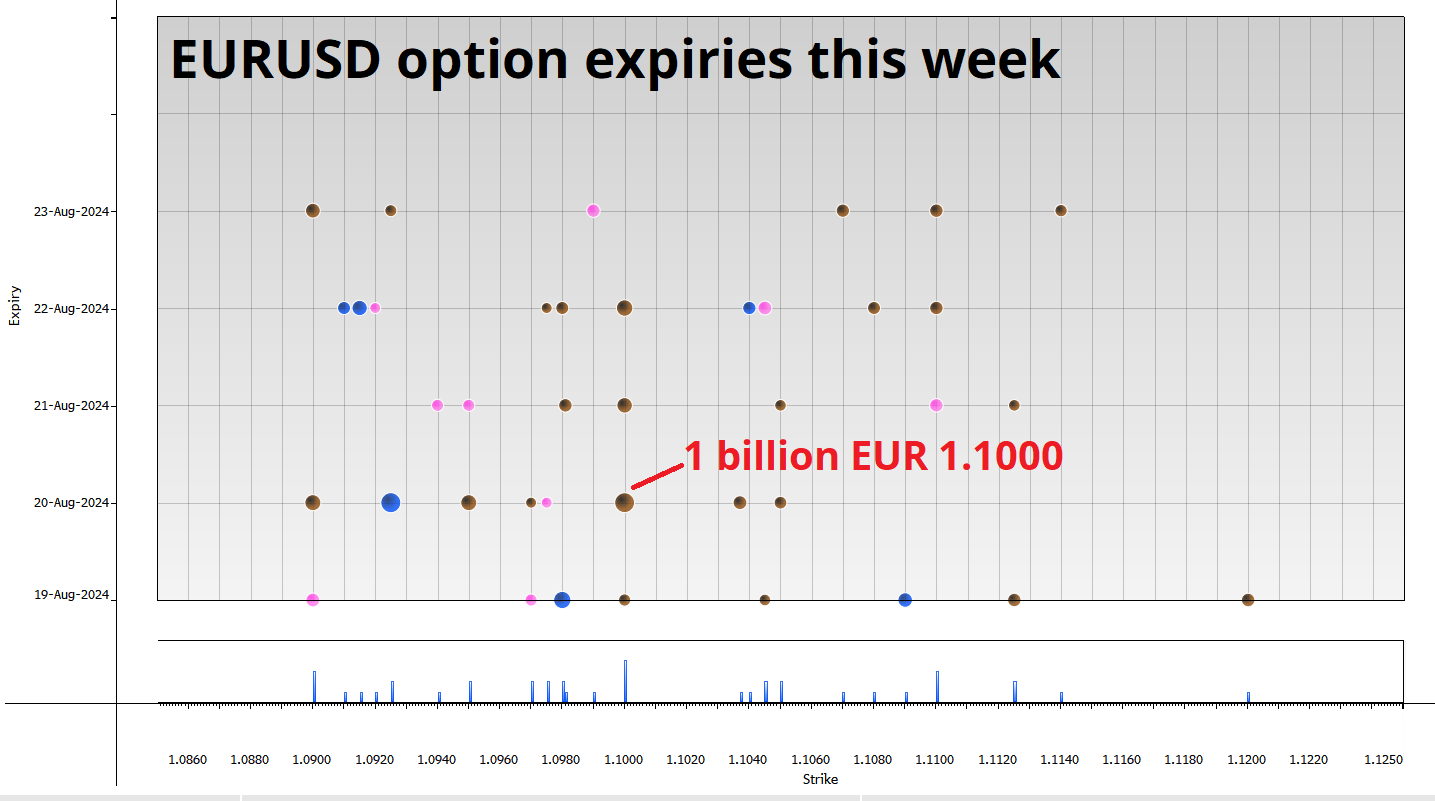
In options land, there is not much to report, with the exception of a one billion 1.1000 EUR expiry tomorrow and some others clustered 1.1035/50 (also expiring tomorrow). Here are the expiries:
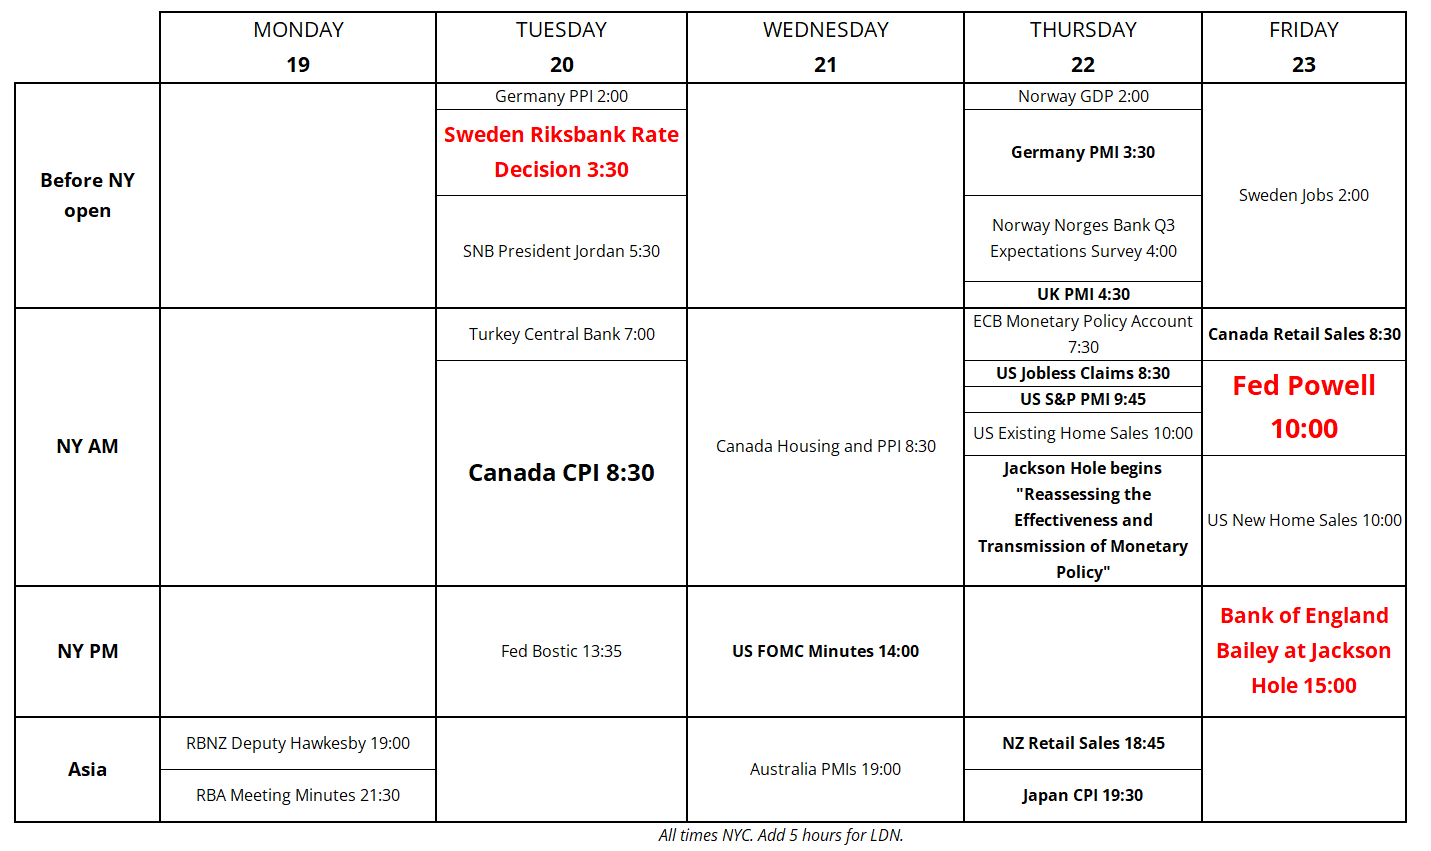
Riksbank and SNB Jordan tomorrow, and Canada CPI as we wait for Jackson Hole. There is some drama around J-Hole, as usual. Chairman Powell delivers a speech on the economic outlook at 10 a.m. NY time on Friday.
Have a peak day.
Relief and population density maps for the United States