

You can listen to this episode right here.
Not a subscriber? Sign up here
Today’s note is 2000 words (9-minute read)
The bull trade continues but MSTR has come too far
The Merge dominates the crypto zeitgeist as buying continues into a touted week of 19SEP merge date. The Goerli Testnet Merge went live yesterday and everything is looking A-OK. No sign of any explosions or huge arc flashes of light and heat blowing up the blockchain, so there should be another four weeks of buying the rumor before it’s time to sell the fact in ETH.
Meanwhile, regulators are blowing as much hot air and sound and fury at crypto as they possibly can, and the market’s response so far has been like:
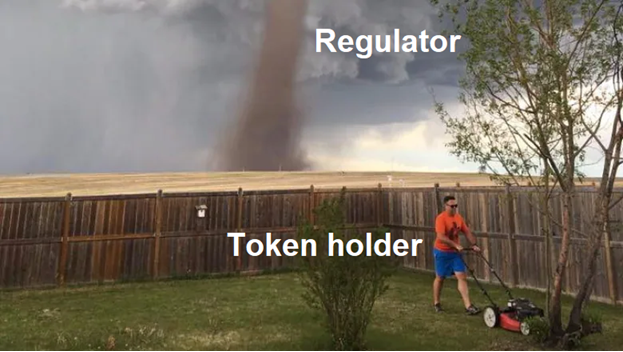
The tornado could take a long time to get here, or it might never arrive, so for now there is not much concern despite the brief histrionics after the Coinbase insider trading complaint described nine tokens as securities.
Speaking of Tornado… regulators tossed another arbitrary Molotov cocktail at crypto this week. Two good stories about it here:
https://thedefiant.io/usdc-addresses-banned
https://techcrunch.com/2022/08/12/suspected-tornado-cash-developer-arrested-in-amsterdam/
There has been a huge bounce in equities and that got a jetpack surge after the weak US CPI figure on August 10.
The cryptocentric story remains bullish (as long as you ignore the US regulators, which basically everyone is doing) … and the boot is off the neck of macro for a bit. Here is how BTC, ETH, and NASDAQ have done so far this year:
Monthly return of BTC, ETH, and NASDAQ (2022)
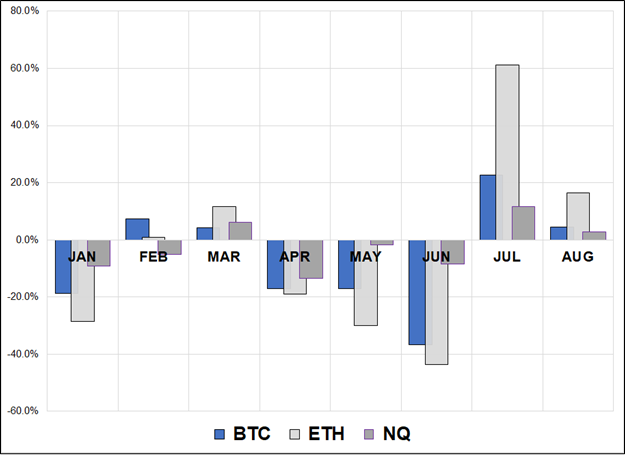
July was a mega month for everything risky, but you can clearly see Merge Fever in there as ETH exploded higher. Also worth noting: February 2022 is the only month this year where crypto and NASDAQ went opposite directions (NASDAQ down, crypto up).
You can see ETH Fever in this next chart too. BoomerCoin volatility is bumping along the lows while ETH vol is mid-range.
BTC vs. ETH rolling 10-day standard deviation of daily returns
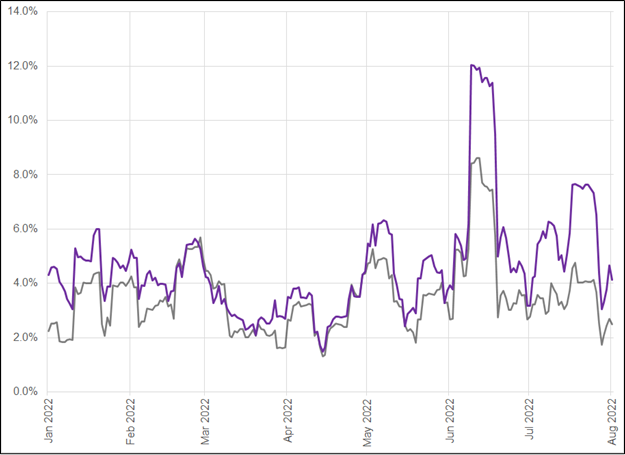
The overall vibe at Club Crypto is still pretty lame, but ETH is dancing like nobody’s watching in the side room.
Halving pain is over
Here is a flashback to MTC#5 for context before I discuss where we are now in the bitcoin halving cycle.
From MacroTactical Crypto #5: Nobody Will Tell You When To Sell
November 2021
Halving cycle is bearish
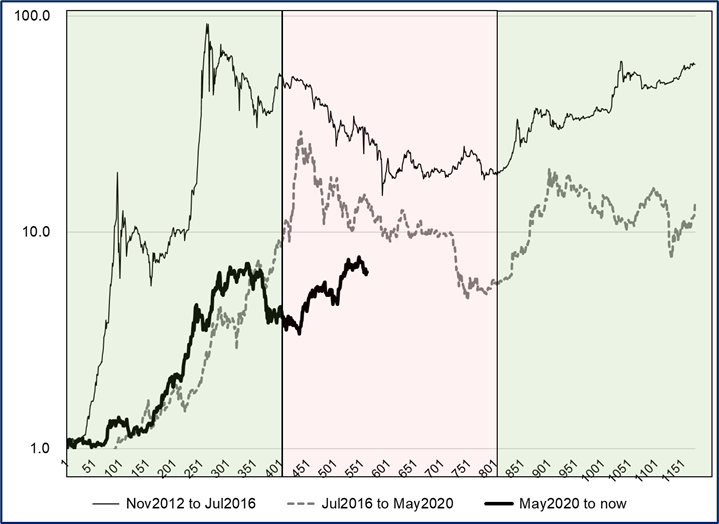
Every 1200 days or so, the reward for mining bitcoin transactions is cut in half. Each halving has been followed by an epic bull run, then a super cold period, then another bull run in anticipation of the next halving cycle. See:
Bitcoin performance over the three halving cycles
The BTC and crypto hype machine is 10X more powerful than the 1999/2000 internet hype machine. Nobody is ever going to tell you when to sell. It is borderline verboten for anyone in crypto to even utter a bearish word. Keep that in the back of your mind. Every story you ever hear is going to be bullish. It’s cool to HODL but just make sure you can survive the next winter.
Also note in that chart that each bull run is less impressive than the last as market cap rises and it becomes impossible for the next wave to outgrow the last. This is why the Plan B model becomes less and less accurate. The halvings are mathematically less important (lower overall impact) and the law of large numbers kicks in. It’s easier to grow from 1 billion to 1 trillion than it is to grow from 1 trillion to 1 quadrillion. Obviously.
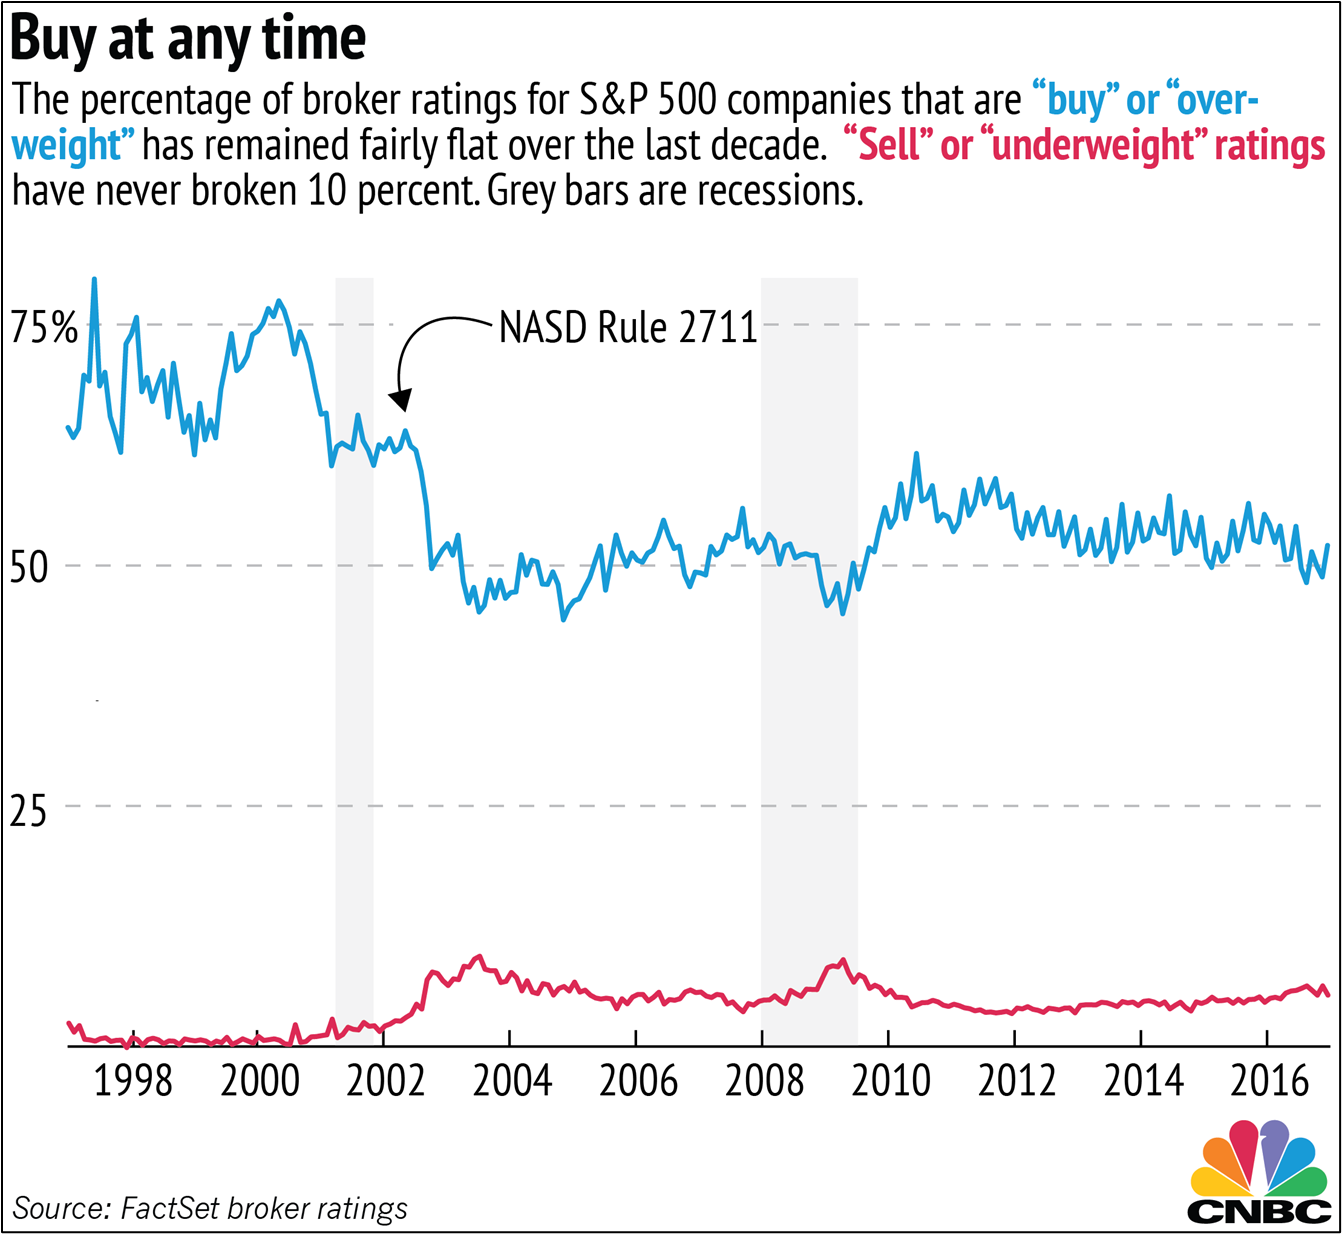
Sidenote: As part of its continuing speed run through the history of TradFi, Big Crypto has copied the 1999 Wall Street playbook as it employs primarily three recommendation levels: BUY, STRONG BUY and IRRESPONSIBLY LONG! Crypto is down 50%-80% off the highs and still 99% of all the recommendations on every Big Crypto or YouTube or whatever are BUY BUY BUY. All the way down.
After the dotcom crash, FINRA tried to balance the buy vs. sell noise with Rule 2711. Here is how well it worked:
Exchanges, custodians, advertisers, VCs, investors, entrepreneurs, developers, and everyone else in crypto space wants you on board! Most crypto analysis is advertising masquerading as research. Keep this in mind in the next bull run. Nobody will ever tell you when to sell. That’s why you have to think for yourself and know the bias of the content you consume. End of sidenote.
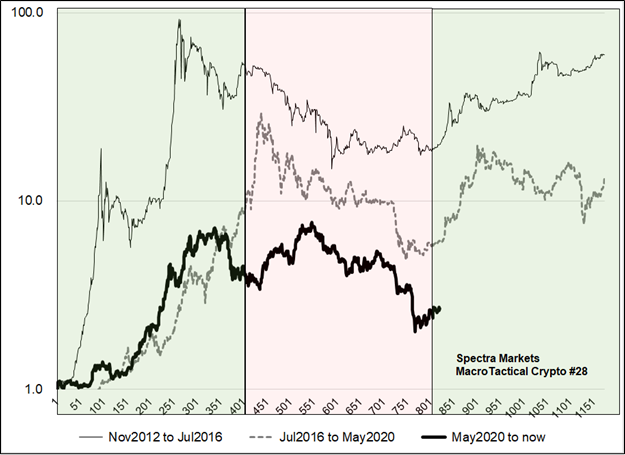
The reason I cut and pasted that MTC5 excerpt is that the Halving Cycle has now turned. Here is the chart from that note, up to date. It is a thing of beauty.
Bitcoin performance over three halving cycles
With assistance from Justin Ross
That’s another crypto-positive factor to add to the list. Nice!
The first cycle, BTC went up 91X, the second one it went up 28X, this one has been around 8X at the peak. This reflects the higher price of the asset, the lower volatility, greater liquidity, larger market cap, and more mature price discovery process. Extrapolations like the Rainbow Chart don’t make any sense as they naively assume a steady rate of price increase over time and ignore the factors listed above (and the law of large numbers). Trees do not grow to the sky. If you’re not familiar with the Rainbow Chart, I strongly recommend you do not bother Googling it.
Mister MSTR
You can build a pretty basic xls to estimate a “fair value” of MicroStrategy and plug in a few assumptions to see where it’s trading relative to that “fair value” or “NAV” or whatever you want to call it. Sure, there is a software business there, but you can just throw whatever number you want on that, and it doesn’t matter that much because the volatility of the software business is dwarfed by the volatile value of the golden-eyed dragon’s big huge stack of shiny bitcorns.
What is interesting is how the price of MSTR diverges from the fair value estimate. Of particular note is that the premium to NAV right now is back to the wides on the back of the recent management shakeup. Saylor is out as CEO of MicroStrategy and he will now focus on the bitcoin strategy exclusively. As if that wasn’t what he was doing before! He can now spend even more time on increasing his production of borderline insane tweets like this one:
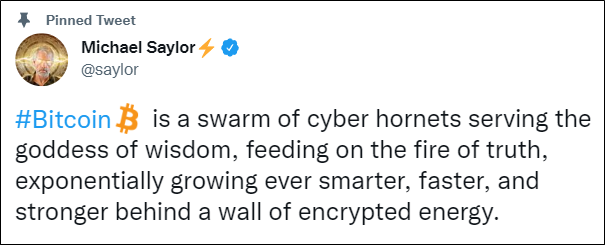
One foot on each side of the genius/madness line!
For my valuation model, I assume the software business was worth $500 million in January 2020 and the value of that business goes up and down with the NASDAQ. This is debatable, but the number I use here doesn’t matter because what I’m interested in is the relative movement of the stock price vs. net asset value. I don’t care what the actual spread is in dollars, I only care if it’s relatively wider or tighter than usual. And that entire spread is driven by the value of the underlying bitcoin vs. the stock price. The assumptions you use for the business don’t matter.
I have a chart below that shows “fair value” in blue, MSTR stock price in gray, and the ratio of fair value to stock price in purple underneath. The fair value calculation is:
Software business value + (total bitcoins * price of bitcoin) + current assets – liabilities
Like I said above, the assumptions you use for software business don’t change things very much because the fair value number is driven by the volatility of bitcoin. As such, I think it’s a pretty good model for evaluating the richness or cheapness of MSTR. Here’s the chart:
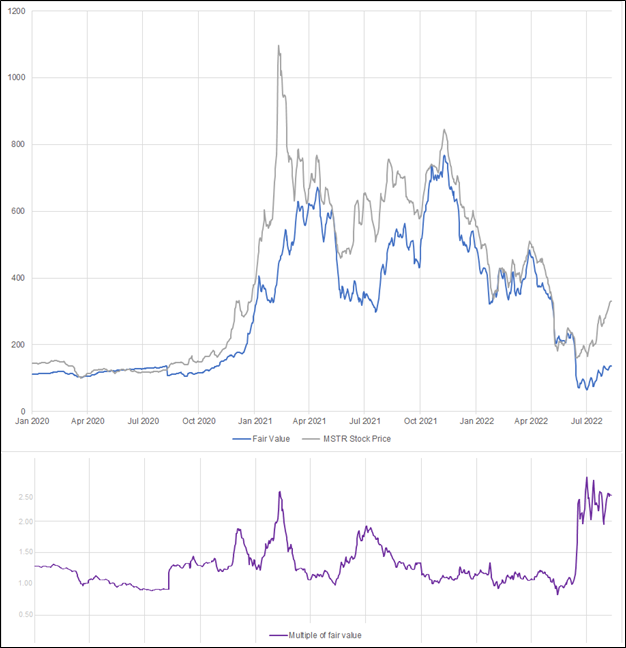
This is not a DCF exercise. DCF is BS, 99% of the time. This is just marking BTC to market over time. Not DCF. I hate DCF.
Astute observers will notice that the spikes in MSTR’s premium to fair value occur at the same time as the meme stock explosions in early 2021 and June 2021. Now, meme stocks are ripping and MSTR has done some kind of jiggedy restructuring of management and MSTR is kind of a meme stock. This makes sense! Not only does the crypto audience overlap substantially with the meme stock crew, loose financial conditions attract funny money to both crypto and meme stonks. Also, the market is always mega short meme stocks and mega short MSTR so when one of those rallies, hedge funds feel the pain in one and race to cover shorts in the other.
So when you trade MSTR, you are trading a weird combo of: (The price of bitcoin + meme stock momentum). MSTR is a good long bitcoin proxy when the premium to fair value is low and it is probably a bad bitcoin proxy (for longs) up here at 2.5X fair value. If you are bearish crypto or meme stocks or think this current wave of liquidity and loosening financial conditions is about to roll back out… Short MSTR makes sense.
Either way, it’s probably a good time to either be flat or short MSTR, not long. To be clear, I’m not necessarily saying the price of MSTR is too high… I’m saying relative to the value of the underlying assets, the price of MSTR is much, much higher than it was a few months ago. My feeling is there is a ceiling somewhere and last time up, that ceiling was right here. “Overpriced” can move to “more overpriced”. But the next time I get bearish crypto, I’ll be selling MSTR, not BTC.
Trade at your own risk. Do your own research.
Conclusion
The base still looks decent in crypto, the ETH Merge story is bullish for another few weeks, nobody believes the Fed is fully serious about inflation, and net flows are positive for crypto. And we are now on the bullish side of the halving cycle. Macro is unlikely to remain supportive for long, but it’s full steam ahead for now and probably at least until Powell speaks at Jackson Hole in late August.
The two main ranges to monitor in BTC remain unchanged. Nearby range is 20000/25000 and 18700/28300 on the wide. The path of least resistance in ETH remains up into the week of 19SEP. Then buy the rumor / sell the fact in September if all goes according to plan.
Before you go, if you’re a trader … Here’s a good weekend read for you: Justin and I wrote a solid piece on the prickly issue of whether or not good traders vary bet size based on confidence levels. You can read it here.
And this is my 30-minute Crypto chat on Twitter Spaces hosted by Bloomberg.
That’s it ! Thanks for reading … See you next week.
bd