Today, a slightly longer piece (4 pages, 7-minute read) looking at how Liz Truss may or may not impact GBP as the new PM of the UK.
This is not the stamp in question,
it’s just a cool stamp from Korea.
When was the first
postage stamp issued?

Today, a slightly longer piece (4 pages, 7-minute read) looking at how Liz Truss may or may not impact GBP as the new PM of the UK.
This is not the stamp in question,
it’s just a cool stamp from Korea.
When was the first
postage stamp issued?
Stop loss 4366
Take profit 4010
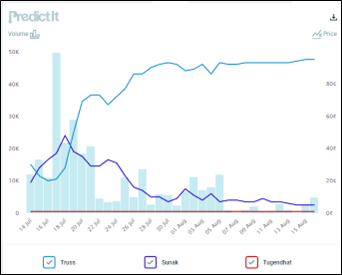
On September 5, the United Kingdom will have a new Prime Minister and her name will probably be Mary Elizabeth (Liz) Truss. Current gambling odds place her as a 1:8 favorite, and the movement of the odds since July looks like this:
The Party member ballot will close at 5pm on Friday 02SEP. The winner will be announced on 05SEP. That winner will become Leader of the Conservative Party and the next Prime Minister.
With a Truss win a somewhat foregone conclusion, it’s worth knowing what she might mean for the future of the UK economy, gilts, and the pound. First a few facts to set the table. As I chatted with UK peers and colleagues, I learned that the Liz Truss topic is a highly charged political discussion, even when you are just hoping to talk about the economics. I don’t have a political view here; I’m just trying to figure out whether to be long or short pounds.
Truss is a bit hard to pin down because:
Some key things to know re Truss:
Foreign Secretary Liz Truss, the front-runner to succeed Boris Johnson as prime minister, has said the UK is facing an unprecedented economic situation and that the “business as usual economic strategy” isn’t working. The BOE should remain independent, but the time has come to revisit its mandate, she said. In a newspaper article, Truss said the recent commodity-induced inflation spike has been “exacerbated by monetary policy.” How she would revise the current system is unclear. She hasn’t said she would scrap inflation targeting but did mention the possibility of widening the target to include a measure of money supply or nominal gross domestic product.
The consensus view is that these policy proposals are bearish for gilts and bearish for GBP. This quote is a good summary of the consensus view:
“Truss’s policy platform poses the greatest risk from an economic perspective in our view with an unseemly combination of pro-cyclical tax cuts and institutional disruption,” Citi’s chief UK economist, Ben Nabarro, wrote in a note.
The argument is that more fiscal spending will swell deficits while any review of the BOE’s remit is bad for institutional stability and could reduce BOE independence and lead to a flight from UK assets. This makes sense on the surface, but there are some pretty good counterarguments.
From a Liz Truss editorial in the Telegraph
Headline: I will pave the way to economic growth with an emergency budget
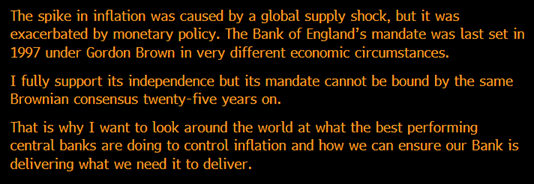
So, imagine her looking around the world. “Hmmm, inflation is really high everywhere. Except Japan. They must be doing something right!” You might think I’m joking. But check this out:
She said the next government should look at other economies that had been successful in controlling inflation, citing the Bank of Japan which has faced repeated bouts of deflation in recent decades despite running the biggest quantitative easing program of all major central banks.
This sounds like something out of The Onion. And she was once UK Treasury Secretary. Amazing. She is worried about high inflation and nodding to BOJ policy as a solution. C’mon. Anyway, given her views about the BoE are poorly informed and make zero sense, my guess is that they will be reprogrammed. Especially because she comes across as pragmatic / flexible, not super dogmatic. If she is open to new information, the new information will be something like:
Advisor
“But Ms. Truss, the Bank of Japan is the loosest central bank in the world. It owns more government debt than the BOE and is the largest equity shareholder in Japan. Their balance sheet is 135% of GDP and ours is 40%. They have been pegging rates at zero for eons. If we did that here, CPI would be 25%.”
Liz Truss
“Oh. Ok, forget it.”
When Truss enters office in September, she will need to prioritize a massive list of risks and issues. I just don’t think the BOE remit will be on that list. Or if it is, it will be a watered-down, long-term word salad kind of thing where nothing ever comes of it. Regardless, when I think about the changes in the central bank remits around the world… NZ added housing, USA went to average inflation targeting… Was any of it actionable? Not really. Maybe for two months or something. Global central banks are all fighting the same war with similar weapons.
Down the road, a scenario where Truss attempts to defang the BOE as they outhike the momentum of her inflationary fiscal plans could be a possibility, but I think that’s something to worry about later. Or never.
There is a bullish GBP scenario where the Bank of England tries to offset looser fiscal by tightening monetary and the GBP rips as positioning is mega short, sentiment could not be more bearish, and yield direction still drives currencies most of the time. The problem with trying to trade this bullish scenario right now is:
At the risk of getting overly complicated, I think there is a good chance that there is a kneejerk GBP selloff into and after a Truss victory, but it’s short-lived and GBP then finds a base and rips higher, especially against the EUR. If you’re gonna trade long GBP, I think short EURGBP is the ticket because it mostly strips out the energy crisis as the EU suffers from the same energy woes as the UK.
Perhaps short gilts is just the easier trade and the currency is too complicated, but the “down a bit then up a lot” trade in GBP seems highly likely to me. Far down the road, deficits might matter or the BOE might outhike the fiscal and drive the UK economy further into the ground, but the takeaway here is:
I don’t think selling GBP on a Truss victory is a good idea. To summarize:
First order impact: More fiscal. Sell gilts, buy GBP.
Second order impact: BOE remit review. Sell gilts, sell GBP if it happens?
Third order impact: Bigger deficits, more credit risk. Sell gilts, sell GBP.
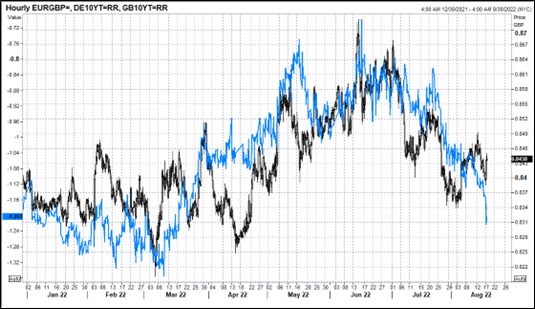
It almost looks like the market is trying to do the “sell UK fixed income + sell GBP trade” in recent days as EURGBP rallies while gilts sag. You can see that here:
OK, that’s it for today. Thanks for reading. I am not a UK politics expert. Feedback is welcome.
Just for fun… Here’s Liz Truss, as a Liberal Democrat at age 19, discussing the monarchy and other stuff.
Have a liberally democratic, yet conservative day.
The first stamp ever: The Penny Black
Issued in May 1840
There were 68 million issued overall
https://robbreport.com/shelter/art-collectibles/worlds-first-postage-stamp-auction-1234643844/
This one went for $450 on eBay
Or get a full plate of 12 for $800,000

This piece is mostly for people who are interested in backtesting