
A look at the macro similarities between 2000 and 2021 and what that might mean for the dollar. And stocks.


Subscriber-only
Brazil, Canada, yen
A sort of almost unbelievably large move in Brazil. Plus: Short CADJPY.

A look at the macro similarities between 2000 and 2021 and what that might mean for the dollar. And stocks.
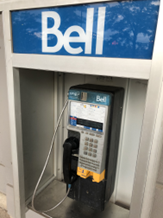
This strange technology was spotted
outdoors last week by an am/FX
reader in Niagara Falls, Ontario.
It’s a public phone and you put coins
or a credit card in it to call people. You
can even use it for long distance.
Apparently it’s called a “payphone”.
September 1, 2022
First of all, my entire piece yesterday has gone out the window as Swiss inflation comes in above expectations and the big EUR squeeze could already be over. There is always a risk of looking stupid when I put a short-term trade like this in am/FX. Fortunately, this is bad decision/good outcome as I cut with a 12 pip profit and move on. I would be more comfortable with EURAUD or EURCAD longs as I think VIX is about to go north of 30, but nothing in the official trades for now.
As Michael Saylor was accused of tax fraud by the DC attorney general yesterday, the quantum entanglement between the 2000 dotcom bubble and the 2021 crypto bubble continues to amaze me[1]. While there are obviously differences, the macro stories then and now line up pretty well:
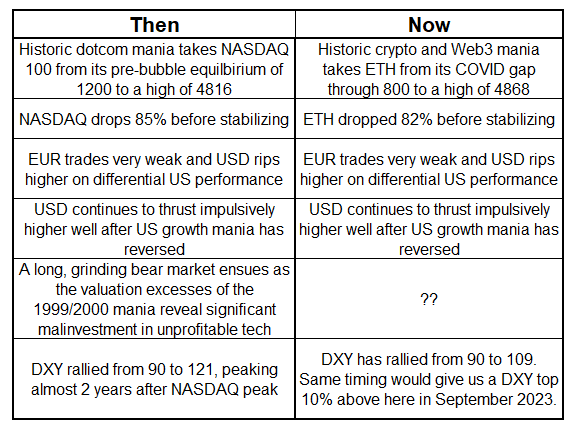
It’s silly to expect everything to play out identically to last time and my belief is that we are in a combination of 2001 and 2018 markets as Fed policy now is more like 2018 than 2001. The Fed had already cut eight times by September 2001, whereas now they are hiking and just doubled QT. The main takeaways are:
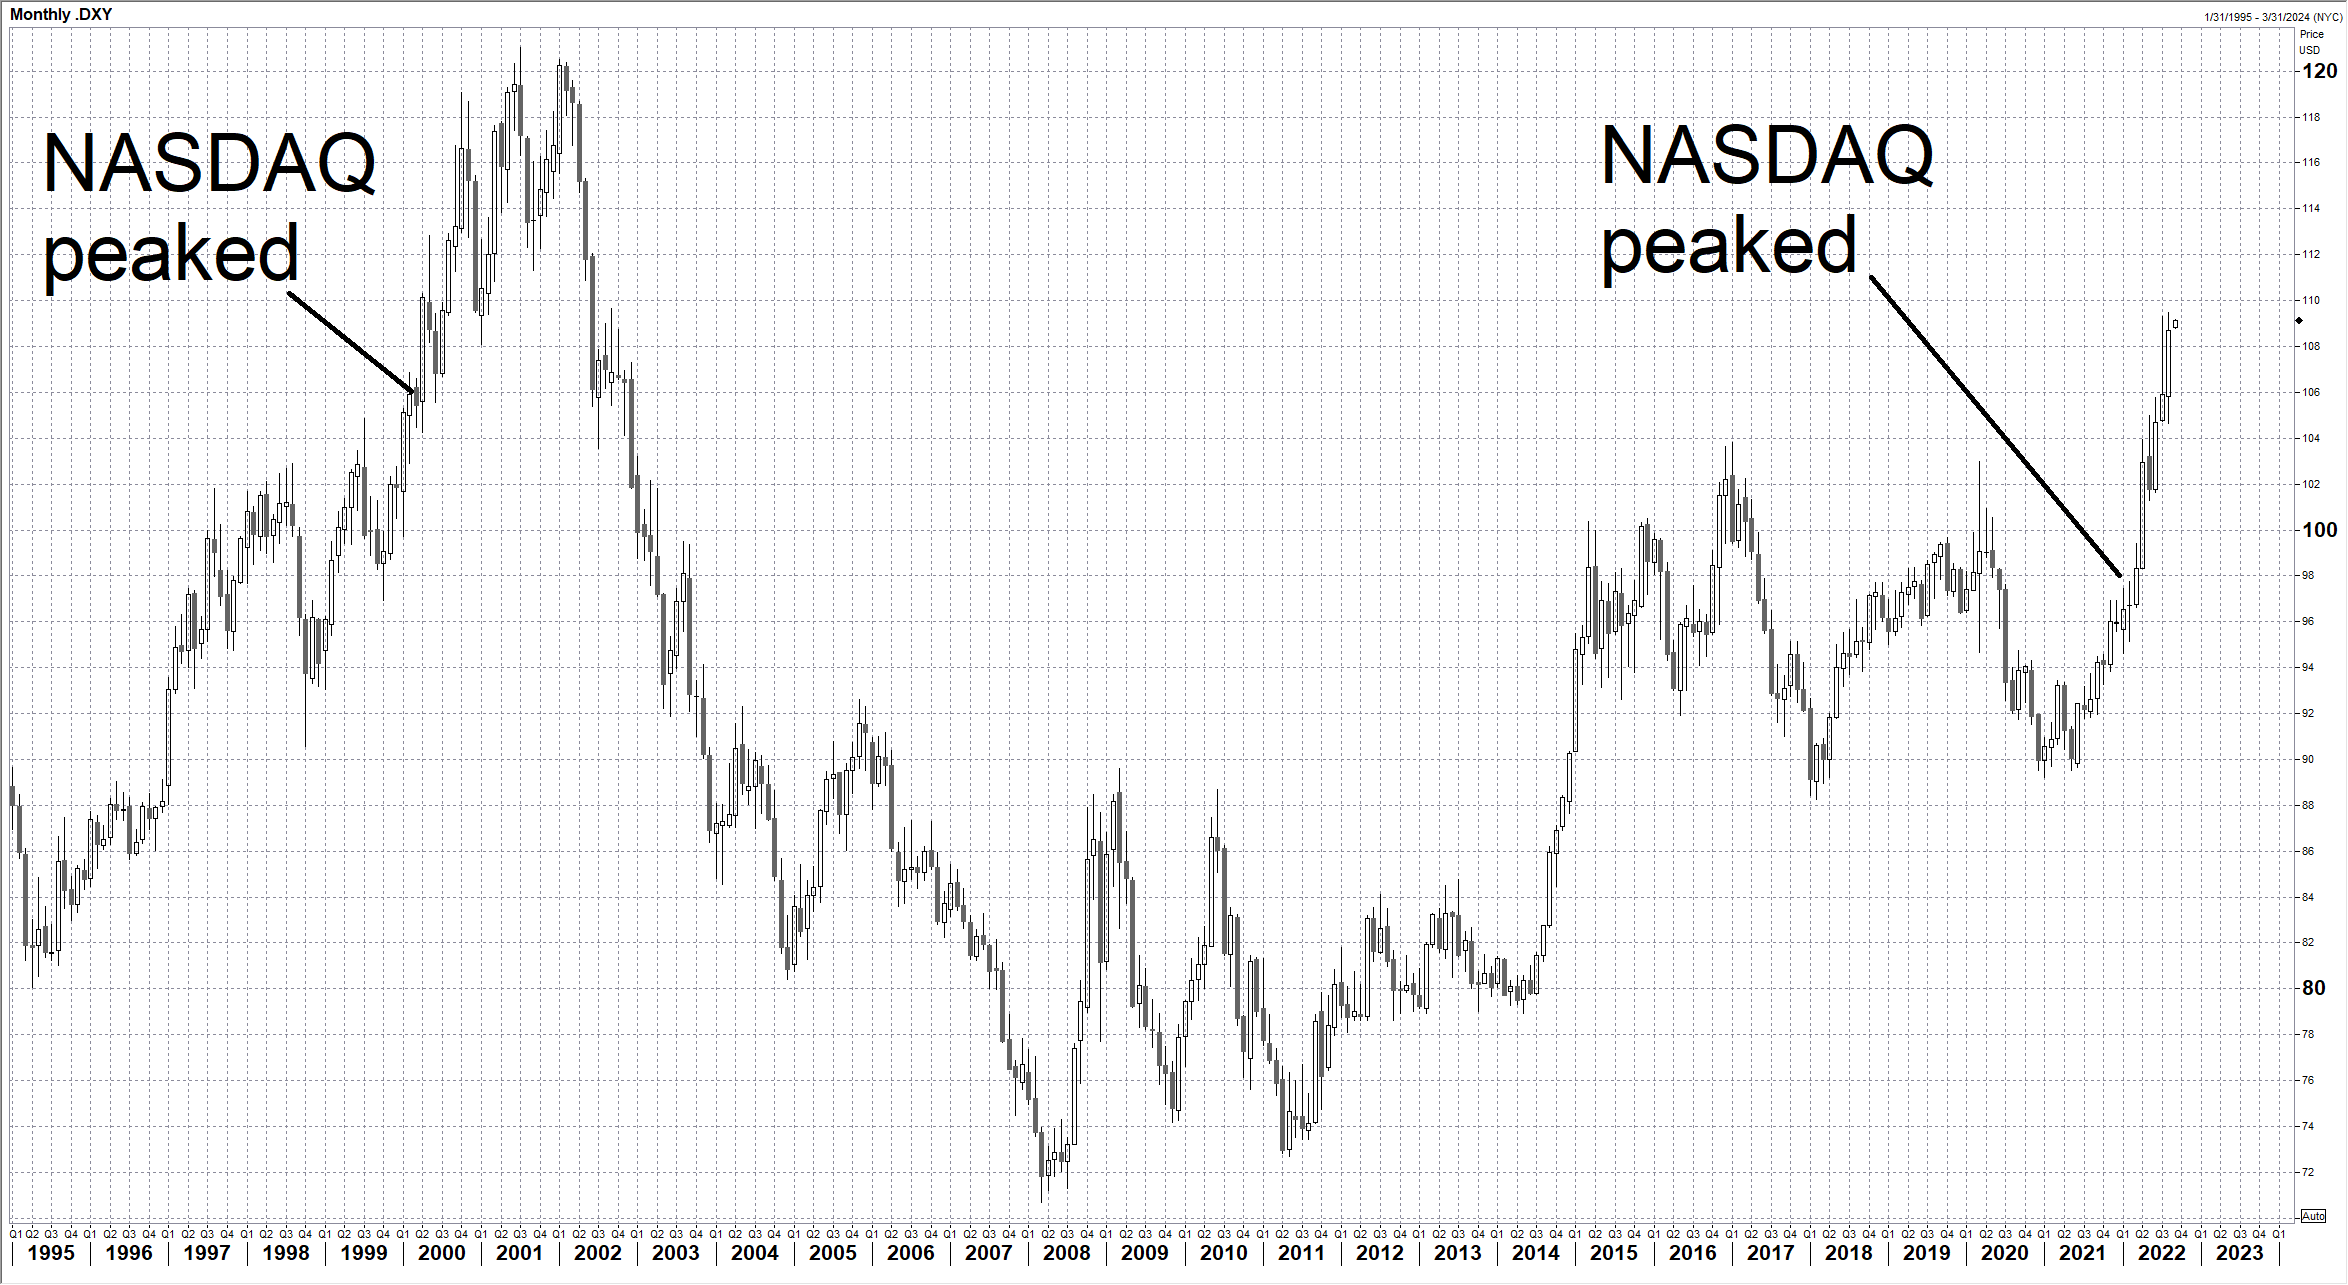
Here is a chart of the DXY so you can see the rhyming:
It is at least mildly interesting that the DXY started at the same level (90.00) and got to 121 in 2000. This USD rally is more impulsive and less choppy than the 2000 rally, probably because Fed policy is unambiguous whereas much of the 2000/2002 DXY rally happened in synch with Fed rate cuts.
If you combine the 2001 bubble unwind with 2018 tightening, 1970s inflation, and a 2010-2020 QE-era addiction to buying the dips… You get the current market. It took 12 Fed cuts in 2001 before the bottom finally hit. This market was trying to buy the dip on hopes for a pair of cuts a year out in 2023, right into the worst seasonal period of the year.
Wacky.

[1] https://www.nytimes.com/2000/12/15/business/microstrategy-chairman-accused-of-fraud-by-sec.html
There has been a record surge in new subscribers this month and I would like to inform all the new peeps of a few things:
1-year USDJPY carry is now 4.3% which means with vol and skew, you can buy a 1year 150.00 digital for 15%. The 1-year ATMF digital is 133.90 right now with spot at 139.65. Spicy! Long-dated topside USDJPY is an interesting product when rates and vol are on the move. Thanks, Sal, for pointing this out.
Have a well-connected day.
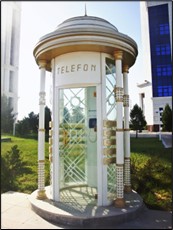
A pay phone in Turkmenistan
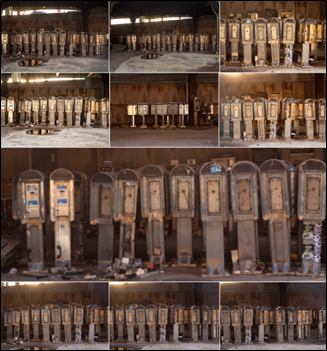
A payphone graveyard under the West Side Highway in NYC
A sort of almost unbelievably large move in Brazil. Plus: Short CADJPY.

NZD has a bunch of bullish kickers: Election, seasonality, and inflation
