Forecasting is hard .. Plus EUR seasonality and BoC thoughts.
Polar bear snoozing in summer

Forecasting is hard .. Plus EUR seasonality and BoC thoughts.
Polar bear snoozing in summer
December 5, 2022
I hereby acknowledge that my forecast for AHE last week was about as bad as they get. “Juuuuusssst a bit outside.” Forecasting is hard. Let me deflect my own bad forecast by distracting you with some others.
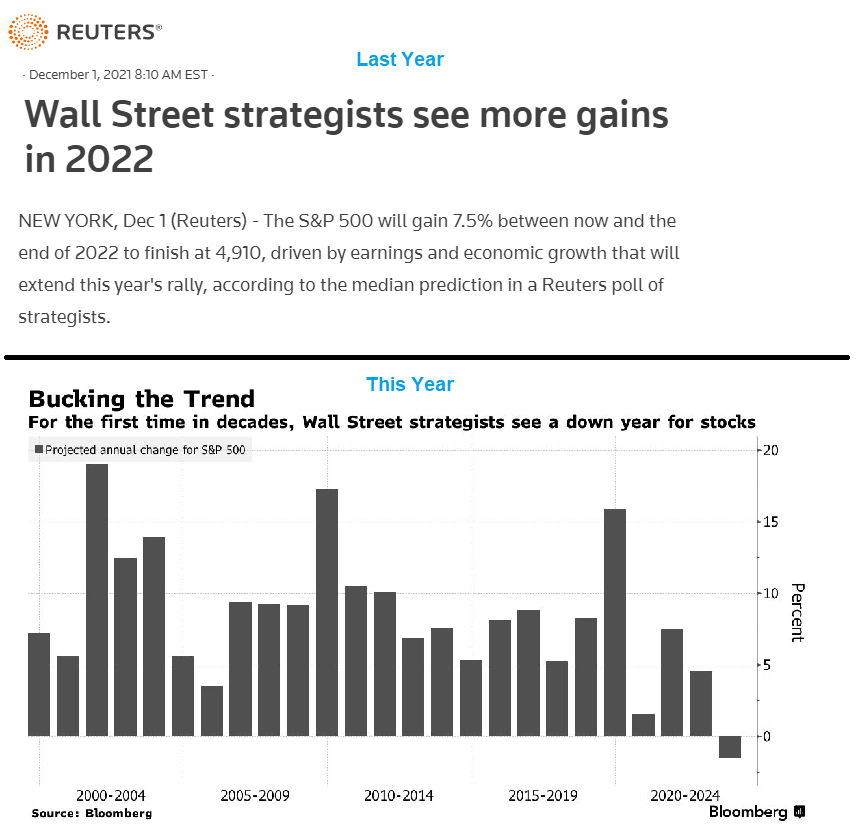
Here is how the S&P forecasts are looking, last year vs. this year. Hmm.
Followers of forecasts know that for the most part, forecasts just follow spot. This is because once a forecast is sufficiently wrong, the analysts will revise it towards spot so that it seems less ridiculous. Analysts with 5200 year end forecasts for S&P in 2022 won’t just leave that hanging out all year, they will keep revising down so that the forecast is always (current level X 1.1) or whatever.
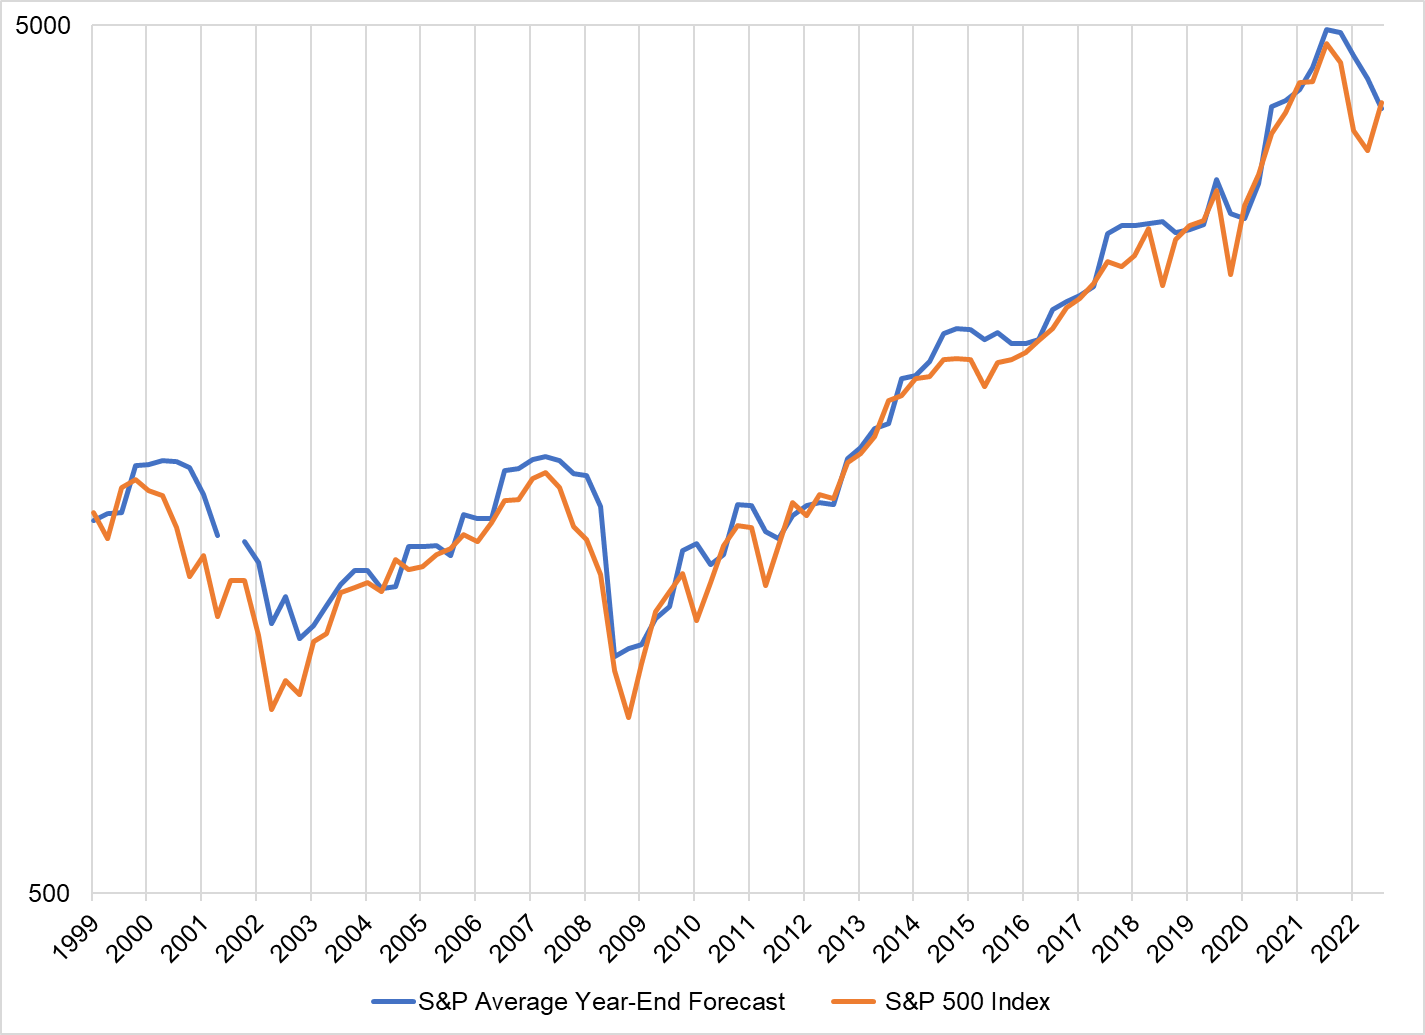
This is not a criticism, it’s just how the game works. The alarming thing about this bearish lean in the forecasts is that I am also bearish stocks for 2023. Seeing the bearish consensus does not make me change my mind, because the consensus is not always wrong. But it certainly opens my mind to more optimistic and bullish scenarios. The obvious one would be that the US economy hangs in, inflation falls, China reopens, and Europe and the UK skate through the winter somewhat unscathed. It’s possible!
On the other hand, the Fed hiking into an accelerating recession as the market has tried to play “bad news is good news!” is my base case. Like 2001, where the market ripped when the Fed paused, and then sold off for a long, long time once the market realized that recession with sticky inflation is bad.
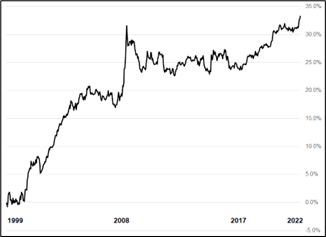
EURUSD is following the December playbook so far, and doing nothing wrong. The December seasonality in EUR is well-known, and I mentioned it last week, but I thought it would be useful to show the path of the EUR in December today. Just so you can see how it played out over the years. The effect was super consistent from inception to 2008, then disappeared from ’08 to ’17. It has been back, but way more subdued in recent years. 2022 is a weird one as a potential EU recession and collapsing EU Trade Balance loom. But if the EUR buying is just bank repatriation, that’s not going to care about fundamentals.
While EURUSD trades well in the face of pretty neutral news flow, AUDUSD trades terribly as positive China reopening news flow accelerates and USDCNH plummets through 7.00. Sure, AUD is higher but it’s getting lapped by NZD and there’s no reason EUR should be passing it in the outside lane. Price action in Oz is highly sus. Good news, bad price.
There is room for the Bank of Canada to sound dovish this week, in sharp contrast to the RBNZ. The market is priced for a 50/50 chance of either 25 or 50 bps and a dovish 50bps would make sense in the context of what has always been a strategy billed as “front loading.” Macklem has consistently described the Bank’s aggressive hikes this way, and if you’re front loading it makes sense to hike more and stop when you think you’re good.
Given the massive financial stability risks around Canadian debts (and thus higher sensitivity to rate hikes) + the limping GDP data since May (monthly figures of 0.0, 0.1, 0.1, 0.1, and 0.1) there is an argument for a pause. Then again, the Canadian labour market has been crazy strong just like the US, and CPI looks peaky but still extremely high.
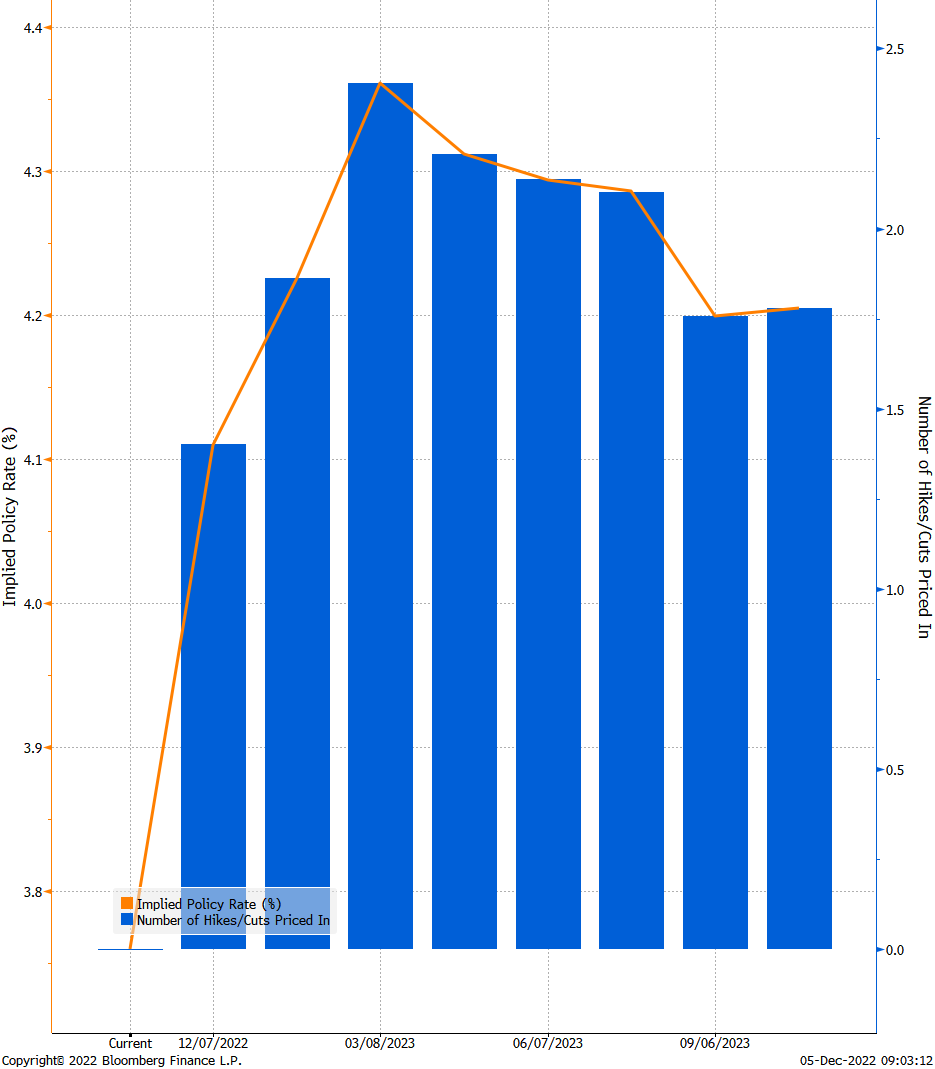
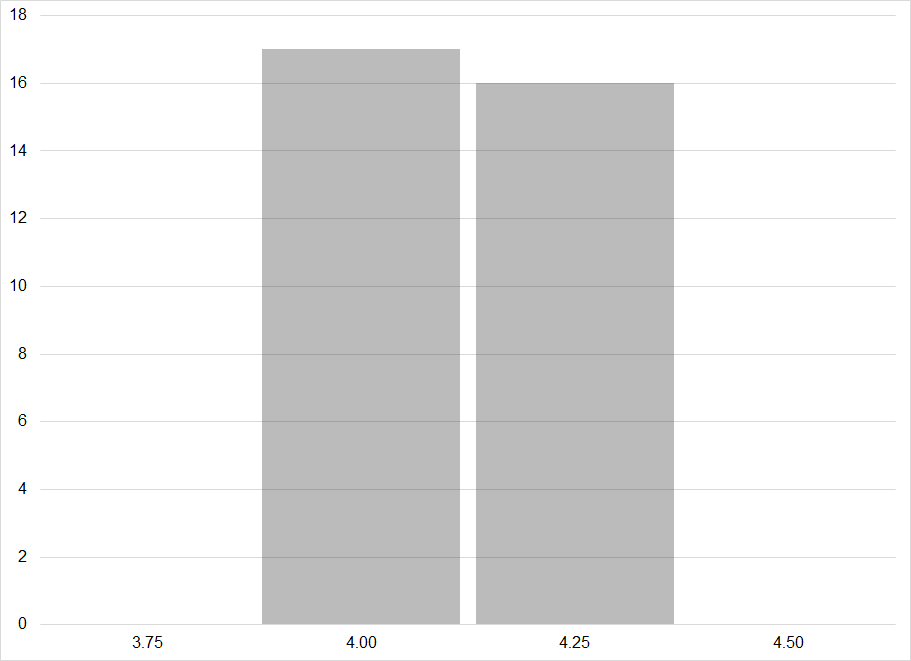
I would lean towards a dovish 50bps this week. ~35bps are priced for the meeting, and as I usually do before big events, I made a histogram of economist forecasts. It is probably the stupidest histogram I have ever made and perhaps I could have done even worse by presenting a pie chart. Anyway, here it is. Maybe it’s so bad, it’s good?
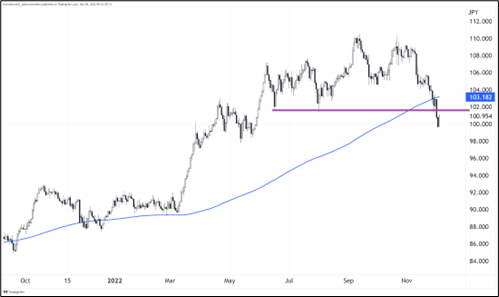
The move higher in risk appetite and USDJPY has provided an OK entry point now for short CADJPY. Here is the chart, which shows the dream entry is more like 101.40/70. That is the purple horizontal line that marks the old lows from June and August. Old support should now be resistance and then you have the 200-day at 103.18 in blue. I am not doing this trade right now because I have a feeling that Friday’s price action in yields has shown us the new equilibrium for now and I’m not sure there is a lot more downside for US yields in the short-term. If US yields stabilize here and BoC is dovish, that could be the juice for a move back under -200 in 2-year CAD forwards (currently trading -153).
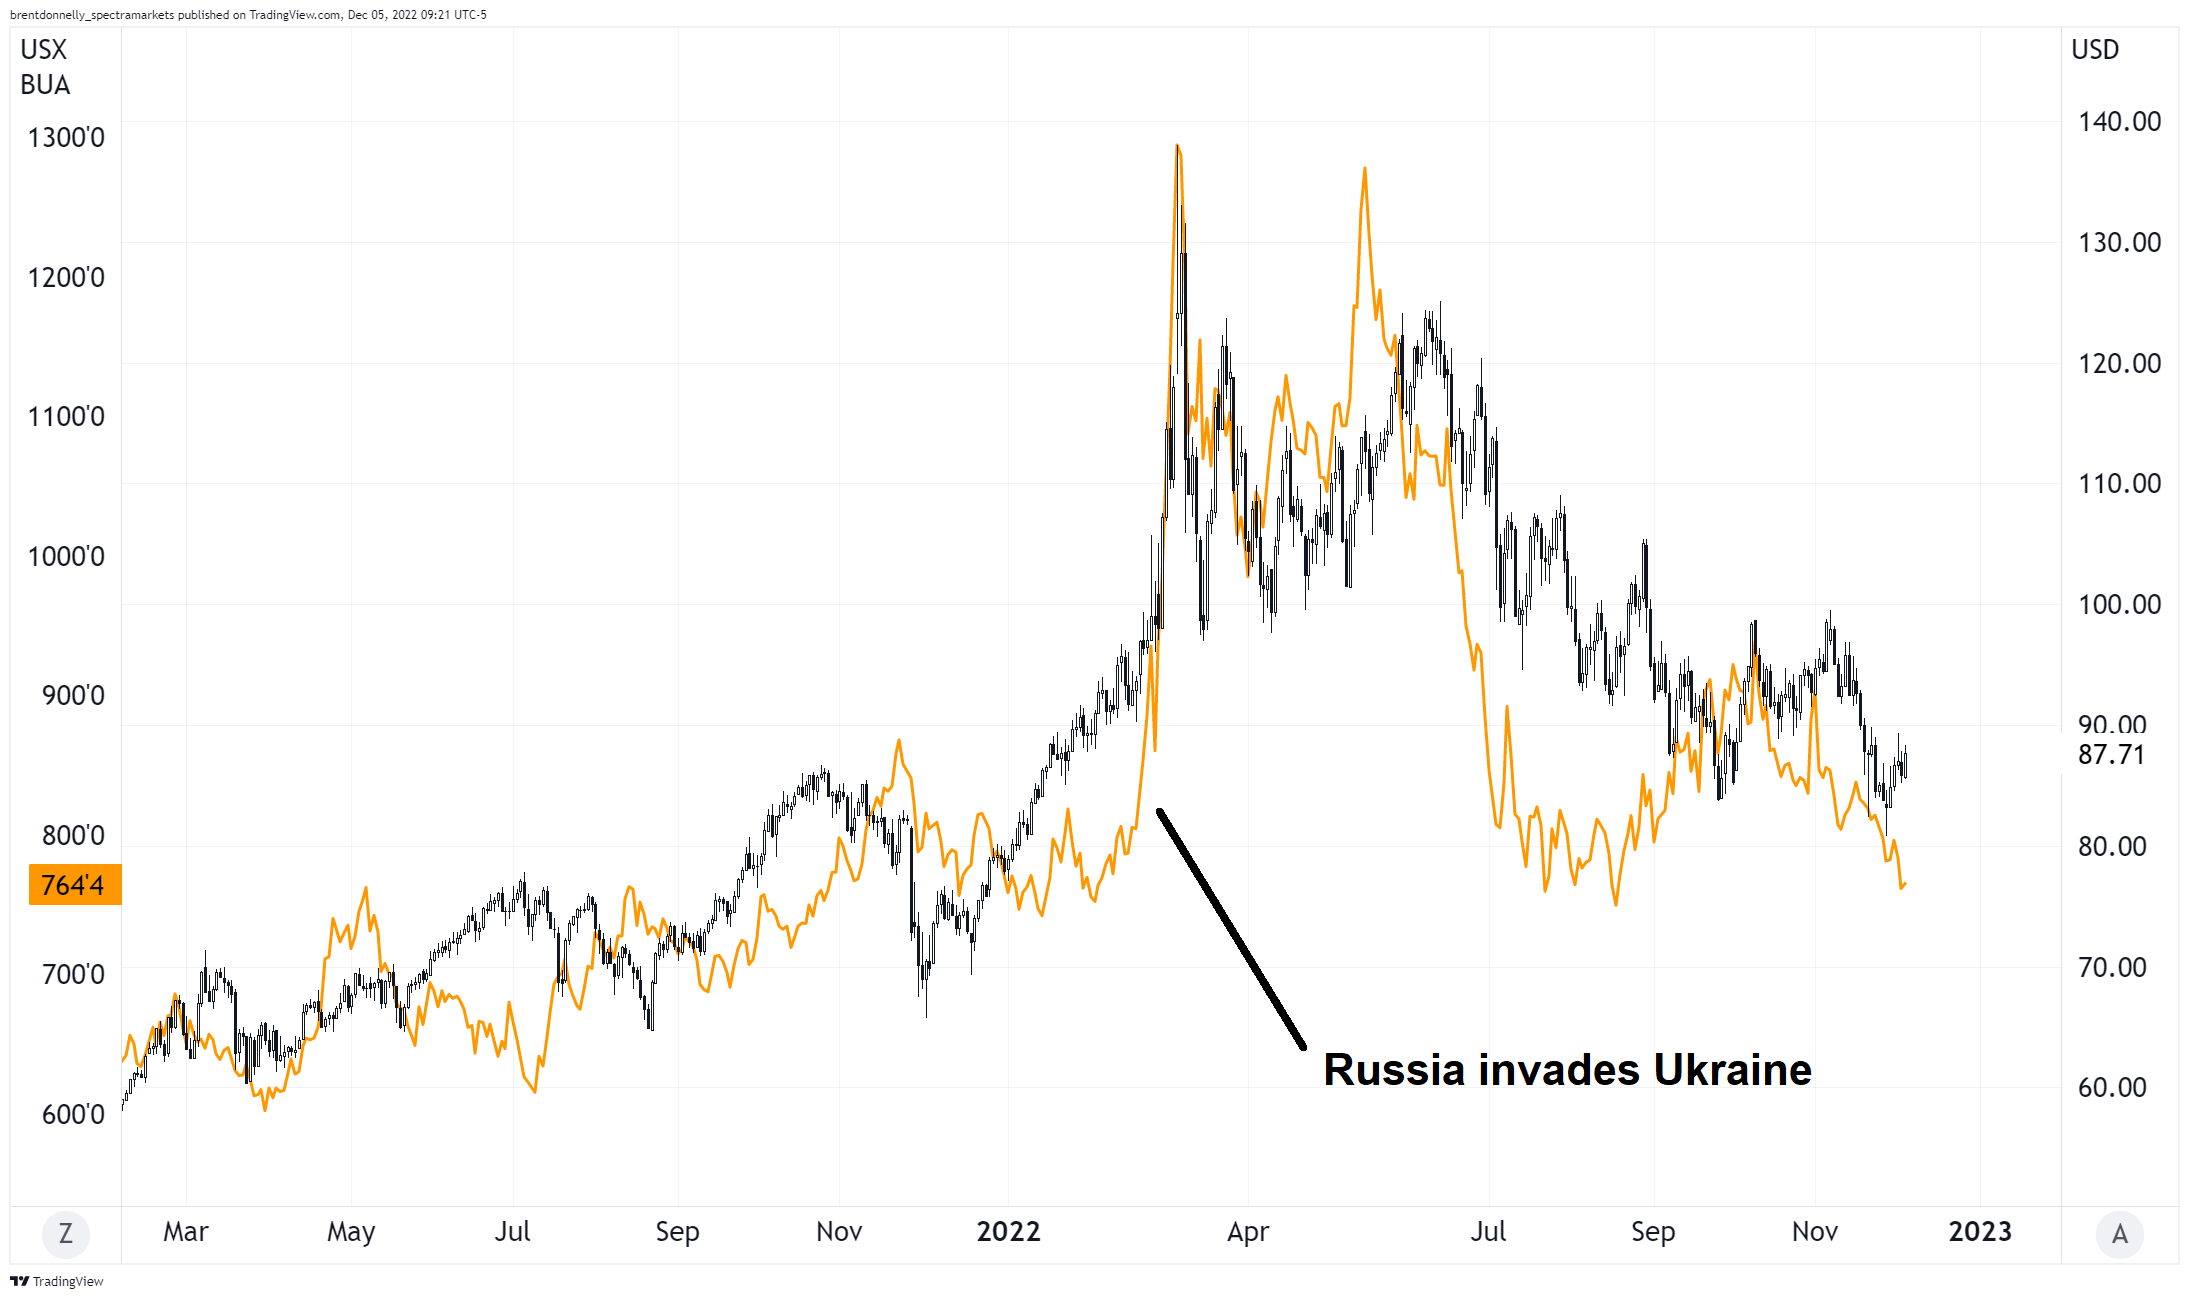
Who would have thought. Wheat and oil unchanged on the year. Crazy.
This podcast featuring Edward Chancellor (financial historian) is way less boring than it sounds. Some nice insights on the time value of money, the history of interest rates, and the destructive impact of manipulating interest rates too low for too long.
Have an alphabetical day.
A photographer spends two months in the Canadian Arctic and reveals a softer side of the world’s largest terrestrial predator.
—
It’s impressive how National Geographic has maintained relevance from my childhood to now.


A sort of almost unbelievably large move in Brazil. Plus: Short CADJPY.

NZD has a bunch of bullish kickers: Election, seasonality, and inflation