
Today’s piece is a little bit about GBP and mostly about JPY.


Subscriber-only
Brazil, Canada, yen
A sort of almost unbelievably large move in Brazil. Plus: Short CADJPY.

Today’s piece is a little bit about GBP and mostly about JPY.
Barry Manilow wrote “Like a Good
Neighbor, State Farm is There,”
“I’m Stuck on Band-Aid Brand
Because Band-Aid’s Stuck on Me,”
and “You Deserve a Break Today
at McDonald’s.”
Stop loss 1.1374
Take profit 1.1839
Stop loss 159.29
Take profit 165.99
Stop loss 1.4884
Take profit 1.5684
September 6, 2022
The bullish Fazoola GBP trade is off to a good start as Day One of Trussonomics sees a spike higher on the first fiscal pronouncements. There is plenty of opportunity for the GBP trade to go horribly wrong still as the market (and I) could be totally off base here, but for now this feels analogous to when a football or baseball team changes managers and a twinkle of hope appears out there in the darkness. Keep an eye on UK CDS for warning signs that this Trussian fiscal largesse is scaring people. CDS have moved a bit wider but remain in familiar territory near the bottom half of the five-year range.
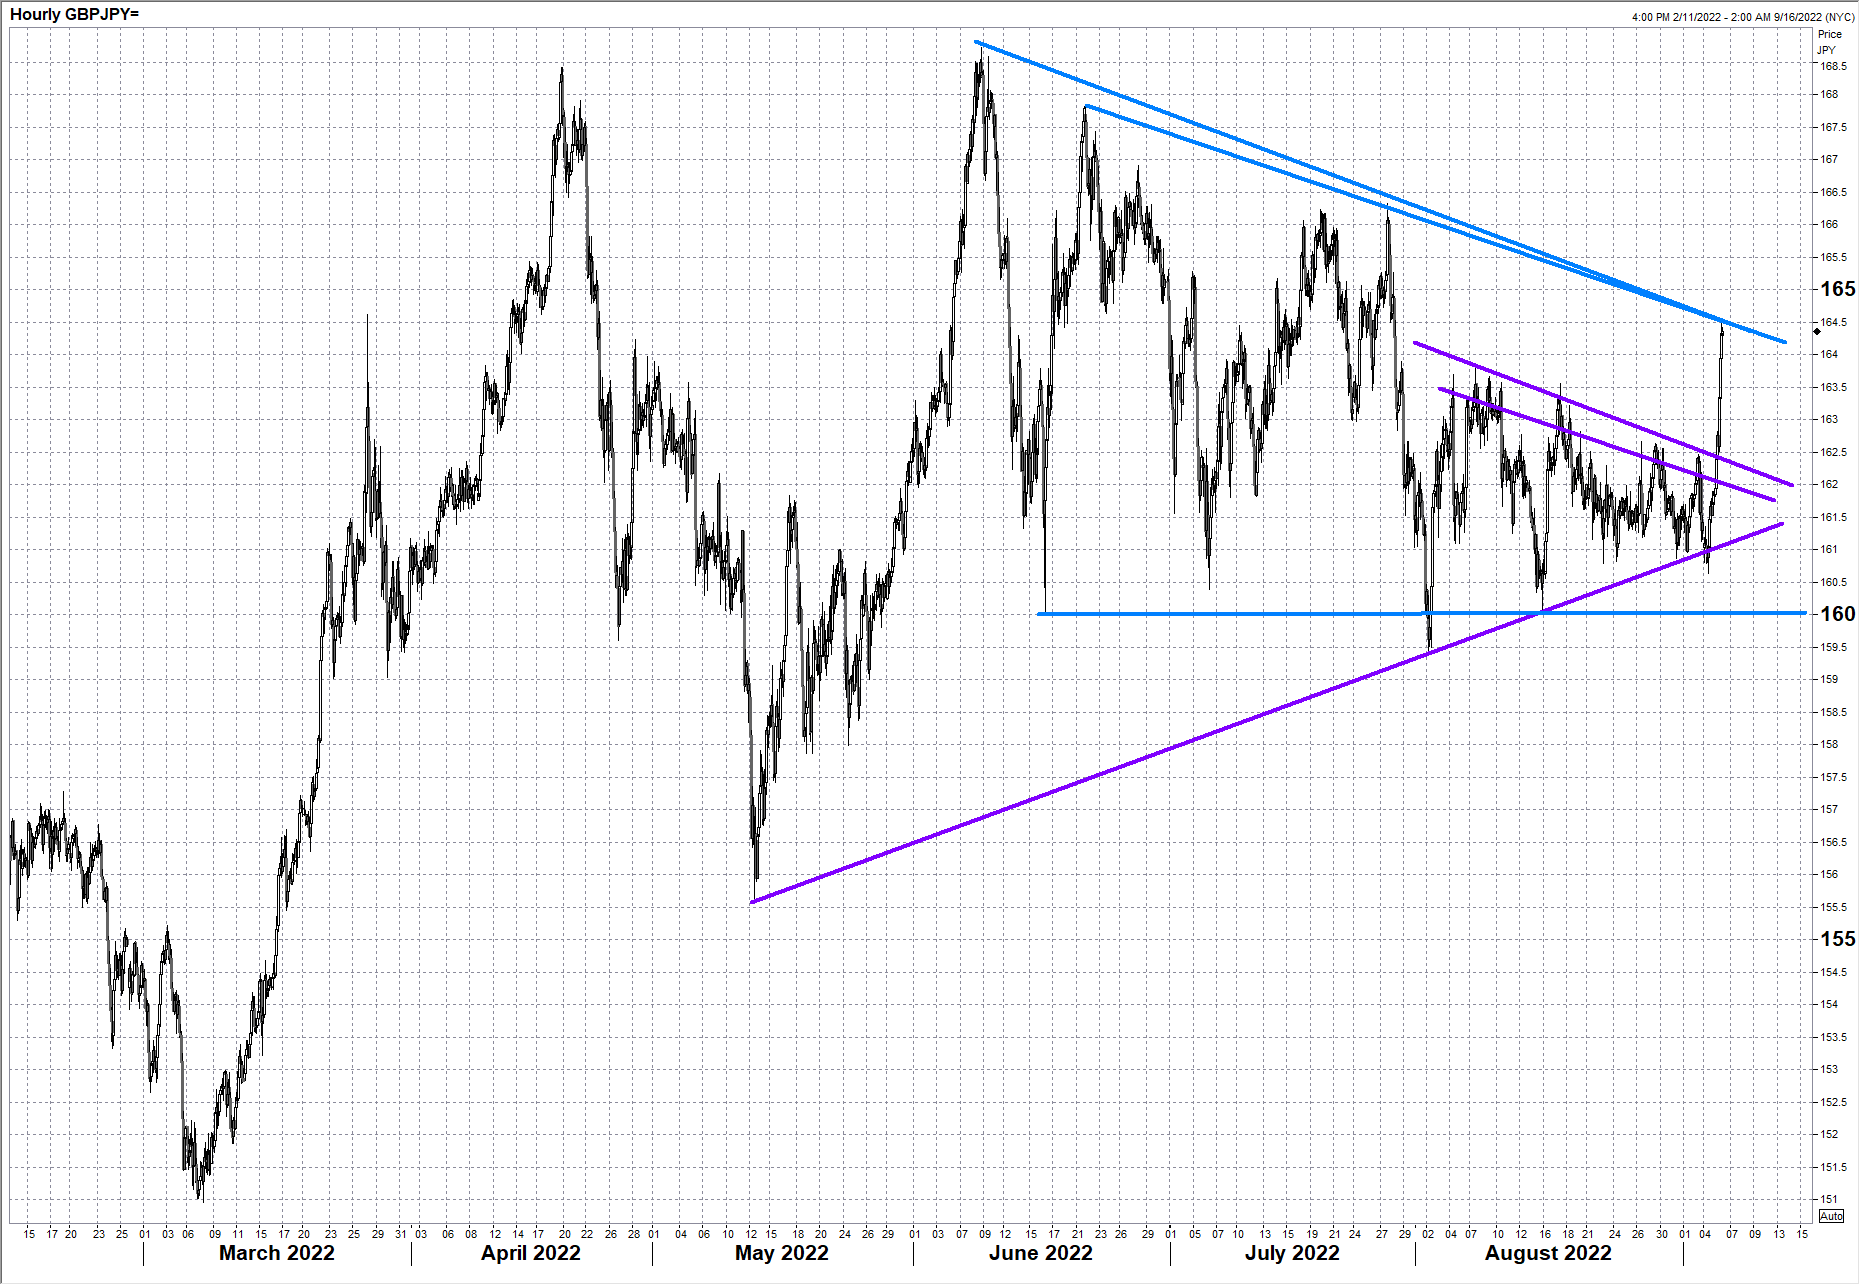
GBPJPY is particularly feisty off the 161 handle as the inside triangle I posted in yesterday’s piece (purple lines) has resolved like a meme stock upcrash. We are now right at the top of the bigger triangle (blue lines).
USDJPY is driving GBPJPY more than GBPUSD, and the question becomes: At what point does the BOJ say “no mas”? USDJPY intervention has historically been more about speed, not levels. Here is the 6-week change in USDJPY with some famous interventions marked:
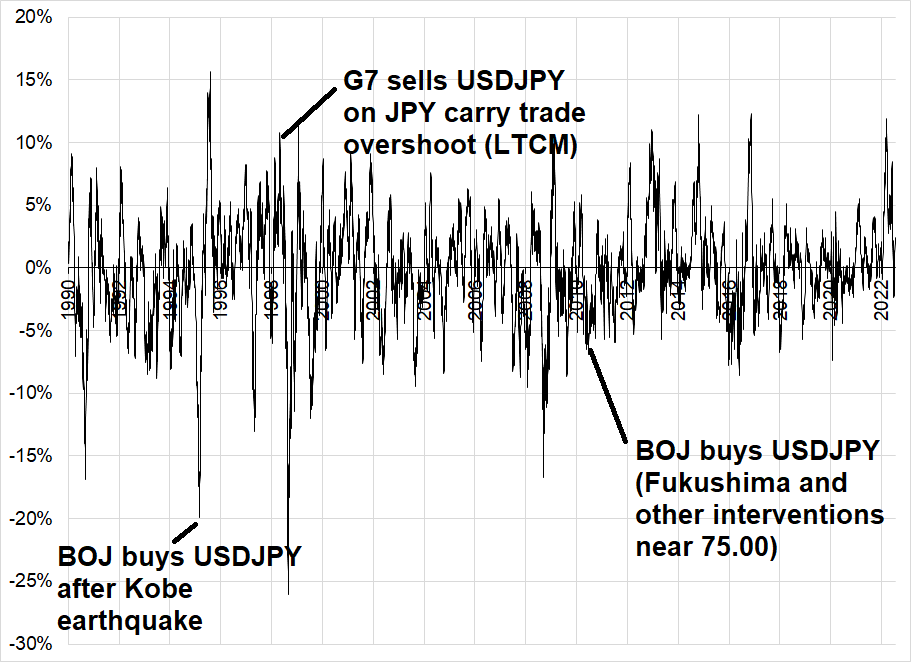
While it feels like it’s exploding moonward, USDJPY is only up 2% in the past six weeks. Interventions have come on moves of 7% to 15% in six weeks. The other condition that influences official JPY concern is whether it’s idiosyncratic JPY movement or a broad USD move. This is a broad USD move (EURJPY is unchanged over the past four months), so again, I don’t think there is anything particularly alarming about this USDJPY move if you’re the BOJ. The G7 would have more sympathy for the BOJ if their monetary policy wasn’t pedal to the metal in the opposite direction of the rest of the world or if the move was purely JPY.
I cannot remember a time in the past when the MOF was getting annoyed with the JPY while the BOJ was fully supportive of market moves. That’s a strange dynamic which means an open mind is warranted—perhaps at some point Suzuki will convince Kuroda-san that enough is enough. My base case is that Kuroda maintains yield curve control and the yen stays weak into February or March 2023. At that point, the market will start pricing Kuroda’s exit and removal of YCC. Still, you can’t rule out the idea that some arbitrary pain point hits in USDJPY, and the BOJ drops a trial balloon that begins a slow-motion rates normalization process. My guess is end of YCC = ~5%-8% 3-day drop in USDJPY.
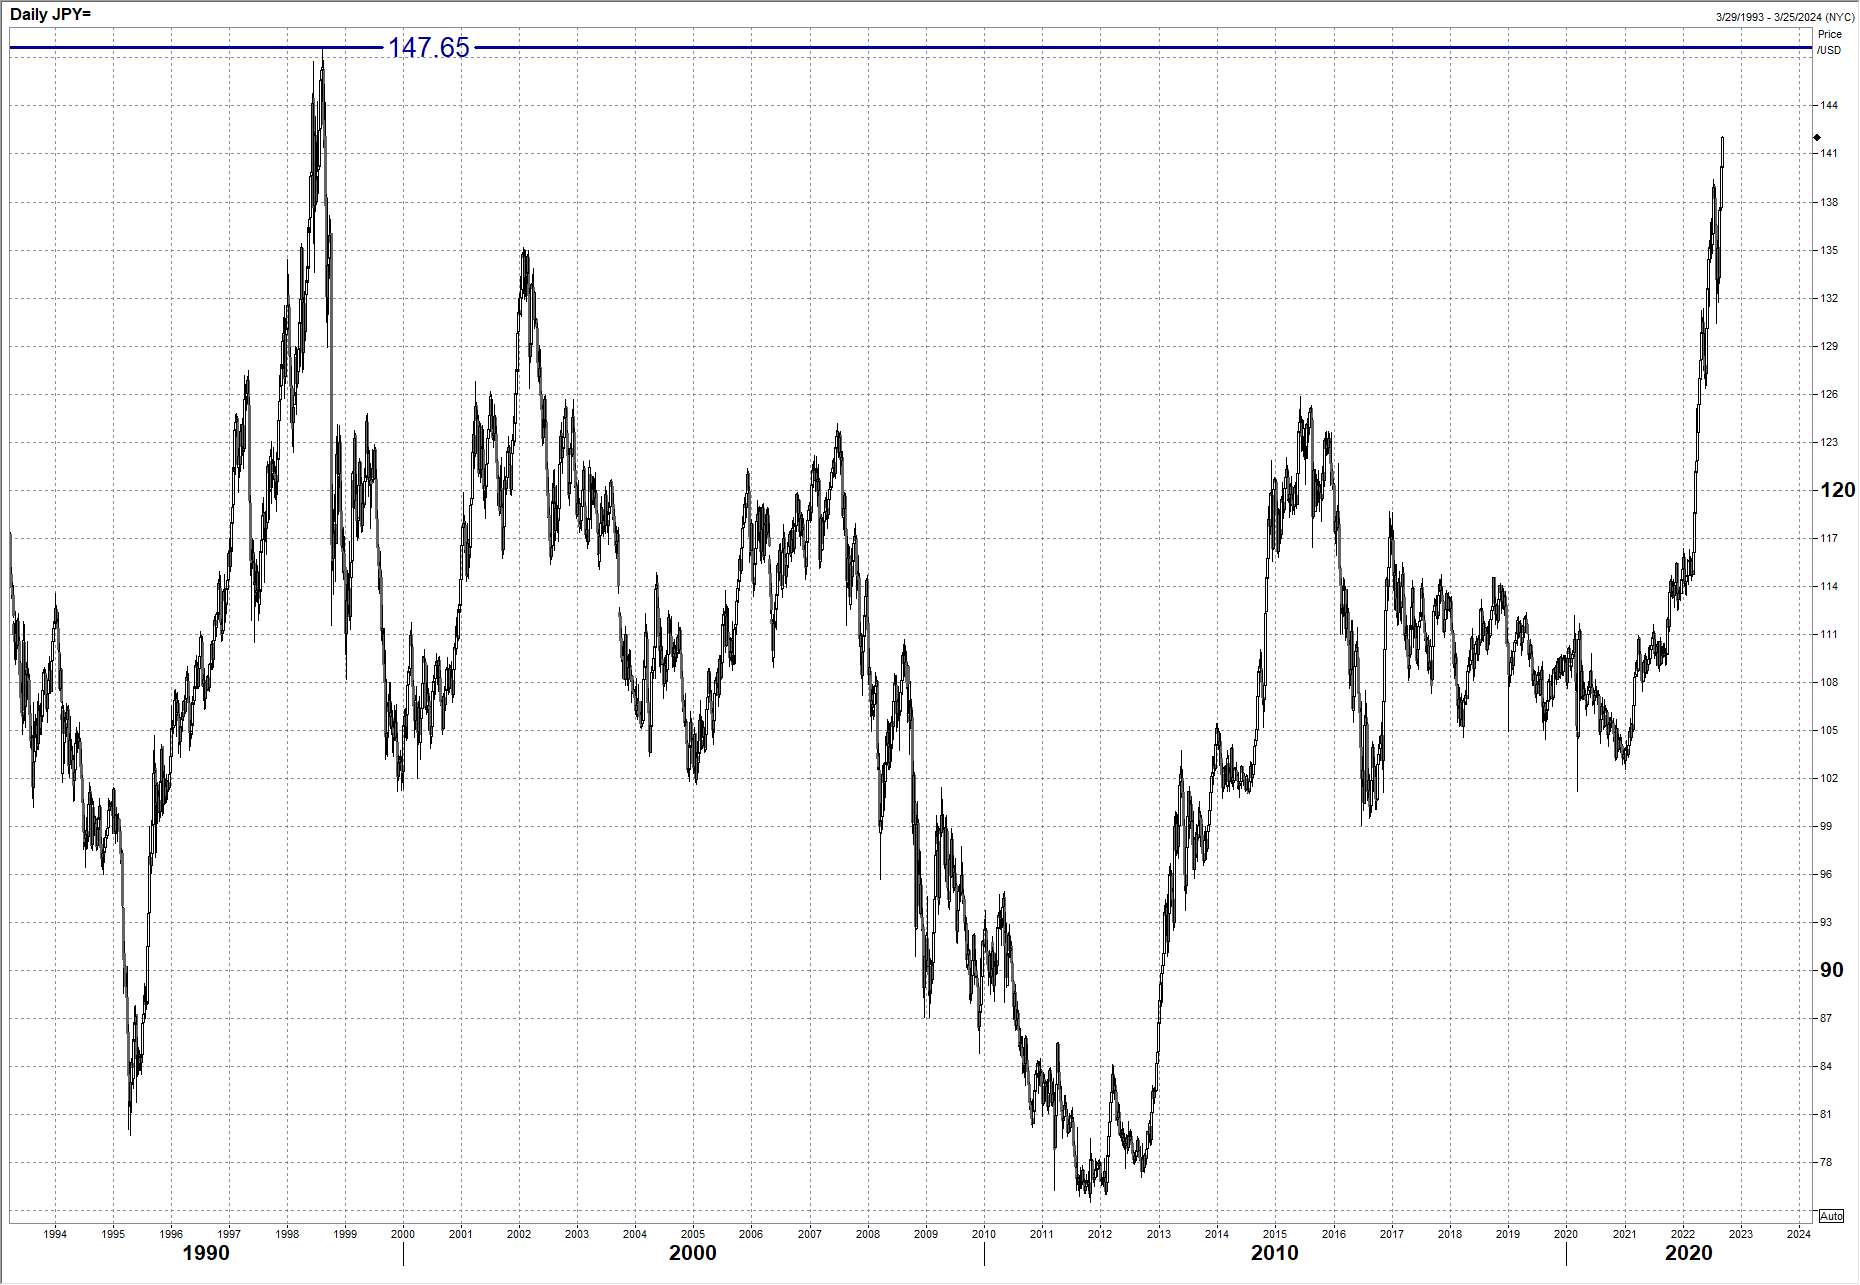
The USDJPY move down in 1998 (see chart above) was one of the most impressive moves in foreign exchange history. USDJPY went from 136.50 to 111.80 in three days. Anyone trading FX back then has some crazy stories and I have a few myself, including this one from June 1998.
INT. MERRILL LYNCH TRADING FLOOR – DAY

It’s 3 p.m. The trading floor is quiet and FX is barely moving. Out of nowhere, a bullish USDJPY headline appears: “G7 says weekend meeting will NOT discuss USDJPY selling intervention.” Fifty phone lines flash. Ringing. Yelling. Mayhem.

FX SALESMAN

Merrill.

CLIENT

Buy all the USDJPY.

FX SALESMAN

Umm... Sorry. What do you mean?

CLIENT

BUY. ALL. THE USDJPY.

FX SALESMAN

(yelling)

Buy as much USDJPY as you can, Stoney!

SJS does a round of calls and buys about 200 USDJPY. It’s instantly 200 points higher.

SALESMAN

You got 200.

CLIENT

<<click>>
Have a drippy day.

Barry’s got the drip
A sort of almost unbelievably large move in Brazil. Plus: Short CADJPY.

NZD has a bunch of bullish kickers: Election, seasonality, and inflation
