The loss of momentum in momo stocks is offset by the strong performance after CPI.
Fascinating thread about The Garden of Earthly Delights by Hieronymus Bosch

The loss of momentum in momo stocks is offset by the strong performance after CPI.
Fascinating thread about The Garden of Earthly Delights by Hieronymus Bosch
Stop loss 0.8479
Take profit 0.8694
CPI posted the smallest of beats yesterday and everyone is slicing the details to deliver the verdict of either “inflation is raging again!” or “all the inflationary things are BS, we’re disinflating”. The rally in stocks was moderately interesting as the initial and expected reaction function was that higher inflation is bad for stocks. Still, this is the sixth time in three years that we have had higher-than-expected CPI and higher stocks on the same day, so this isn’t exactly epic. Here is the subsequent performance of the SPX.
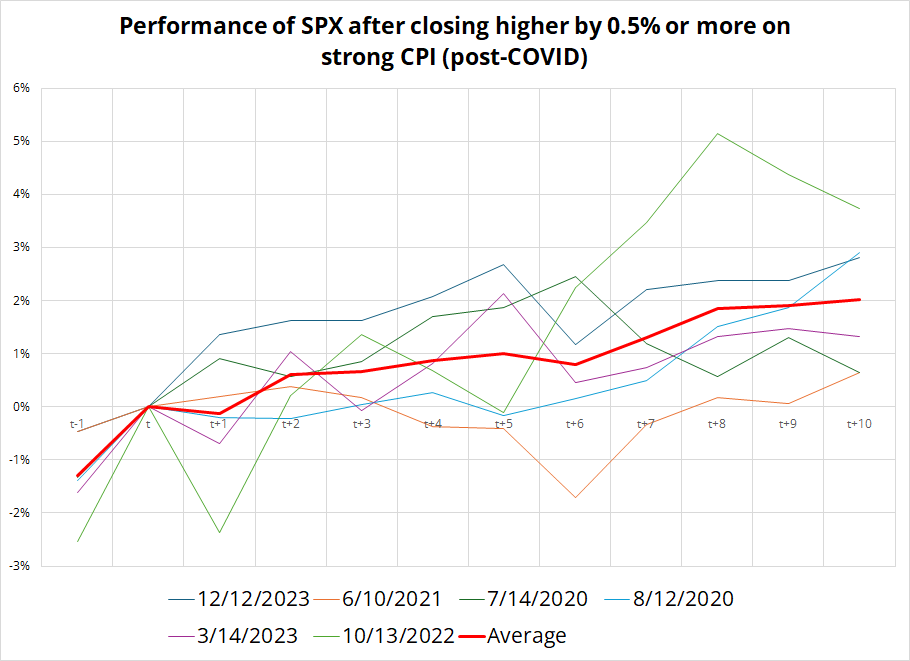
Somewhat bullish, because the average 10-day performance in the sample was +0.6%. That said, the day after the release (i.e., today) saw a couple of hiccups, and overall I suppose this is mildly, but not super informative. If you take this and combine it with the big turn in momentum in NVDA and NKY and the poor performance of MAG7 components like AAPL and TSLA, the short-term equity view looks mixed to me. Sure, NVDA has ripped back, but that scary reversal off 975 might put a few longs into sell rallies mode.
Equities and crypto are the only game in town right now, as FX remains in the doldrums and there is no data today. Copper has launched out of a huge triangle, so maybe that will keep the related currencies (AUD and EM) underpinned, but CPI has come and gone and the Fed and ECB are now scheduled to execute their coordinated rate cut in June.
Bond and equity vol are low. FX vol is lower. Here’s the latest from the ECB:
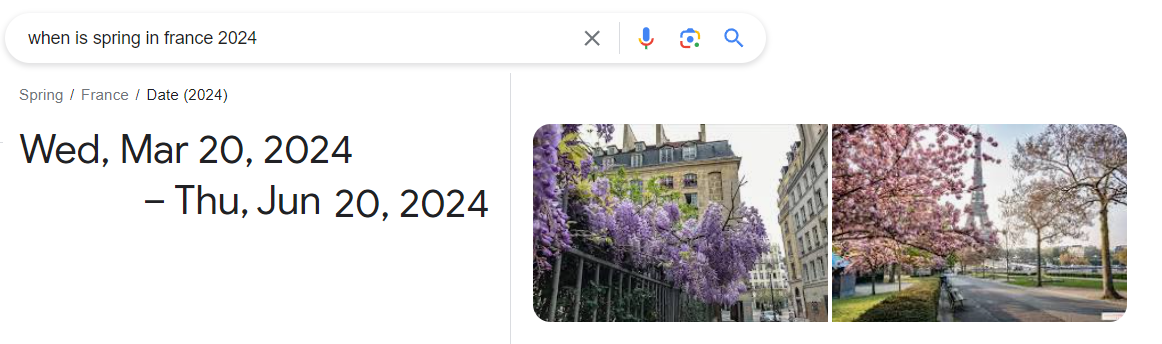
The European Central Bank will probably start cutting rates during the spring, as the “victory” against inflation is in sight, French central bank head and ECB policymaker Francois Villeroy de Galhau said on Wednesday.
“The consequences we, at the European Central Bank, should draw is probably to cut rates in the spring and I remind you that in France and Europe this is a season that lasts from April to June 21,” he told France Info TV.
That is a random comment given the ECB meeting is June 6, and Spring ends on the 20th this year, but OK!
The US is now priced for 76% chance of a cut by June while the ECB is priced for 91% and the Bank of Canada at just 57%. All three are more than fully priced for a cut at or before the July meetings. As I have said before, this could be the classic “we’re cutting in three or four months” rolling to the right by 3 or 4 months, every 3 or 4 months. Waller teed up the March 2024 cut in November 2023 and now it’s March 2024 they are teeing up the June 2024 hike. The data, not the central banks, will decide when rate cuts happen.
Nice blog post from Alpha Architect about how retail investors overpay for short squeeze candidates:
Key takeaway:
Short squeezes are often associated with a large positive jump in the price of a stock. Filippou, Garcia-Ares, and Zapatero demonstrated that skewness-seeking investors try to identify securities that could experience a short squeeze in the near future and are willing to pay a premium for them. That results in an overvaluation of the options and, on average, negative returns. Investors are best served to avoid investments with lottery-like distributions. One way to do that is to turn a blind eye to social media sites like Robinhood and Reddit so you don’t get caught up in the hype and excitement. That’s another example of why retail investors are called “dumb money.” Forewarned is forearmed.
Have a surreal day.

Surrealism in the 1500s! Who knew?


A sort of almost unbelievably large move in Brazil. Plus: Short CADJPY.