It’s France’s turn to get a flogging.
Hello. It’s Friday. Thanks for signing up. I’m Brent Donnelly.
The About Page for Friday Speedrun is here.
It’s France’s turn to get a flogging.
Hello. It’s Friday. Thanks for signing up. I’m Brent Donnelly.
The About Page for Friday Speedrun is here.
Here’s what you need to know about markets and macro this week
The Deficit Panic Wheel of Misfortune lands on French bonds this week as the market logically wonders where the bottom might be for OATs.
OAT stands for: Obligation Assimilable du Trésor, i.e., France’s 10-year government bond. And the price action has not been pretty. Here is the yield spread on the 10-year OAT vs. German bunds:
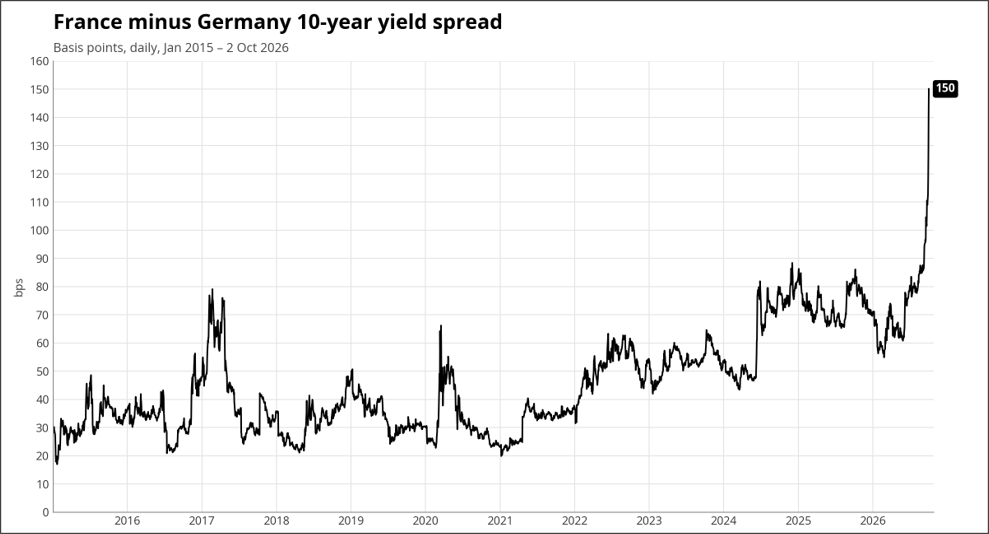
And here’s a zoom out.
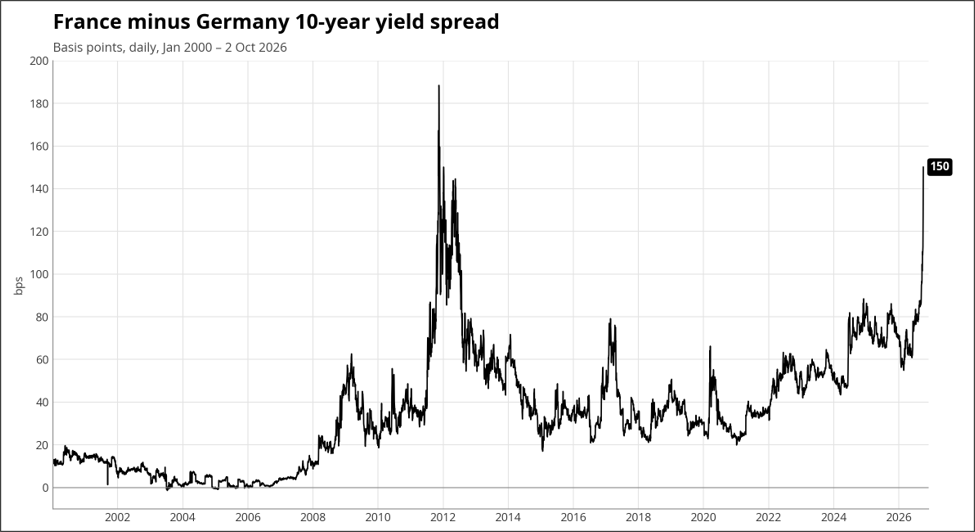
The French politics trade that many expected would escalate this winter as April 2027 elections neared… Is here now. It’s not completely obvious what might fix things here as any budget promises made by the French government now are not super credible with a change of power coming soon. They can do the old “we promise to get deficits below 3% in two years!” thing but nobody is going to give those promises any weight. The ECB is somewhat constrained from intervening still, but verbal intervention noise will pick up from here if things don’t soon improve.
Before the French kerfuffle started, we were watching the Fed as they slow played the rate hike and finally went in September—then quickly ran out into the streets to provide forward guidance in an attempt to rein in October hike pricing. This Fed feels exactly like the Yellen Fed. Dovish hikers to the core.
A more hawkish Fed was supposed to be the cure for high back-end yields, but that has not been the case so far. The roaring real rate story refuses to cool as you have SOOOO many bond bearish factors all converging at once:
The French said it about their deficit too this week:
*LESCURE: FRENCH BUDGET DEFICIT OF 3% IN 2029 STILL POSSIBLE
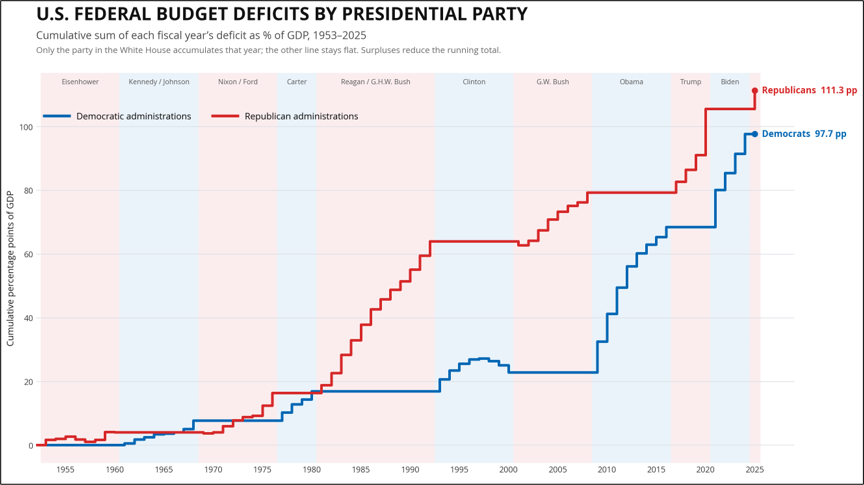
Every Republican administration massively increases deficits and every Democrat since Clinton has done the same. And it’s not just the U.S. that has gone Barry. The market’s stinkeye flicks round and round the room—from the U.S. to Japan to the U.K. and now on to France. You’re next, Brazil! Starting in 2020, the sovereigns started gobbling up all the private debt. Now they are choking on it.
On the podcast with Alf today, I said that I don’t like trying to pick a bottom in bonds because there are so many factors hitting all at once that if I go long bonds, I don’t know what I am cheering for. Weak U.S. data certainly hasn’t mattered this week, for example. My best trades have a clear catalyst and a clear “I’m wrong if” and right now all I can really say is: “Man, bond yields are juicy.” That might be good enough for your 401k, but it’s not good enough for a trade.
Seasonal equity weakness never showed up and now the bears are left with a grab-bag of bricks with which to build their wall of worry, but not enough bricks to stop the indices from roaring back towards the ATH. Yes, breadth is terrible, but it’s been terrible many times through this bull market and it eventually resolves with the rest of the market catching up to the indexes, not the indexes catching down to the majority.
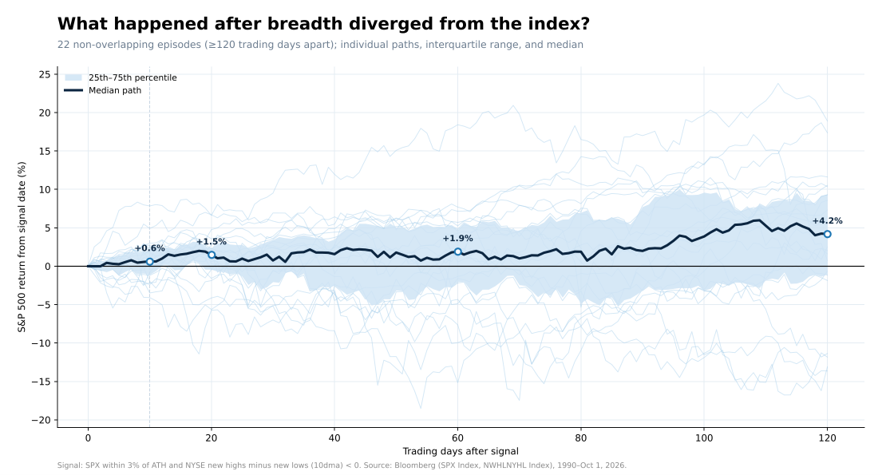
If we create an event study, you can see there is a mild bearish angle for the near future, but bad breadth tends to be a feature, not a bug in bull markets.
Here are some times when breadth was super bad like it is now. The study flags the following:
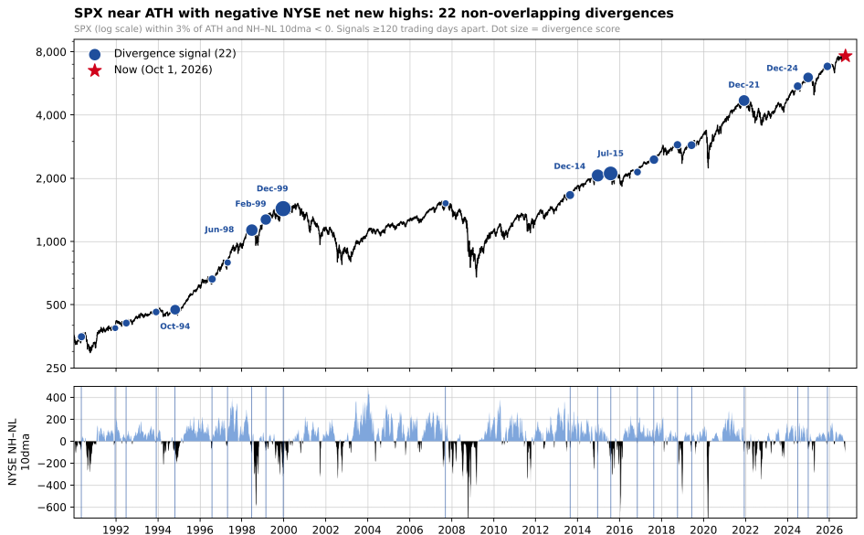
So, you can see there are some short-term turning points in there, but also trend continuation. Here are the forward (non-overlapping) returns of the signals. I compare a) signals, b) all other times we were within 3% of ATH (but no signal), and c) all other days.
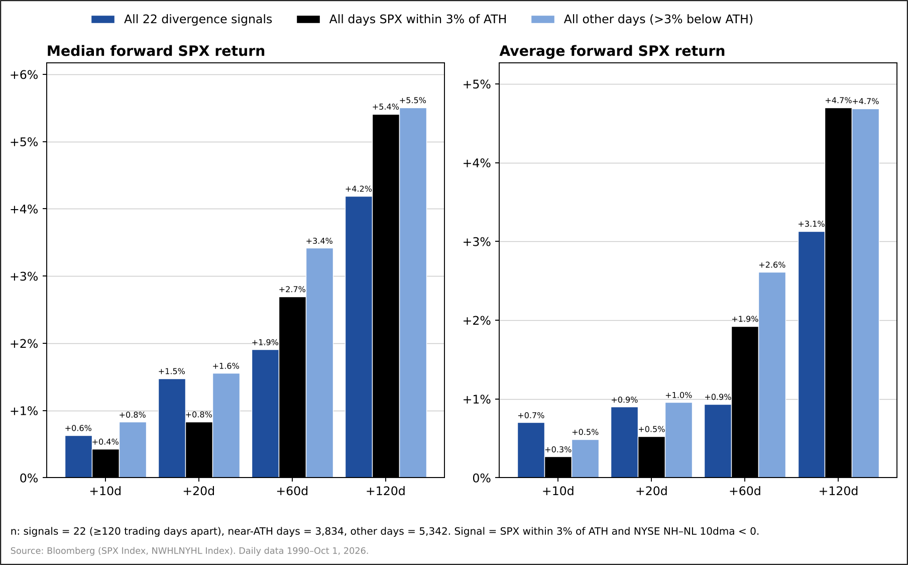
The takeaway is that this sort of bad breadth setup is not bearish, historically. In fact, the bad breadth setups have better returns than the other times when SPX is near the highs.
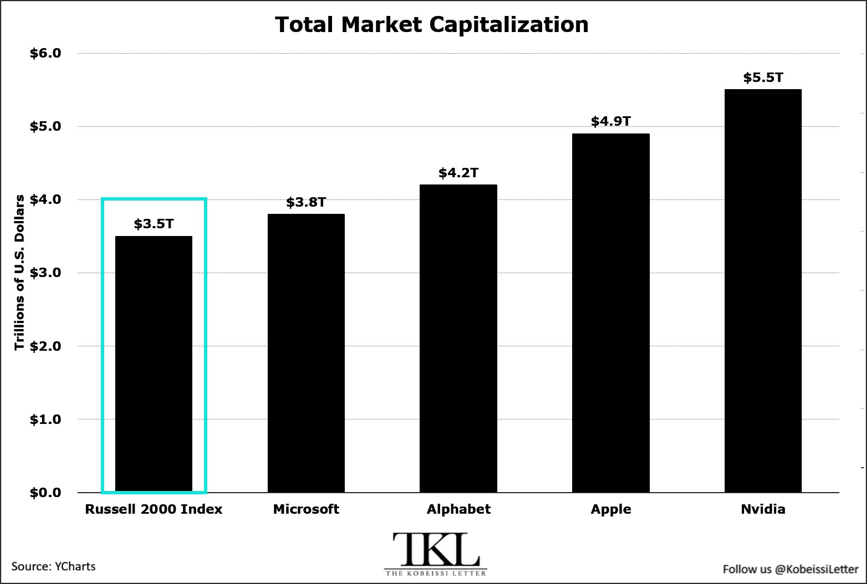
I am not convinced that French budget woes are going to lead to worse earnings for META and therefore all this tightening in financial conditions around the world is still a bit hard to get excited about. Is there a read through to stocks? Yes. Housing and banks and small caps have not been having fun lately. Is there a read through to the indexes? No. The entire equity index is a bet on whether or not AI will pay off. Mortgage rates are not part of the answer to that question. Funding costs are a rounding error. The real question is about AI revenues and we have no visibility yet.
Here’s some perspective from TKL on why small caps can drop 10% and the indexes don’t care.
Here is this week’s 14-word stock market summary:
Plenty of reasons to be bearish. But the path of least resistance is up.
The Fed are rolling out the speakers to push back on the October rate hike but bonds can’t rally on dovish or hawkish central bank speak. We are now up in a new layer of the atmosphere as U.S. 10s cleanly breach 5%.
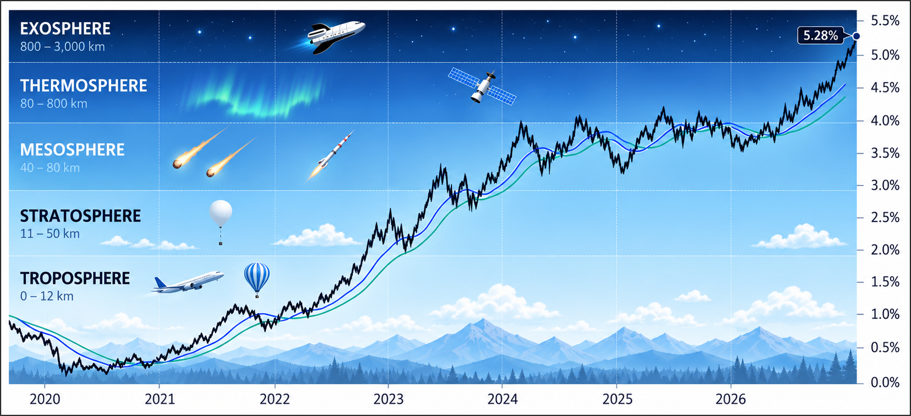
What is above the exosphere?
There is no sharp boundary to where bond yields must stop. They can keep drifting up through the magnetosphere. If you zoom way, way back in, you can see that today we had a soft jobs report, and higher yields. Good news / bad price for bonds.
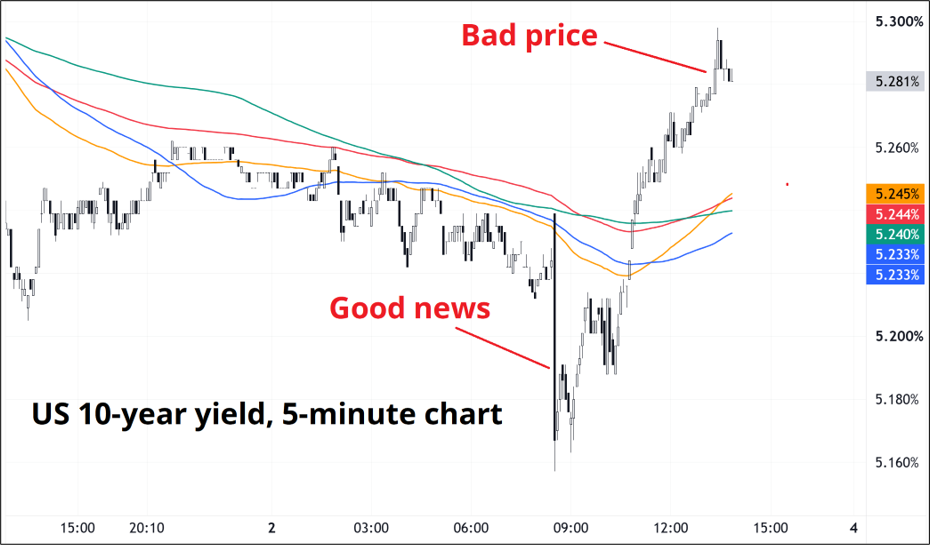
A dozen-plus factors all point to pressure on bonds. Technical levels last touched before the iPhone came out feel rather arbitrary at this point. So, the best approach to bond trading is to stay away and wait for something special to happen. A government intervention, a massive outside day on record volume in TLT, etc. Here I see no trade.
Sincere congrats to Jim Bianco who has nailed the bearish bond call for eons and now has turned bullish bonds. Jim’s a cool guy and a real professional.
This chart is neat. Nice try, SNB!
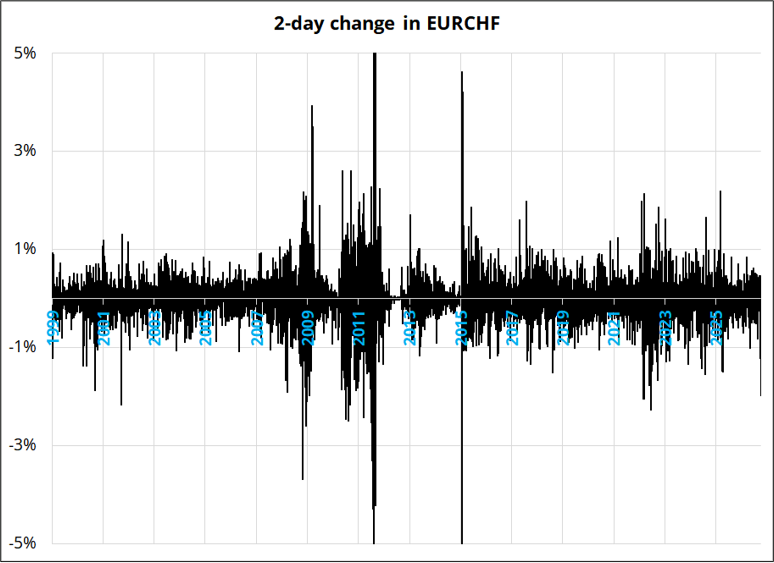
That black bar on the far right is a 2% move lower in EURCHF since Wednesday and when the thing is trading on a 4% vol, that’s a 6-SD move. I don’t want to get into the boring conversation about fat tails and how financial markets are not normally distributed and all that. Let’s just say, when it comes to standard deviations and financial market data:
IT’S A HEURISTIC!
Yeah anyhoo. The euro is following French spreads, just about tick-for-tick, as you can see in my next chart. It shows EURUSD vs. France spreads and you can see that the market erroneously tried to trade EURUSD off U.S. data (weak Core PCE) for about 15 minutes there on Wednesday.
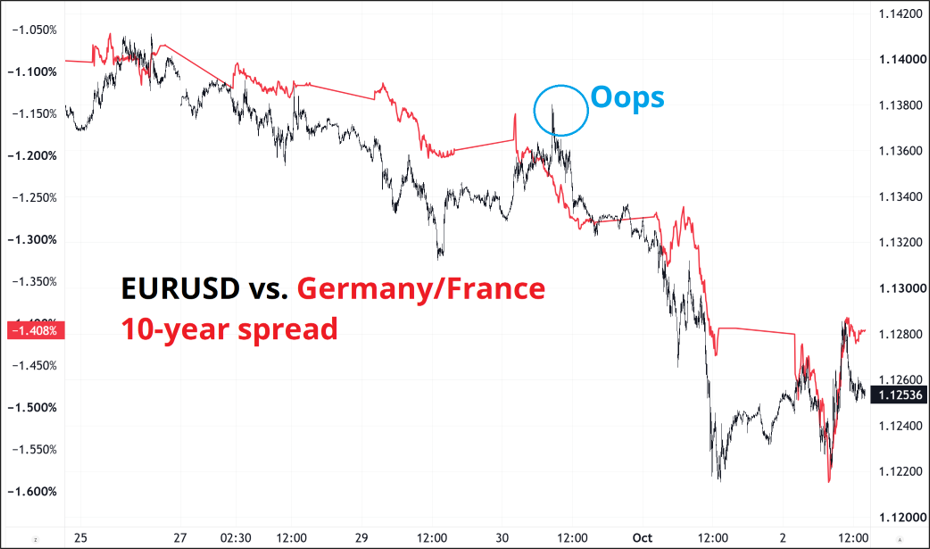
Spreads ripped tighter on no news today as the market covers shorts into the weekend. During crisis periods, weekend risk tends to be bullish because policymakers huddle up and make soothing statements on Saturday and Sunday. If they can. It’s not hard to imagine a soothing statement from French politicians this weekend, for example.
If you want a full menu of what might help French spreads, here’s an excerpt from today’s am/FX:
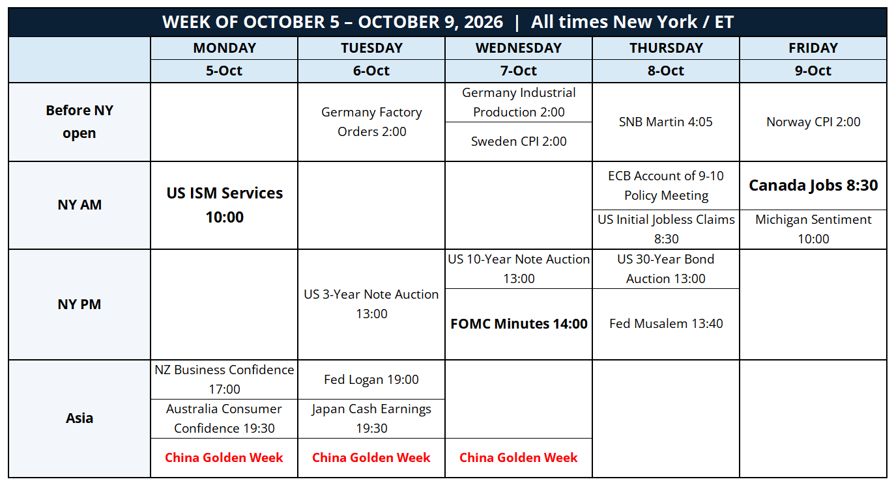
Here’s next week’s calendar. It’s a dud:
HEY! If you’ve read Trade Outside the Box – please click here to leave a quick review. Thanks! And if you have not… Buy it here:
TRADE OUTSIDE THE BOX: Advanced Thinking for Professional Traders.
Here’s the one-pager.
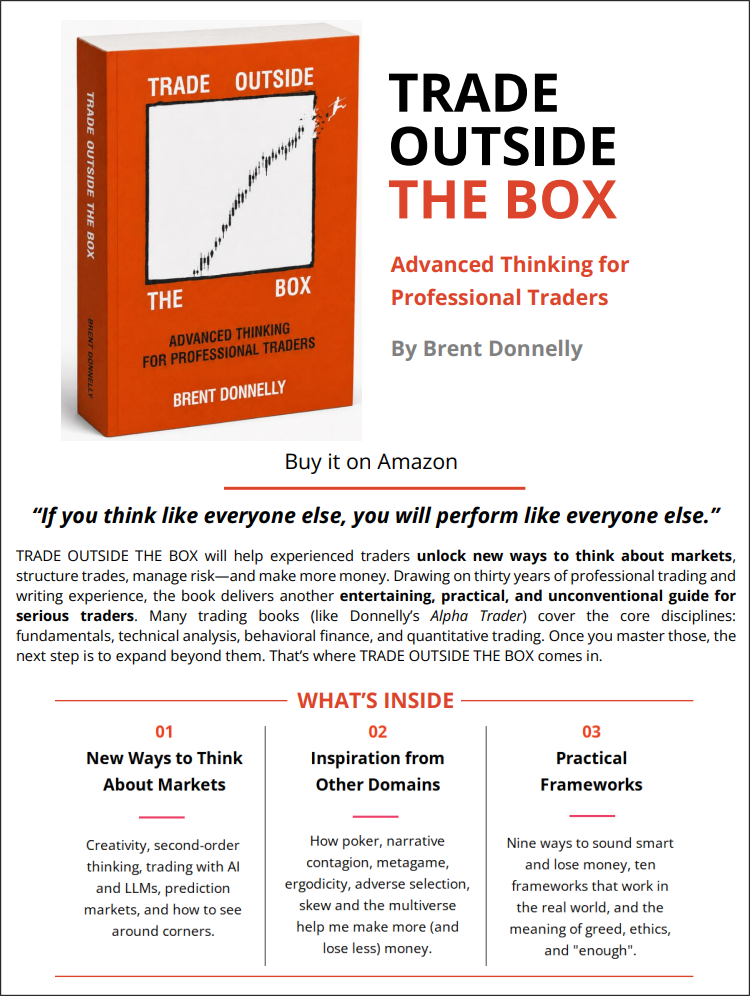
The book is written for experienced traders. If you are new to the game, I would suggest you start with Alpha Trader. If you have been trading or investing for more than five years, this book is for you (and you don’t need to have read Alpha Trader to enjoy it).
The qualifying Bart pattern I wrote about on September 11 followed the historical script and broke out to the topside!
Barts are bullish, baby. The crazy thing here is that we have formed another Bart next to the first Bart!
Siamese Barts! Conjoined Barts!
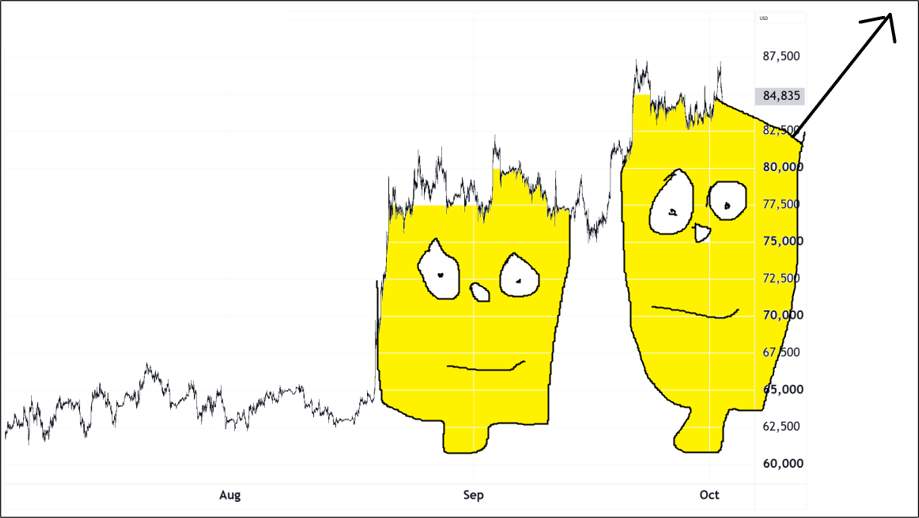
My art skills are down bad this week because I am actually quite busy at my real job today, thank you for asking. If you are reading this and don’t know what I am talking about and feel like this…

You can go back and read the original article here (see Crypto section).
Barts are a continuation pattern.
And it’s Uptober, ofc.
All the cool kids are talking about diesel now as Persian Gulf crude flows are back to normal and apparently that chart of Hormuz passages didn’t really have any usefulness for anyone trying to predict energy prices.
GS offers this chart:
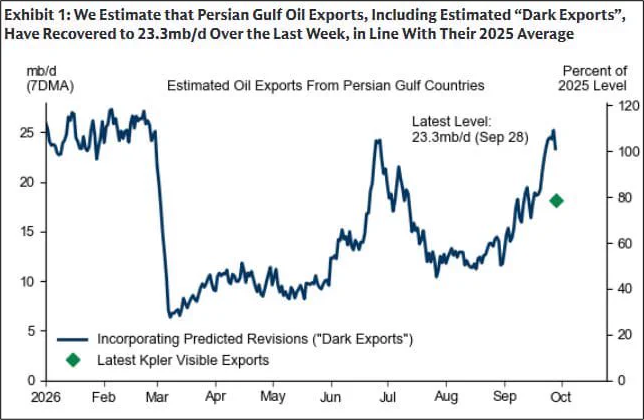
Problem is that absolute flows are not really the story as various products are in shortage and refining capacity and etc. etc.—this is too boring.
Diesel! El Niño! Diesel! Copper triangle!
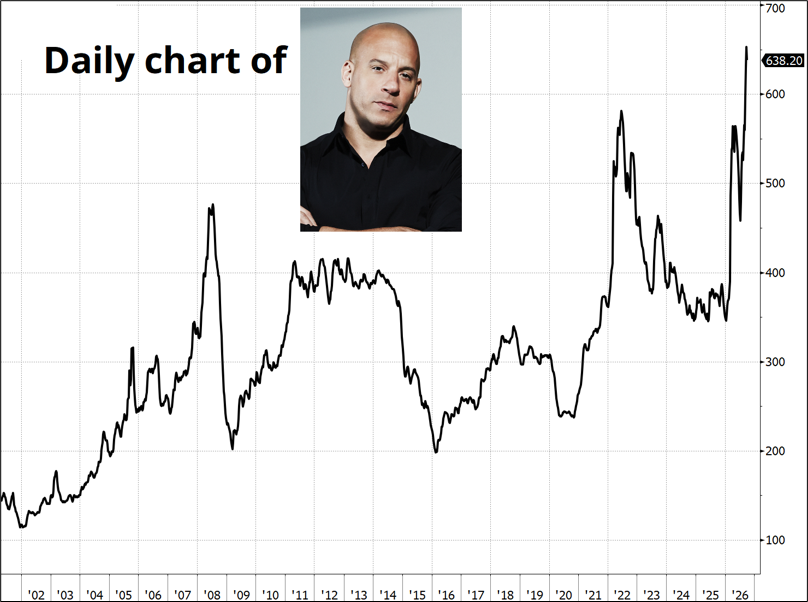
I watch energy prices, but I don’t predict them.
Finally, gold, which was benefitting from falling Fed credibility as the FOMC passed in June and again in July, flipped back to the downside now that (maybe?) the Fed might hike enough to get inflation back to target. Gold and silver look tired and it’s useful to remember that once a bubble bursts, a new, strong bull market rarely ensues afterwards. You usually get months or years of painful chop.
That’s it for this week.
Get rich or have fun trying.
*************
*************
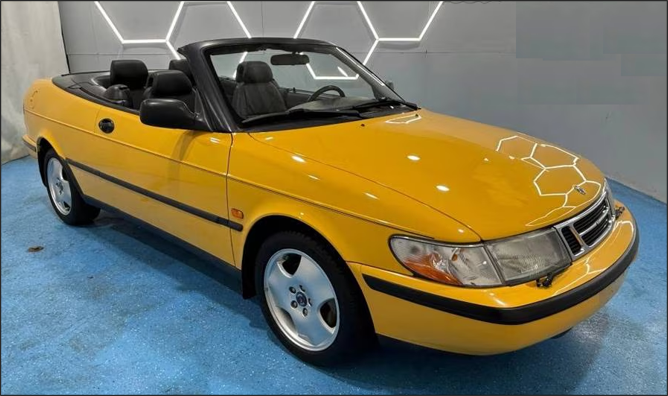
This car is pretty dope for under $20k. 1998 Saab 900 convertible.
*************
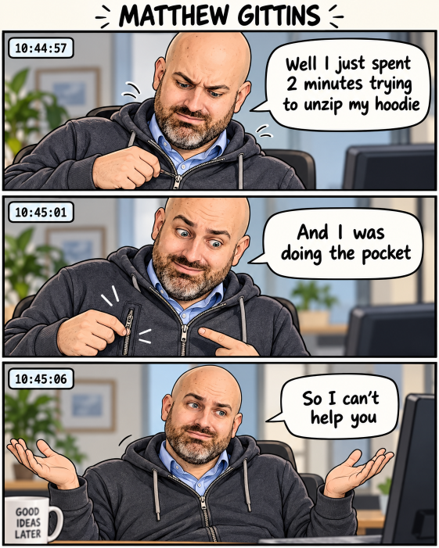
Matt Gittins admitted to a dumb mistake he made as I was Bloomberg chatting with him yesterday and I cut and pasted the chat into ChatGPT and the output was comedy perfection. The timestamps, the facial expressions and the mug—all flawless.
*************
The only thing crazier than granting personhood to corporations is to grant personhood to AI entities. Here’s an article about that.
*************
A very nice piece here with one of the best American authors. A 10-minute read. It is an interview with George Saunders on AI and writing with AI. His frankness and absolute belief in humanity are commendable.
*************
Thanks for reading the Friday Speedrun! Sign up for free to receive our global macro wrap-up every week.