NFP matters but not as much as CPI
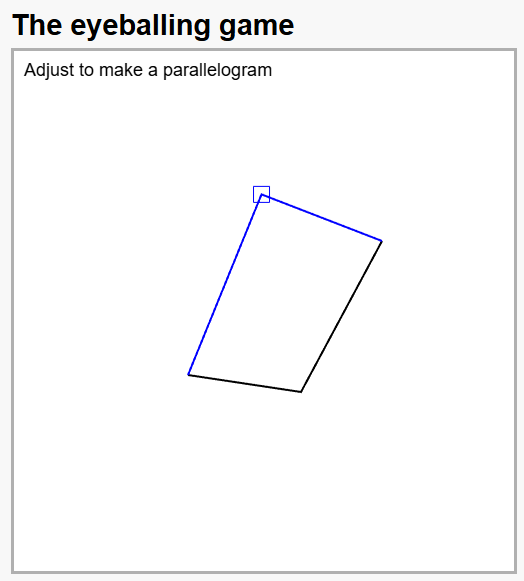
This is a simple and fun game if you have 90 to 140 seconds to kill.
https://woodgears.ca/eyeball/index.html
HT Nirav
NFP matters but not as much as CPI
This is a simple and fun game if you have 90 to 140 seconds to kill.
https://woodgears.ca/eyeball/index.html
HT Nirav
Buy USDJPY @ 153.60 (limit order)
Stop loss 151.64
10SEP CHFJPY put spread
199/196 for ~37bps off 200.50 spot
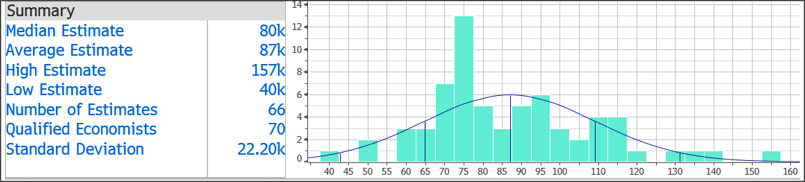
Here is the distribution of economist forecasts for NFP.
And here is the implied distribution of expectations if you combine Kalshi and Polymarket data:
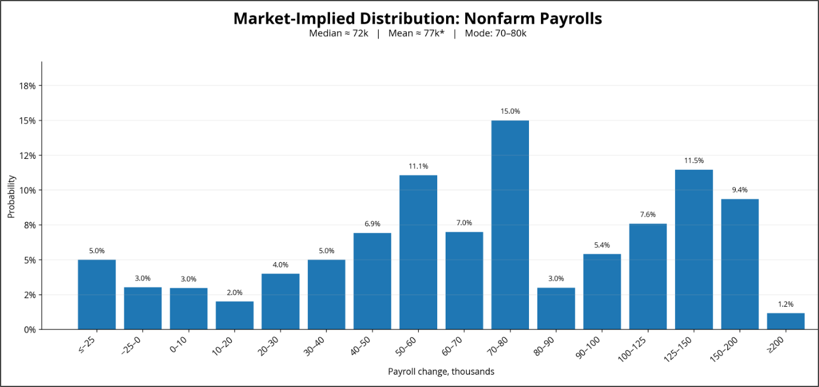
You see the normal story with the economist forecasts: they herd towards a central cluster at the median, with very few outliers. The skew is to the strong side, as it is with the gambling odds, and there are two main clusters, one around 80k and one around 135k.
There are plenty of things to consider going in, particularly the -61k drop in leisure and hospitality (in contrast to a hiring boom expected by economists). The reality of mega events like the Olympics and World Cup is that their effect on tourism and employment tends to be exaggerated because they raise prices and crowd out normal tourism, leaving a landscape of more expensive, but not more crowded hotels. At some point, the 61k will come back, but it could be this month or next month (or it could be real, but I doubt it).
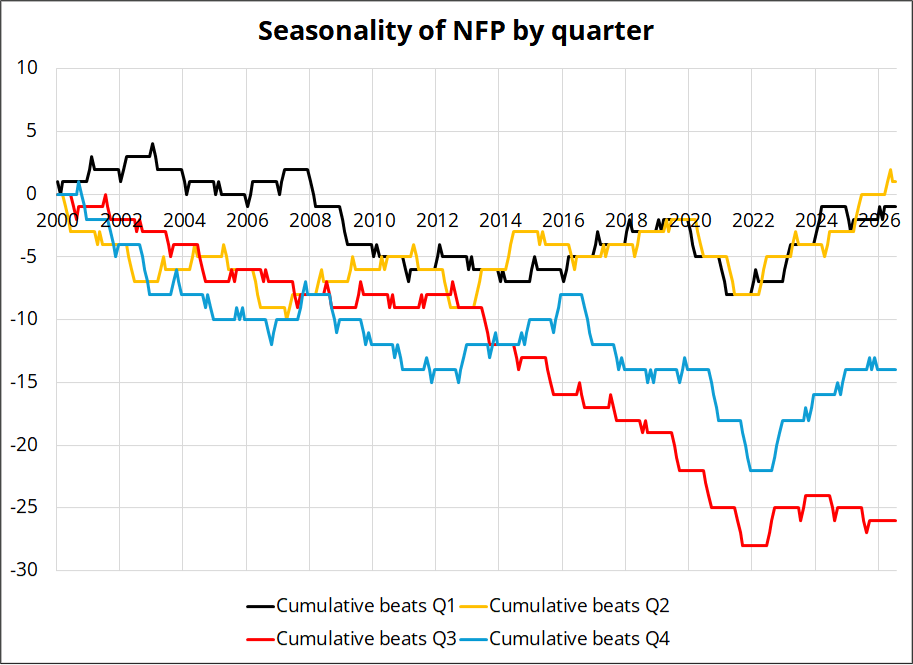
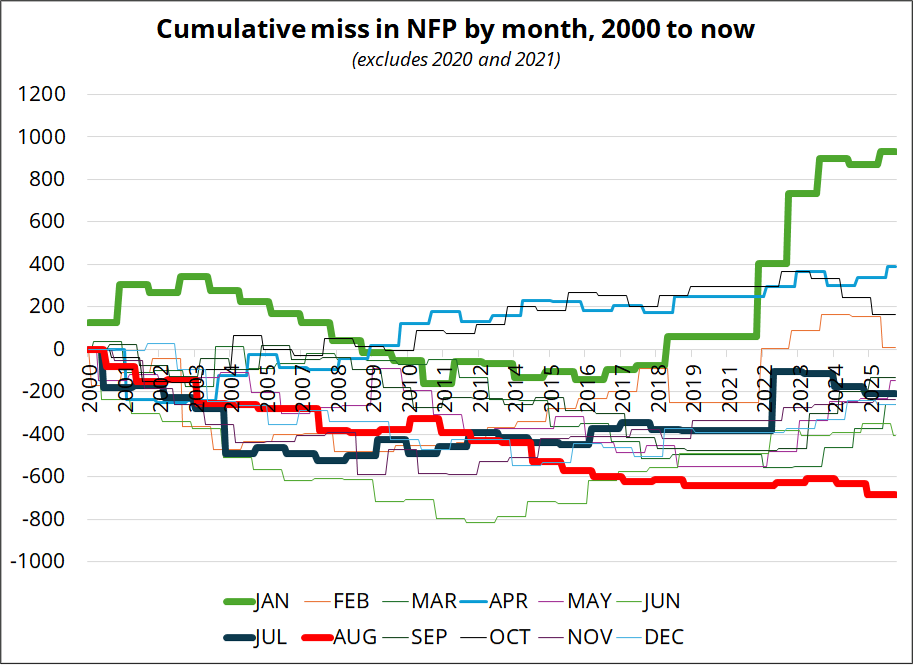
If you look for anchoring bias, or uncaptured seasonality, or clues from claims, ISM employment, or ADP, there are a few clues, but not many. For example, there is a persistent uncaptured weak seasonal in Q3 and particularly in August (next month’s release) and January has been a huge upside surprise since COVID.
Here you can see the weakness in Q3.
And here’s the monthly data. Need to keep in mind there is a good chance some of this is fooled by randomness, but the pervasive economic “strength” in Q1 post-COVID is almost certainly a failure to seasonally adjust correctly after the pandy. You can see July is neither here nor there.
Note the distribution of forecasts for the Unemployment Rate (using Kalshi and Polymarket) falls off a cliff after 4.3%. I suppose you could argue, then, that 4.4% is much more of a surprise than 4.1%, even though pretty much every economist is either at 4.2% or 4.3%.
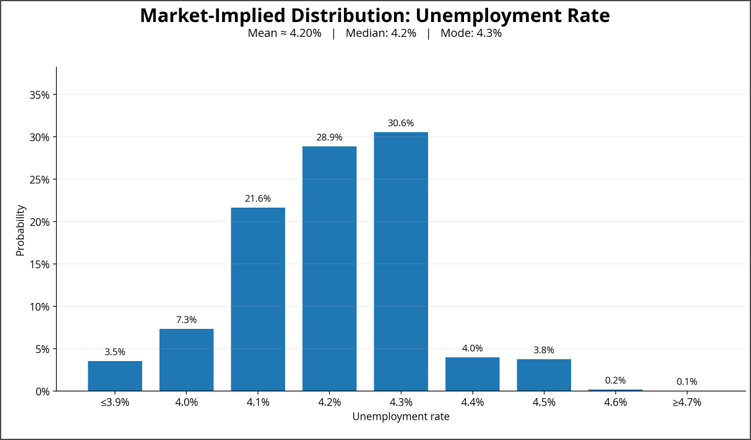
With September FOMC 50/50 and Warsh probably not immune to the barrage of questions about his inflation-fighting credibility, a strong jobs report is likely meaningful for the Fed and for Fed pricing. There is nothing out there that suggests any serious weakness in the jobs market, but it’s also worth remembering that breakeven NFP is super low, like 20k-50k, so 80k and 4.2% UR is a tight jobs market, not a loose one.
A strong NFP is most likely good for the USD and bad for bonds, but I don’t think it’s bad for stocks. We are talking about a tiny rate hike cycle here; even Kashkari, who dissented, is talking about a hike or two or max three. The economy handled 500bps of increases in 2022/2023 and now the Fed is simply fiddling with the dial by cutting or hiking a few times here and there. These are meaningless tweaks to the policy rate in a world where transmission from U.S. monetary policy to the U.S. economy is almost completely broken. It’s probably unfortunate that we spend so much time talking about the Fed when their policy really doesn’t impact the economy or inflation much or maybe at all. Anyway, I rate NFP a bit below CPI, but it’s still important.
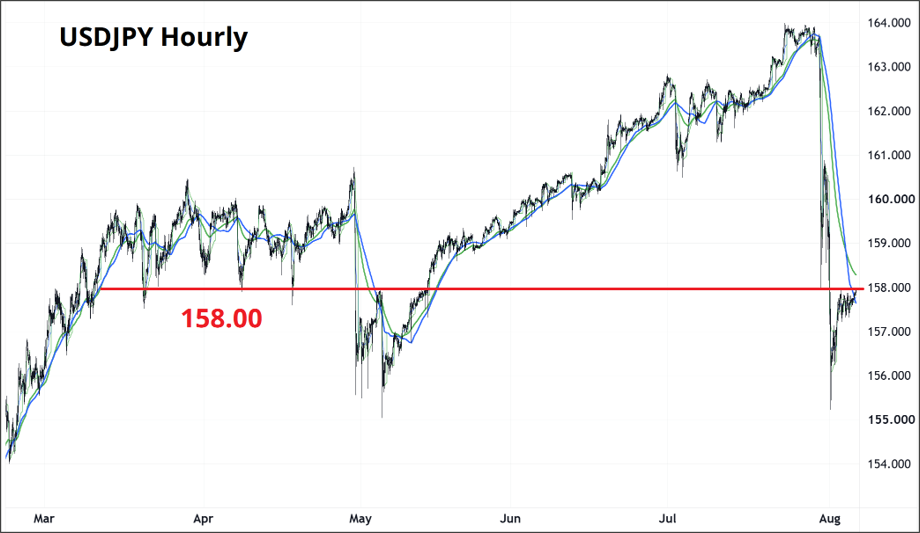
The most interesting aspect of NFP tomorrow is that a strong number could take USDJPY back up towards 159.00/50 and put the MOF and U.S. Treasury in a bind. Bessent’s small numbers (on the notepad, and in calling it a reserve switch) sucked some credibility out of the coordinated intervention strategy and if the U.S. prints a barnburner on jobs tomorrow, it gets a bit confusing. They can’t just walk away, of course, but they also can’t intervene every day.
Last Friday, when they were intervening aggressively after 4 p.m. NY, it looked like a concerted effort to get USDJPY through 158.00 That has been a big level on many occasions as you can see in the chart. 158.00 was the base in March/April, then the MOF intervened and it became resistance. Then, in mid-May, USDJPY ripped through 158.00 and never looked back. It was the low on the first intervention last week, and it’s where the 100-hour MAs come in now. Huge level.
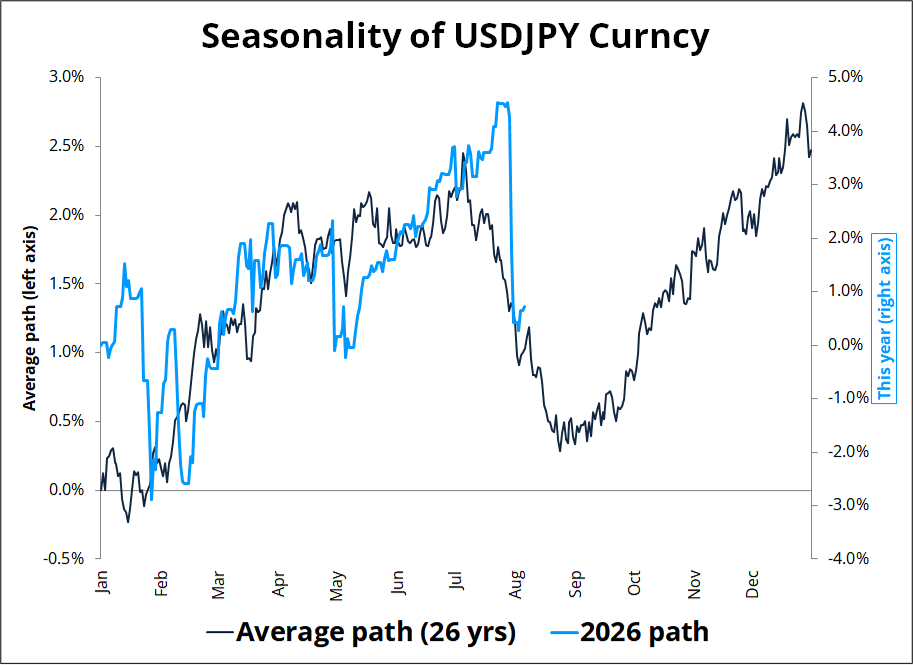
And in case you are wondering, the bearish USDJPY seasonality continues until August 10. Here is the average path of USDJPY since the year 2000 and this year’s path.
A couple of scenarios worth considering.
I would rate these as 15% and 30% probability. That is, assuming that NFP is weak, I think there is a 30% chance MOF comes in and piles on.
This is a simple and fun game if you have 90 to 140 seconds to kill.
It’s from a woodworking for engineers website.
https://woodgears.ca/eyeball/index.html
I am not good at this game.
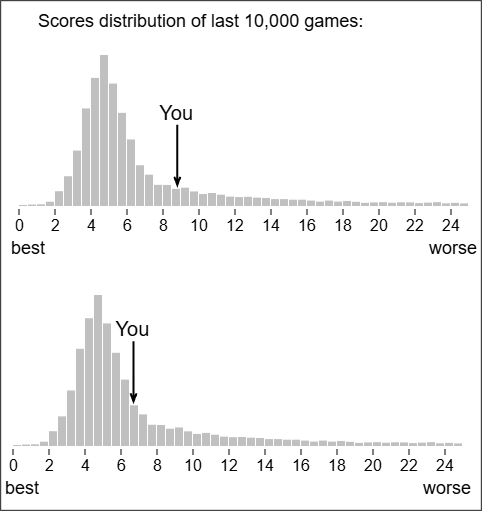
By “You” they mean me.
HT Nirav